
Is now the right time to get into the markets?
With risk assets having pushed into bear market territory in May, some investors are asking whether now is the right time to get into the markets. On one side of this debate is a group of investors who look at the recent pullback as an opportunity to buy securities at a discount. On the other side is a set of investors concerned that prices will only move lower from here. Make no mistake, this question is relevant to investors today not only because of the magnitude but also because of the breadth of recent market declines.
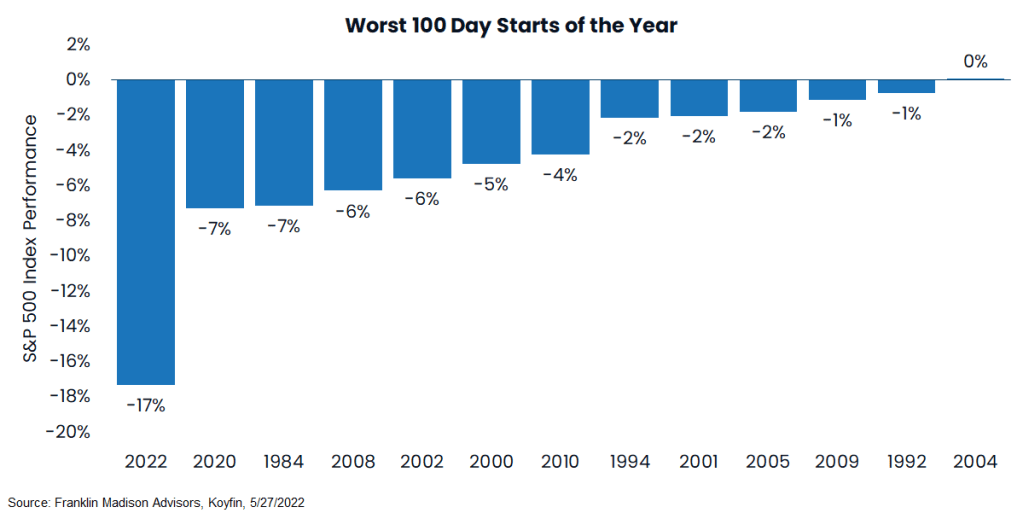
For example, if we consider year-to-date performance for the S&P 500 index, what we find is that the first one hundred days of this year's market performance have been brutal. Indeed, through the end of May, the data show that U.S. Large Cap stocks have had their worst year-to-date decline in the past forty years. Adding insult to injury, investors have had little place to hide given the fact that stocks and bonds across U.S. and international asset classes have all posted losses this year.
So, why are markets selling off across the board? Well, the reasons behind this seemingly correlated selloff across major asset classes are manifold. But at its core, persistently high inflation and the prospects for an impending U.S. recession given ongoing logistics issues, healthcare concerns, and the war in Eastern Europe have made market participants more sensitive to the effects of less favorable central bank policy and the weaker corporate earnings outlook.
Now, in the past, market participants could look to policymakers to bolster the economy and markets when similar weak or uncertain macroeconomic conditions were present as they did back in 2020. But today, that story has changed. With headline inflation well above 8% this year, Federal Reserve policymakers are keen to continue raising interest rates, even if that means forcing the U.S. economy into a recession.
At the same time, businesses likely will find it increasingly challenging to keep passing along rising prices to consumers as wage growth has failed to keep up with inflation and household pocketbooks become increasingly stretched.
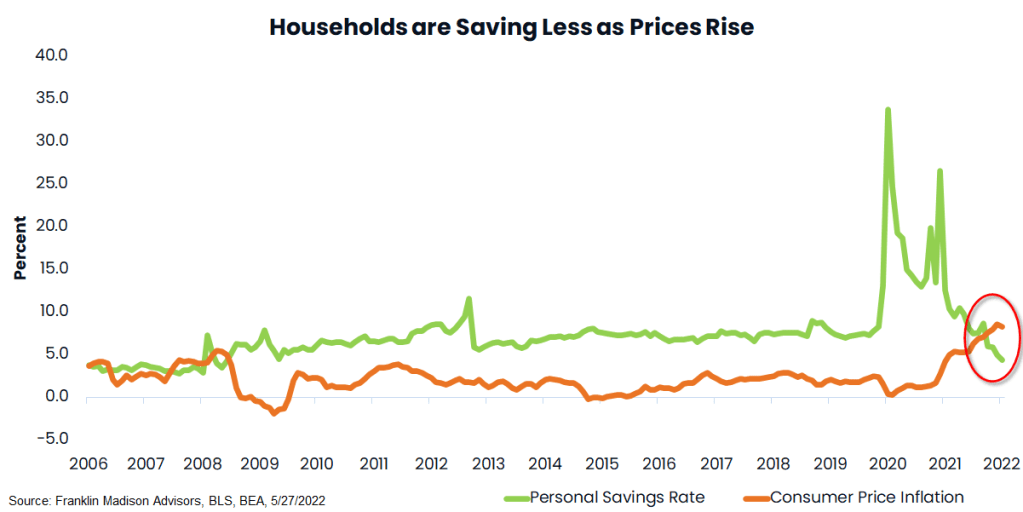
With the economic backdrop poised to weaken, and asset prices declining across the board, is now the right time to get into the markets? Well, with market sentiment being driven by the macro narrative, it can be argued that current economic conditions depend on many factors for which we yet have little clarity. For example, can the world avoid massive food shortages this year and next with a war raging in Ukraine? And, has inflation peaked, and if so, when will it stabilize enough for the Fed to stop pushing borrowing costs higher and higher?
While the answers to these questions are debatable, what is clear is that market participants have a host of broad-based macroeconomic concerns that still need to be worked out. And from this perspective, the prospect of continued volatility across asset classes suggests that timing market entry points (whether that's buying at a discount or avoiding the markets altogether) may be challenging for even the most seasoned investors.
Therefore, in the current environment, we believe that the question investors should be most concerned about is not how to time the markets but rather whether they have an investment process in place to withstand this period of heightened market uncertainty.
Missing the best days in the markets
Indeed, some investors may be enticed to use timing techniques or other short-term strategies in a bid to boost overall returns or to avoid losses completely. Such approaches involve exiting risk assets in anticipation of market moves lower and ratcheting risk back up as market sentiment improves. While such an approach sounds reasonable, getting the timing wrong could be more costly than beneficial.
How so?
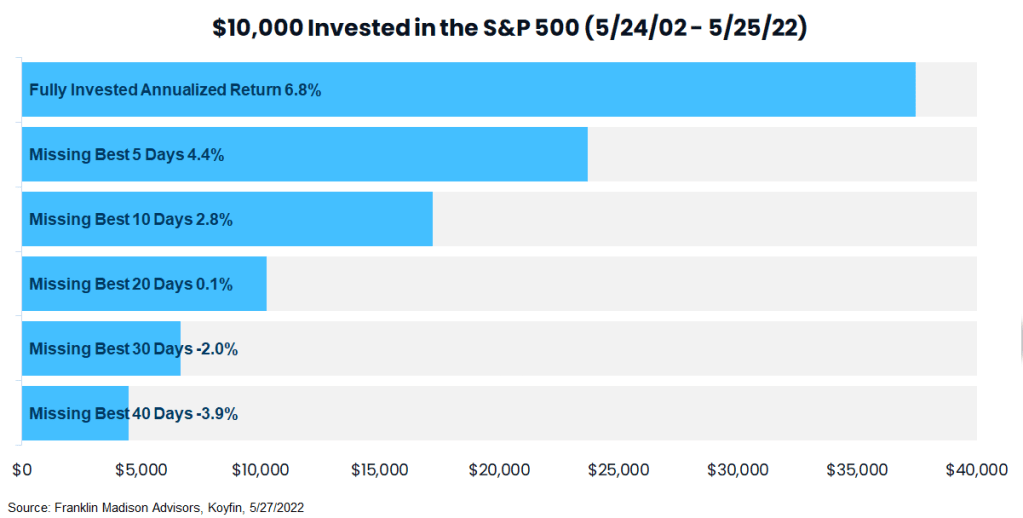
Well, one analysis shows that over a 20-year period, missing even the 10-best days in the market would have led to returns of more than half the rate of those made by investors who stayed committed to the markets during up and down periods.
How is this possible?
Well, history shows that some of the best days in the markets typically follow the worst selloffs. This insight means that investors who had taken money out of the market in fear of a move lower could miss the beginning of a long-term rally. This reality was evident as recently as the COVID-induced market pullback in early 2020 and the subsequent risk asset rally through the end of 2021.
So, what's the point?
Well, unless you have the time, inclination, and experience, getting the timing right on a trade in your portfolio because you're debating whether you should (or shouldn't) get into the markets may cost you more than it is ultimately worth over the long run.
Finding the winning trade
This timing discussion also raises the question about trying to spot winning and losing trades. This attempt to time the market is especially tempting when yesterday's winners are beaten down and appear to be deep value opportunities or a bargain-buy.
Another temptation during the market selloff is chasing what appear to be winning asset classes and avoiding those asset classes that appear to be losing trades. The problem with trying to separate winners from losers, notably during a time of heightened market volatility, is that investor sentiment can shift on a dime, leaving many a portfolio in disarray.
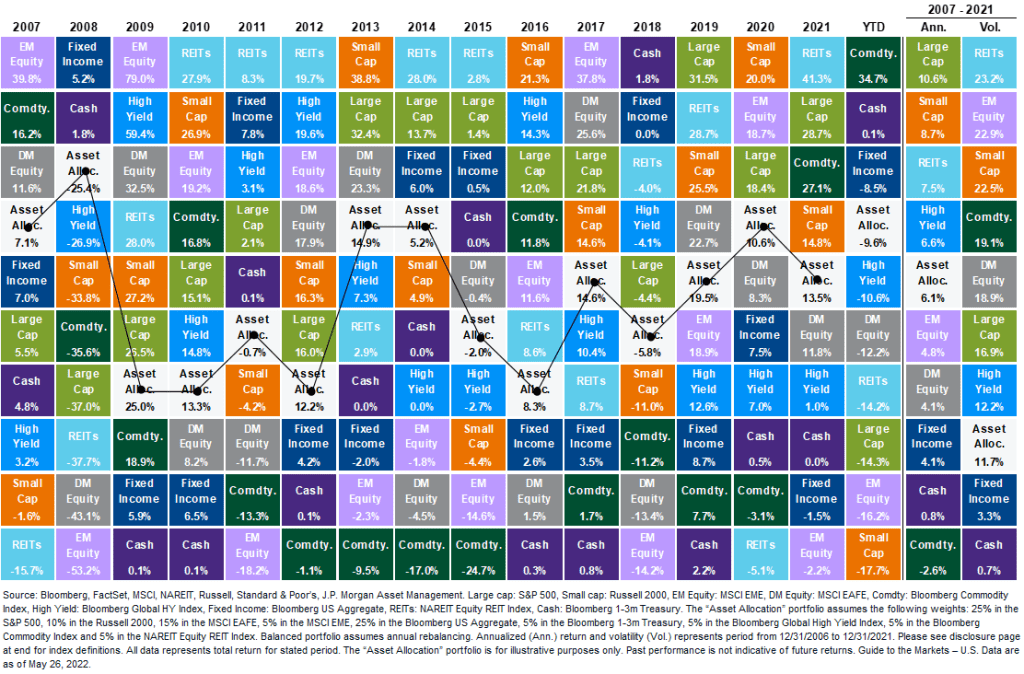
Indeed, some data show that today's best-performing asset class could be tomorrow's laggard and vice versa.
What's more, the variability between stocks and bonds and even domiciles like the U.S. versus international investments tend to vary in performance from one year to the next. That's why an investment portfolio utilizing a diversified asset allocation framework and rebalanced at regular intervals tends to perform more consistently and avoids the wide swings associated with staking a claim in any one asset class. This finding leads us to our final point: a systematic investment process can add more value over time than trying to time the markets.
A systematic process for navigating market uncertainty
To be sure, even some of the best asset managers have had a hard time beating the markets over the past decade, which underscores the importance of a solid investment process. What do we mean by investment process? Simply put, we suggest 1) choosing the right mix of assets for a portfolio that aligns with an investor's risk tolerances and objectives, 2) putting money to work in the markets in a disciplined manner, 3) rebalancing portfolios at regular intervals, and 4) finally having a cash management process in place.
Diversify your portfolio
Now, a systematic investment process begins with understanding your own tolerance for risk and adding a set of assets to an investment portfolio that that vary with your overall goals and objectives. What does this look like? Well, for investors with a low tolerance for market swings and a near-term need for access to their assets, a conservative allocation would likely reflect a bias toward more bonds and less stocks.
On the other hand, a more aggressive asset allocation framework could be appropriate for investors who can tolerate wide swings in the markets and have a longer investment horizon. Either way, a solid investment process begins with understanding your preference for risk and your overall investment horizon.
Dollar-cost averaging
The next part of the systematic investment process involves being disciplined with committing capital to an investment portfolio at regular intervals. As we pointed out earlier, trying to time the best and worst days of the markets might have an adverse effect on overall investment performance. To avoid such issues, we recommend dollar cost averaging, or more simply, committing a set sum of money to your investment portfolio on a regular basis.
What does this look like?
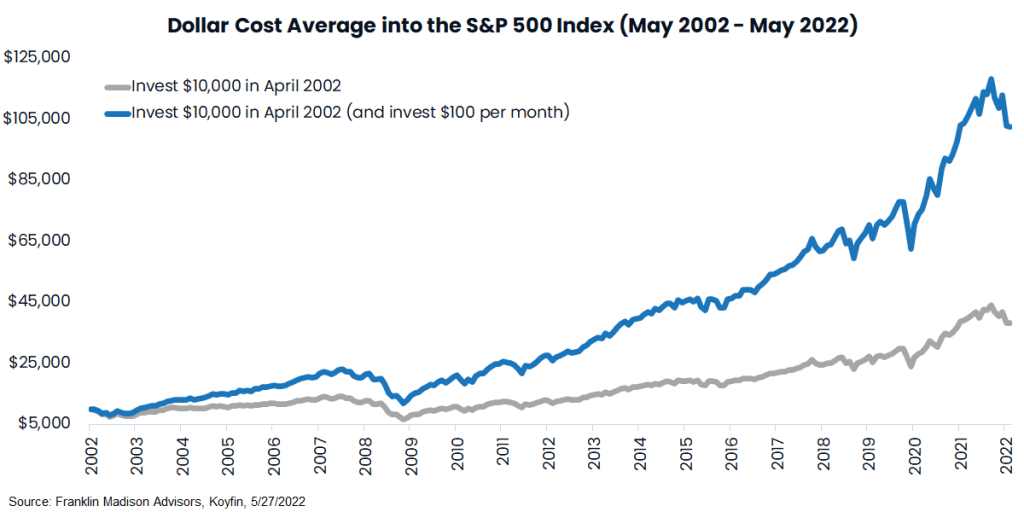
If you participate in an employer-sponsored retirement plan, this could involve setting up automatic payroll deductions and having capital committed to your portfolio every pay period regardless of market conditions. Or, a similar approach can be used for after-tax contributions or lump-sum transfers by scheduling cash allocations to your IRA or taxable investment account on a pre-defined schedule. Either way, putting capital to work at set intervals can help reduce cognitive load, simplify decision-making during periods of market volatility and keep your savings goals on track.
Rebalance your portfolio
Another step in the systematic investment process is portfolio rebalancing. Now, rebalancing is essential because, over time, the values of various assets within a portfolio will drift away from their initial allocations as markets move up and down. The purpose, then, of rebalancing is to realign portfolio holdings with their target allocations.
So, when should you rebalance?
Rebalancing can occur 1) on a set schedule, 2) when asset values drift by a certain threshold, or 3) in a combination of the two. For example, rebalancing on a set schedule could involve evaluating portfolio holdings quarterly, partially selling positions that have appreciated, and adding to allocations that have underperformed during that period.
Alternatively, using a threshold to rebalance could involve using a decision rule that prompts a rebalance only when the value of a specific asset class is a set percentage above or below its target allocation. This process could lead to less frequent rebalancing during flat markets but more rebalancing during periods of heightened market volatility.
Cash Management
Finally, if you're in the distribution phase of your investment journey, or in other words, dependent on your savings to pay for your living expenses, then cash management is essential for navigating market volatility without missing out on the best days in the market.
Now, a solid cash management technique ensures that you have access to enough liquid assets in your retirement portfolio to cover between 12-18 months of living expenses. Such investments can include money market mutual funds, and the purpose of this approach is to give your savings enough of a runway to avoid having to sell assets at an inopportune time when the markets begin to sell-off.
Bottom line
When it comes down to it, asking whether now is the time to get into the markets often misses the point of what it means to be a long-term investor. To be sure, trying to time the markets and hoping to find the next "fat pitch" or winning trade are demeanors often associated with speculative behavior. And, as we have pointed out earlier, such behavior can lead to unfavorable investment outcomes over the long term.
That's why during times like the present, we challenge investors to ask themselves whether the decisions they are making are aligned with a systematic investment process. This approach includes committing to a target asset allocation framework, deploying capital to the markets in a disciplined manner, rebalancing as appropriate, and having a solid cash management process in place.
Whether you're looking to buy securities at a discount or avoid losses altogether, there's rarely a right time to get into the markets. Nevertheless, we believe that staying committed to a disciplined investment process and using techniques to manage uncertainty during periods of heightened market volatility could help you increase the odds of achieving your lifestyle goals regardless of market conditions and keep you on track to mastering your financial independence journey.


Is it Possible: Two Recessions in Two Years?
Two recessions in two years. Is it possible? Well, calls for a U.S. recession have been on the rise recently following the Fed's decision to raise rates at its March FOMC meeting. To be sure, given several factors already in play, it's possible that we could see an economic slowdown later this year or even early next year.

While some market watchers have suggested that policymakers could simply stop raising rates if a downturn emerges, the reality is that the Fed's credibility and its playbook are considerably changed from where it was two years ago.
Make no mistake, at this moment, the U.S. economy is doing well. And recent data suggest that growth has been on a solid footing since the COVID-related lockdowns eased last year. Nevertheless, various developments related to monetary policy uncertainty and rising geopolitical tensions suggest that the road to U.S. economic growth likely will face some headwinds in the year ahead.
Indeed, the bond market, typically a canary in the coal mine when it comes to the health of the economy, is now indicative of heightened financial and economic stress as escalating war tensions and rising interest rates have led to yield curve flattening. And too much flattening could be an early indicator of an impending recession.
This outlook has led some investors to ask whether there is anything they should be doing now to avoid downside risks related to a market or economic downturn. The truth is that many investors have been caught flat-footed by trying to time the markets during similar periods of uncertainty.
And that's why during times like these, it’s essential for driven individuals on their path to financial independence mastery to focus on an approach that has worked time and time again: consistently executing on a well-defined financial plan.

Still Solid Economic Growth?
So, how strong is the U.S. economy right now? Well, if you were to look at some recent reports, the data suggest that U.S. economic growth has been robust over the past year. Indeed, government data showed that the U.S. economy grew seven percent on an inflation-adjusted basis in the fourth quarter of 2021. This gain is much faster than the average growth rate between the Great Recession and the pandemic, likely reflecting the positive effects of easy monetary and fiscal policies.
What's more is that recent data shows that the U.S. labor market, another important indicator of economic health, continues to improve significantly. For example, recent initial jobless claims have declined to their lowest level since the pandemic began, and according to some reports, there are more job openings today than there are unemployed workers. So, what does this all mean?
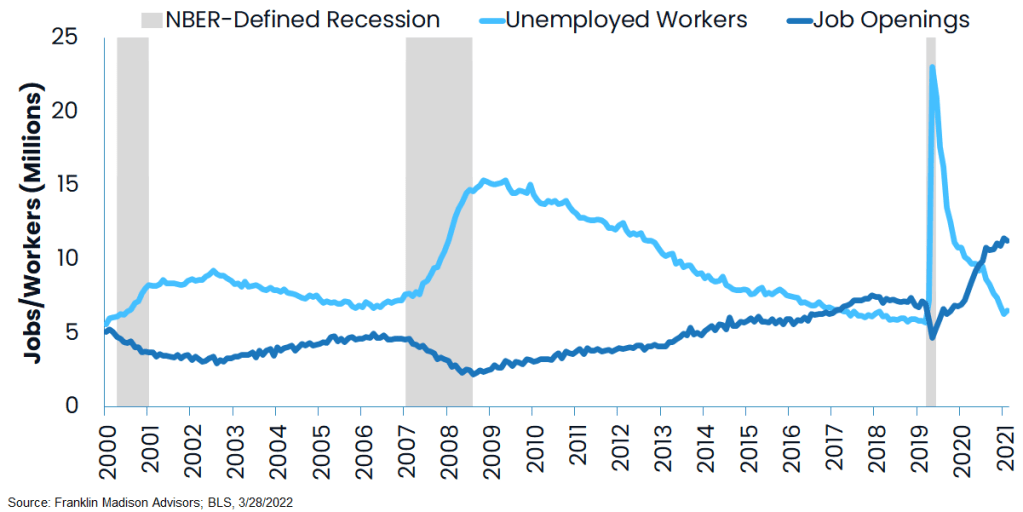
Well, by looking at a solid growth print in the fourth quarter and continued robust labor market data, one could conclude that, at present, growth momentum remains positive. Now, while it's true that labor market shortages and falling unemployment rates are signs of robust economic conditions, what truly drives growth in this environment is business and consumer spending which are poised to decline later this year.

Slowing Growth and Rising Inflation
How can spending decline when labor market conditions have improved? Simply put, households today are likely to face twin headwinds of higher borrowing costs as the Fed raises rates, commodity shortages and ongoing supply chain issues related to Russia's war with Ukraine drive inflation higher. It's important to recall that back in 2020, policymakers unleashed unprecedented amounts of cash into the financial system as the U.S. economy stared into the abyss of Covid-related lockdowns. Back then, trillions of dollars worth of stimulus payments allowed many businesses and households to remain solvent while the U.S. economy effectively shut down.
With COVID lockdowns easing, and individuals returning to their usual spending routines, household consumption has been robust over the past year. Even so, real disposable personal income, which measures how much households have left at the end of the month after paying their obligations, has fallen to its lowest level in nearly two years as the effects of inflation has bid up the prices of goods and services.
Rising inflation has also negatively affected household confidence, falling to its lowest reading in over a decade as measured by the University of Michigan's consumer sentiment index. Indeed, the same survey shows that individuals anticipate inflation to remain above 4.9% over the next twelve months, which is its highest reading since the height of the Great Recession in 2008.

It's important to note that these weaker data points were published before Russia invaded Ukraine. Today's high inflation arguably is tied to legacy supply chain issues coupled with too much money chasing too few goods as a result of pandemic-era stimulus measures. While Covid ground global supply chains to a halt, Russia's war with Ukraine coupled with Western sanctions are likely to exacerbate an already challenging inflationary environment for which we're only beginning to see the early signs.
For example, in some parts of the country today, gasoline prices are at historic highs. According to AAA data, diesel prices were as high as $5.25 per gallon in mid-March, besting the Great Recession peak price of $4.76 in July of 2008 and a pandemic low of $2.37. Add to this the parabolic rise of fertilizer, wheat, industrial metals, and other commodity prices, and the inflation picture could become more challenging in the months ahead. And this matters because households tend to consume less when prices move higher, especially when borrowing costs rise due to the Fed's anticipated tighter policies.
Second Recession Worse than the First
Looking ahead, recent positive economic developments could give way to disappointment in the coming months. Even though a tight labor market has led to higher wages, they're not rising fast enough to compensate households for higher food, housing, or transportation-related costs. At the same time, it's becoming increasingly clear that the U.S. response to Russian aggression is not something that will be resolved in just a few weeks. Indeed, following his meeting with NATO members last week, President Joe Biden indicated that the U.S. and its allies are preparing for a long, drawn-out confrontation with Russia (and potentially China) that could lead to a prolonged high-inflation environment.
So, that leaves us with monetary policy. And one question on some people's minds is will the Fed cut rates as they did in 2020 if the economy begins to slow? While it would be comforting to believe that the Fed could hold back on raising rates if growth slows, the truth is that policymakers likely will continue raising interest rates so long as inflation remains stubbornly high.
Long story short, the Fed made a bad call on inflation in 2020 and waited too long to raise interest rates, so its credibility has suffered. Now, with inflation in the U.S. increasing to 7.9% in February and cruising over five percent for the past nine months, Fed policymakers are playing catchup when supply-side pressures are poised to make their jobs more difficult.
Indeed, during its March meeting, the FOMC raised the Fed Funds rate for the first time since 2018 by one-quarter of a percent, to a rate of one-half of one percent. While this appears to be a small move, the economy is already feeling its effect, with average 30-year mortgage rates now approaching five percent.
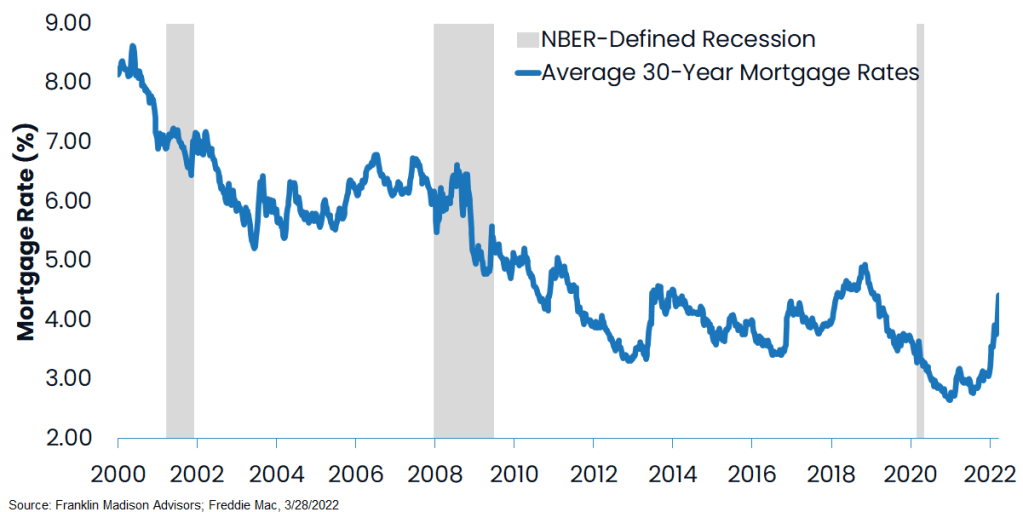
What's more, according to the Fed's economic projections, policy rates are likely headed above two percent this year and above three percent in 2023. At this pace, it's very well possible that we've seen the end of zero-percent auto loans and mortgage rates near three percent.
Simply put, if a recession does materialize, what will make it different from 2020 is that there likely won't be broad-based stimulus to prop up growth this time around. You'll recall that during the pandemic-induced slowdown, politicians were willing to dole out stimulus checks to households and businesses, and the Fed cut interest rates and expanded its balance sheet.
This time around, however, the economic slowdown may not lead to the same kinds of bailouts as we saw a couple of years ago, naturally giving way to increased strain on households, businesses, and the financial markets alike.
The truth is that central bank policymakers have lost credibility in their capacity to manage inflation. Their policies either undershot in the years following the Great Recession or overshot during the pandemic. That's why, from their perspective, one way to make that up for the loss of credibility is to allow the economy to fall into a recession, just as the central bank did back in the 1980s during Paul Volcker's time as Fed Chair.
Positioning your Finances for an Economic Slowdown
Taken together, rising interest rates, higher commodity prices and ongoing supply chain issues likely will lead to slower economic growth in the coming year. And this time around, Uncle Same probably won't be doling out cash like he 2020. That's why you need to be prepared financially should a recession appear for the second time in two years.
So how should you position your finances for a potential slowdown and heightened market volatility in the months ahead? Well, if you're an individual focused on mastering your financial independence journey, the short answer is to stay committed to executing on your long-term financial plan.
During times of economic and market uncertainty, for some of us, there's a tendency for our vision to narrow to the present, tempting us to change the way we handle our finances or investment allocations as a way to mitigate what appears to be an immediate financial threat.
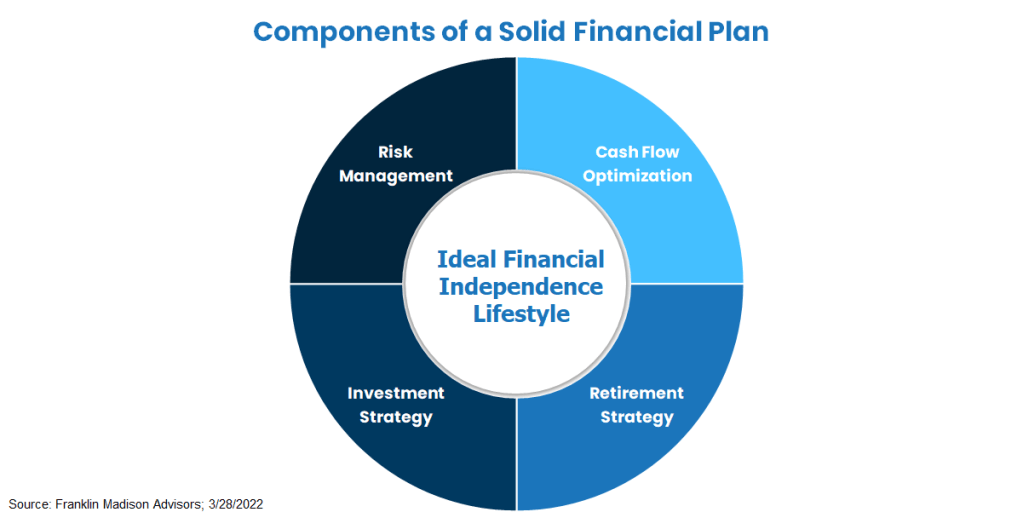
Even so, if you have a well-structured financial plan and a disciplined investment process already in place, then the action that you'll likely need to focus on today is consistently doing the work necessary to execute on your plan. If you have a well-crafted plan, those actions should be defined in your implementation schedule. Otherwise, developing a set of strategies to align your financial resources with your long-term goals should be a priority if you don’t already have a comprehensive financial plan in place.
Indeed, a solid financial plan lays out how to connect the dots between your financial resources and ideal long-term lifestyle goals. At the same time, it identifies predefined strategies and tactics that you can tap into to manage adverse conditions when they inevitably arise in the near-term.
When it comes down to it, various indicators suggest that we’re likely headed for a second recession in two years. And this time around, the government possibly won’t be as accommodating as it has been in the past. That’s why if you're serious about mastering your journey to financial independence, then now's the time to ensure that you have a solid financial plan in place, that your investment strategy is aligned with your long-term plan and that you're effectively executing on your implementation schedule.

Russia Invades Ukraine – What Now?
Russian President Vladimir Putin made good on his promise to invade Ukraine on Thursday. As a result, the S&P 500 Index sold off sharply before bouncing back into the close. Front-month crude oil futures also climbed above $100 per barrel intraday for the first time since 2014 before giving back gains. Market tensions indeed settled after President Biden’s press conference concluded on Thursday, but, on a year-to-date basis, US equities, on the whole, remain near bear market territory.
A New Set of Risks
There’s little doubt that market participants have had a lot to contend with over the past few weeks. More recently, it was the uncertainty surrounding central bank policy and whether the FOMC would aggressively raise rates in March to help stem the tide of higher inflation. Now, investors not only have to make sense of what a Russian invasion in Eastern Europe might mean for corporate earnings but whether military conflict escalates to the point of sparking a world war, as some US politicians have suggested.
Make no mistake, there are many reasons to be concerned about Russia’s assault on Ukraine. For starters, this move has arguably rewritten Russia’s relationship with the West after 30 years of peace following the collapse of the Soviet Union. Certainly, some might suggest that this relationship changed when Russia invaded and took control of Crimea in 2014.
Even so, as President Biden pointed out in today’s press conference, Putin’s ambitions to restore the Soviet Union could lead to further military escalations beyond Ukraine’s borders. Indeed, a Russian confrontation with NATO-allied countries in Eastern Europe could escalate tensions along other territorial fault lines, leading to a broader global conflict.
Potential Conflict Beyond Ukraine
That’s why it’s essential to understand that the events unfolding in Ukraine are just one of many other territorial disputes across the world today. And the most significant source of these disputes is China. Indeed, after dismantling democracy and securing its hold of Hong Kong, China is arguably looking for an opportunity to finally take back control of Taiwan (a country staunchly allied with the US), potentially by force. India has also seen its fair share of confrontations with China as military tensions have centered on the Kashmir border for years.
In Southeast Asia, North Korea, whose economy is mainly dependent on China, continues to agitate its neighbors with threats of military strikes even as its population starves. And more broadly, China has a score to settle with several countries regarding its nine-dash line claims to the South China Sea. Add in political instability and various proxy wars in the Middle East and Central Asia, and you could have the recipe for a broad-based global conflict.
Are We Headed for World War III?
So, is this the start of World War III? Well, we hope that cooler heads prevail in the coming days and weeks, notably following the imposition of significant financial and economic sanctions placed by G7 leadership on the Russian economy. Either way, China likely will be directionally key to broader global tensions. To be sure, Beijing appears to be walking a fine line between appeasing the Kremlin while maintaining decorum with the West, potentially forestalling a broader global conflict. Even so, in the coming weeks these sanctions likely could have a notable impact on the global markets and economy even without a hot war. How is this possible?
Well, long story short, global energy prices are likely to rise as sanctions hit a vital producer of the world’s fossil fuels. Additionally, restrictions on US technology exports to Russia could inadvertently spark a policy tit-for-tat with China and complicate an already strained global supply chain. Indeed, much of inflation’s rise over the past year has been attributed to global supply chain issues resulting from Covid-related economic lockdowns.
Amidst this geopolitical uncertainty, one silver lining seems to have surfaced. And that’s the fact that it could be more problematic for central bank policymakers to raise rates aggressively without potentially pushing the economy into a recession with the threat of war looming. Indeed, this realization among some market participants arguably led to a significant risk asset rally into the market close on Thursday.
What’s the End Game?
So, how will this all end? Well, we don’t have a crystal ball and can’t say with certainty how today’s events will unfold in the weeks and months ahead. Nevertheless, what we do know is that similar geopolitical events have come and gone over the past century, yet global democracy has only become stronger as a result while risk asset prices continue to gain decade over decade.
Now, it goes without saying that Russia’s decision to invade Ukraine could have significant global economic and market implications. So, from this perspective, what should individuals concerned about the prospects of military escalation do to best position their finances during this time of uncertainty?
Well, given the tenuous geopolitical and global economic backdrop, we believe that individuals on the path to mastering their financial independence journey should take a few steps to frame these uncertainties within the context of their portfolios and, more importantly, their broader financial plans.
Dealing with Market Uncertainty
To start, turn off the news and take the time to remind yourself of your long-term financial goals. During times of crises, we often find ourselves consumed with ever-changing news flow and yearning to take some form of action.
Oftentimes, however, the best course of action during times like these is to stay committed to the priorities you’ve set out to achieve for the future. Don’t get distracted by the near-term noise. Indeed, your long-term financial plan and disciplined investment strategy was created to help you navigate times just like these.
Next, try to avoid timing the market where possible. Even after reviewing your financial plan, you may be tempted to make near-term investment decisions in your portfolio that may have adverse consequences over the long term.
For example, if you had sold into the market open on news of Ukraine’s invasion, you likely would have missed the strong rally into the market close. During these times of uncertainty, many investors are best served by managing risk in their portfolio rather than by trying to divine market moves hour-by-hour or day-by-day.
And that brings us to our last and final point: manage investment risk. To manage risk in your portfolio you’ll likely want to focus on two things you can control: 1) having adequate cash on hand and 2) ensuring that your portfolio is properly aligned with your long-term goals. To the first point, consider having enough cash on hand to cover living expenses or other expenditures over the next 9-12 months. Doing so could prevent you from selling securities from your portfolio at an inopportune should market volatility linger for longer.
Second, now may be the time to ensure that your portfolio has an ideal mix of stocks and bonds aligned with your strategic asset allocation framework. Periodically rebalancing your investment can help ensure that you’re taking the ideal amount of risk in your portfolio, given your current stage in life.
At the same time, you may want to ensure that your portfolio holdings reflect a basket of stocks with solid earnings potential while holding higher-quality credit in your bond holdings.
Only time will tell whether the current situation will escalate to a broader conflict or settle more amicably. We hope that substantial financial and economic sanctions coupled with a solid political resolve from Western leaders will convince Putin to end his military incursion in Ukraine. Until then, we anticipate market volatility to ebb and flow with the news cycle. For now, avoiding the noise and committing to your long-term financial plan will not only give you peace of mind during this time of uncertainly, it likely will also enable you to continue your journey toward financial independence mastery.

Don't Call it a Crash (Yet)
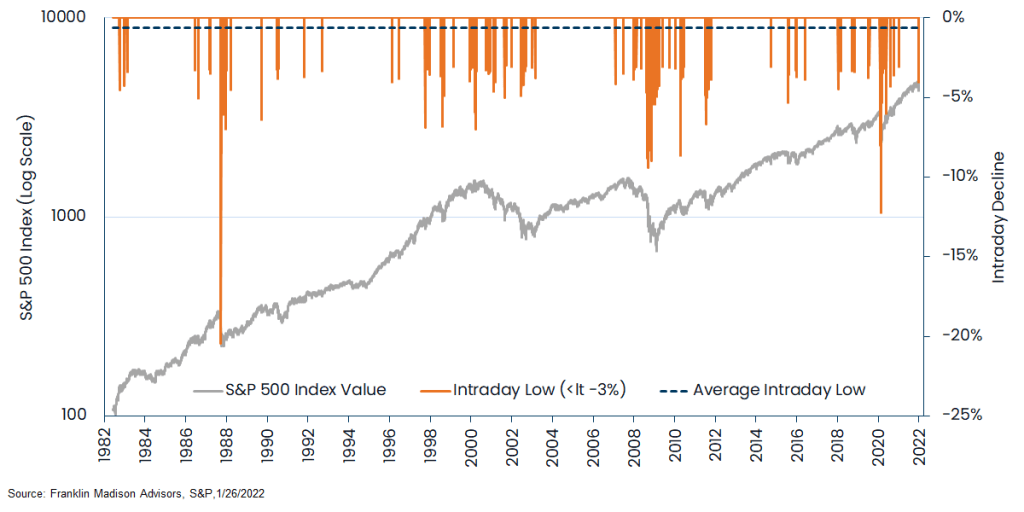
The S&P 500 index fell nearly four percent intraday on Monday, January 24, making for one of its most volatile trading sessions since September 2020. Heading into this period of instability, investors had good reason to believe that the markets were heading for a collapse. Rising inflation, concerns about the Omicron variant, the potential for war with Russia, and a Fed poised to aggressively raise interest rates amidst a clouded U.S. and global economic outlook had seemingly overshadowed any positive catalysts for an upward market move.
S&P 500 Index Intraday Declines Greater than 3%
With so much uncertainty on the rise, and policymakers poised to drain liquidity from the financial markets, a key question for many investors is whether we are on the precipice of a prolonged market selloff. Certainly, some market watchers and prognosticators are making the rounds on financial media and arguing that this week's volatility is setting the stage for lower equity prices ahead.
Anecdotes aside, historical data indeed suggests that a period of market weakness in risk assets is likely on the horizon after this week's moves. That said, however, there's still a case to be made for avoiding panic and remaining committed to a long-term investment strategy amidst solid economic and corporate fundamentals. Indeed, it's during these times of increased market uncertainty that financial independence masters like yourself preserve their wealth by adhering to their disciplined asset accumulation and retirement distribution strategies.
Intraday Decline and Future Market Performance
So, what should we make about Monday's market decline? Well, one way to interpret the selloff is to view the market move in a historical context. To do this, we looked at S&P 500 index data going back to 1982 first to understand the frequency and significance of sharp intraday pullbacks. Second, we evaluated how stocks have performed in the periods following a significant one-day selloff.
What did the data show?
Well, to the first point, history shows that days where the markets declined by at least 3% intraday, like the one we saw this week, have occurred in less than two hundred of the ten thousand trading days over the past forty years, or 2% in total. In fact, the data show that, on average, stocks tended to decline less than one percent in intraday trading over this period. Moreover, our analysis suggests that these sorts of pullbacks are prevalent heading into periods of price weakness, more so when market narratives change.
So, now that we know that what happened this week wasn't just another run of the mill market slump, what does history tell us about how stocks have performed in the weeks and months following such a selloff? Historically speaking, the data suggests that markets more often than not continued sliding an average 8% in the month following a sharp one-day selloff.

And how have stocks performed after three months following a selloff greater than 3%? Well, from this expanded timeline, the data fares somewhat better, with markets down only about a third of the time. And finally, if we look out over a one-year horizon the data suggest that equity prices are down about a quarter of the time over the past four decades. Taken together, one way to interpret Monday's selloff from a historical context is that volatility likely could remain elevated in the near term, with market conditions improving over the long term.
Is it a Crash or Market Correction?
While there's certainly precedent for continued market weakness in the weeks ahead, a key question for some investors is whether we're heading for a market correction or a market crash. First, it's important to clarify that a crash is much different from a correction. A market crash can be characterized as a sudden, steep decline occurring over a matter of days. For example, you'll likely recall that in February 2020, the S&P 500 index declined over 10% in less than a week amidst Covid concerns before dropping the following month precipitously.
On the other hand, Corrections generally extend over weeks and are relatively common. So common, in fact, that corrections have occurred 18 times over the past decade. So, what does all this mean? Well, as we pointed out earlier, while a sharp intraday pullback has been historically consistent with near-term risk asset declines, several catalysts like expectations for positive economic growth and rising corporate earnings this year likely remain supportive of equity prices.
S&P 500 Index Analyst Earnings Estimates

Solid Fundamentals as Tailwinds Fade
Indeed, compared to the outlook driving the market crash of 2020, economic fundamentals today are softening yet remain generally on firmer footing. For example, the government this week reported that U.S. economic growth bested expectations in the fourth quarter and that the economy expanded at its fastest clip in nearly four decades on an inflation-adjusted basis. Data also show that personal income and household balance sheets remain solid as the unemployment rate declines and employers offer higher wages to their workers.
From a business sentiment perspective, the Richmond Fed's latest survey of CFOs shows that optimism among business leaders remained buoyant in the fourth quarter of 2021. Indeed, aside from cost pressures and supply chain issues (which we'll discuss in a moment), positive hiring intentions remain a key indicator of forward-looking business health.
On the earnings front, analysts expect corporate earnings growth to slow compared to last year's post-pandemic rise, but generally are anticipated to remain positive in 2022. This data is vital because heading into the market crash of 2020, corporate CEOs slashed forward guidance, and earnings declined amidst policy-induced economic lockdown measures.
US Average Hourly Earnings

Self-Inflicted Wound
While backward-looking data suggests that the U.S. economy has been on solid footing, forward-looking indicators point to both economic and market headwinds in the months ahead. Top of mind for households, businesses, policymakers and market participants alike is the persistence of stubbornly high inflation. This concern is evidenced in headline inflation coming in at 7.1% in December, its sharpest rise in forty years. At the same time, the core PCE index (the Fed's preferred measure of inflation) came in at 4.9% in December, compared to a pre-pandemic average of 1.6%.
This inflation rise has also been evident in record-high home and auto prices as well as the rising cost of food and gasoline, which understandably has households worrying. Indeed, data out on Friday from the University of Michigan showed that consumer sentiment is at among its lowest level since the start of the pandemic, with survey respondents reporting five-year inflation expectations at their highest level in a decade. At the same time, business surveys indicate that rising input costs are among the top concerns for business leaders.
To address seemingly out of control price increases, Federal Reserve policymakers have announced measures to quickly raise interest rates and have scaled back asset purchases. And it's this aggressive policy response that has caught market participants on the back foot and contributed to recent bouts of market volatility. As it stands, the Fed is ready to raise rates four times this year (likely beginning in March), with some analysts predicting as many as seven hikes this year.
While monetary policy can be used as a tool to slow rising prices, a slowdown in the economy (or even worse, a recession) could result as a self-inflicted wound via Fed policy in 2022, which has some market participants on edge. The reason being is that today's spiraling inflation is in many ways driven by logistics issues over which the Fed has little control.
To be sure, at a macro level, global supply chain issues have contributed to the rising prices of everything from clothing to autos. At a local level, a report from the American Trucking Association suggests that the U.S. is experiencing a shortage of around 80,000 drivers due to illness, retirement, or simply a lack of interest. This shortage of freight delivery drivers and the rising cost of transportation is putting upward pressure on the price of goods on store shelves – something the Fed can’t control.
Freight Costs Growing Fastest in Decades

Don't Call it a Crash (Yet)
While there's a reason for concern among some market participants, it may yet be too soon to call recent market moves the beginning of an outright crash. Indeed, compared to the events of the market crash in 2020, both fiscal and monetary policymakers have greater leeway on addressing impediments to economic growth, which can affect market sentiment.
Nevertheless, with forward-looking indicators pointing to signs of slowing economic growth, market participants need some clarity that aggressive Fed policy won't choke off economic growth and, hence, corporate earnings. Simply put, how the Fed threads the needle of policy tightening while preserving economic growth will determine whether the markets can claw back gains or succumb to a prolonged bear market selloff. This is one reason why incoming forward-looking economic data will be crucial to market sentiment in the coming weeks, confirming whether or not the economy can handle higher rates.
So what's an investor to do during these times of changing market narratives and policy uncertainty?
Whether you're still saving up for your early retirement goals or have already become financially independent, now is the time to carefully consider your investing, savings, and spending strategies for the coming year.
Saving for Financial Independence
If you're still in the accumulation phase of your financial independence journey, now's likely an excellent time to take a second look at how much you'll need to have saved to cover your post-employment lifestyle expenses in the future.
While it's likely that the inflation rate could slow in the months ahead, the truth is that prices of goods and services will potentially remain elevated for years to come. Indeed, the rapid rise in home, auto, and other consumer goods has reset long-term baseline spending needs for some individuals.
From this perspective, your role as an asset accumulator will be to ensure that the baseline financial independence savings goal you've defined for yourself five, ten, or twenty years down the road are consistent with the reality of higher prices today. From there, you'll need to determine if and to what degree your savings needs to increase today to meet your new financial independence number.
Additionally, during these times of uncertainty, you'll likely want to avoid the temptation to shift your investment strategy when markets become volatile.
Unless you have a near-term need to drawdown investment savings, changing your asset allocation, like going to all cash, could be detrimental to your long-term savings plan. Indeed, as we pointed out in a prior report, missing even the ten best days in the market could leave your long-term financial plan falling short.
Missing the Best Days in the Markets

Preserving Your Financial Independence
If you're already financially independent and living off of your savings, being prepared for a bout of market volatility while accounting for higher prices in the years ahead likely will be essential to preserving your wealth. No one has a crystal ball to tell them where the economy or markets are headed. That's why during times of uncertainty, your investment process is vital to ensuring long-term financial success. To this end, we suggest that you take a multi-pronged approach to ensure that your assets are well-positioned to provide savings longevity.
First, as with the accumulators, take the time to reevaluate your long-term income distribution need when factoring in higher levels of inflation and market volatility using Monte Carlo simulations. After completing this analysis, you may find that your financial wealth could fall short of your high-confidence savings projections. If this is the case, now may be the time to adjust your near-term lifestyle spending trends by making minor adjustments to expenses, which can significantly impact your overall savings need.
Second, stay committed to a disciplined investment process. Periods of market uncertainty, like we experienced this week, might tempt you to go to cash in anticipation of a broader market selloff. On the other hand, after reevaluating your savings need, you may be tempted to increase your investment risk exposure to make up for a projected savings shortfall. Either way, when it comes to managing your wealth, focus on what you can control and stay committed to long-term outcomes.
Finally, ensure that you have enough cash on hand in the coming months to navigate periods of market uncertainty. The last thing that you'll want to do is sell portfolio holdings to pay for household expenses when markets are in decline. Selling at inopportune times may lead to disappointment and reduce your likelihood of long-term retirement success, particularly if you're not in a position to add to savings through employment income.
While we may not be headed for a market crash just yet, there's ample fuel for a prolonged market selloff in the weeks ahead. With that said, however, there’s still a case to be made for avoiding panic and remaining committed to a long-term investment strategy amidst solid economic and corporate fundamentals. Indeed, it’s during these times of increased market uncertainty that financial independence masters like yourself preserve their wealth by adhering to their disciplined asset accumulation and retirement distribution strategies.

What to Make of the Black Friday Market Selloff?
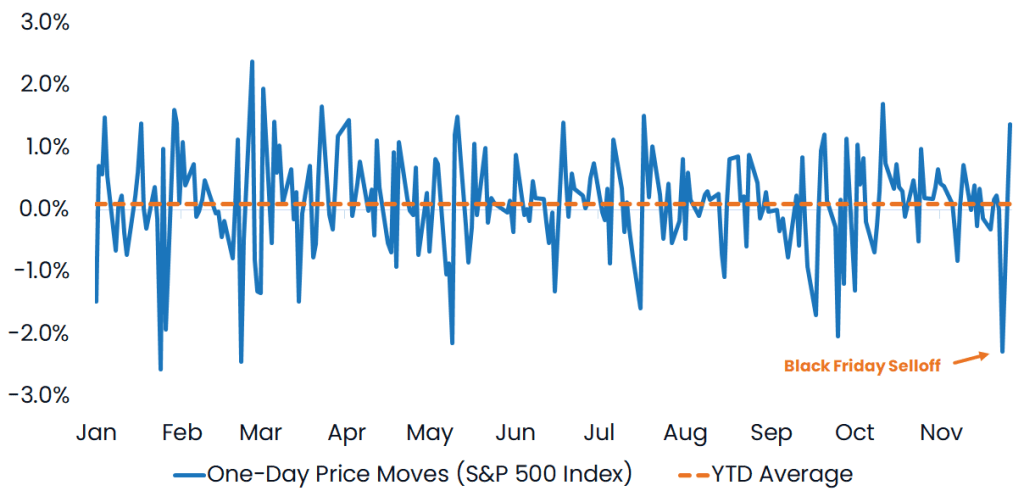
Some investors cut short Thanksgiving festivities last week as financial markets sold off on renewed Covid concerns. The World Health Organization (WHO) declared the latest Covid strain Omicron a “variant of concern”, leading broad market indices to post their sharpest single-day losses in months.
This latest designation from the WHO reflects the fact that the viral strain contains around 50 mutations, 30 more than the main target of many current Covid-19 vaccines, potentially making the virus more transmissible and existing treatments less effective. While the ongoing healthcare situation has created angst in the markets over the past two years, the virus itself is likely not the primary cause of the Black Friday selloff.
To be sure, shortly after the WHO announcement, the US, along with the Canadian, Japanese, and EU governments, announced travel restrictions on Omicron fears. These actions prompted market concerns about renewed economic lockdowns while, at the same time, leading rallies in some stay-at-home stocks even as broader indices posted sharp declines. After a prolonged risk-asset recovery following March 2020 lows, many investors are asking whether this latest viral development will be the catalyst for a long-awaited bear market selloff.
Uneven Policy Transition
Now, many unknowns are surrounding the healthcare and economic implications of the latest viral outbreak. Ever since Covid was discovered in late 2019, the WHO has designated dozens of outbreaks as “variants of concern”. This ever-changing viral landscape has diminished the prospect of a clean break with the pandemic, leading many experts to conclude that the temporary nature of the healthcare crisis likely will shift into a long-term endemic that society will contend with for some time.
While these suggestions seem simple enough, the authors of the reports concede that such an approach would require what they consider a momentous societal shift where every stakeholder plays an important role...
For many individuals, last week’s outbreak announcement likely came as little surprise, and it’s very well possible that society at large is already accepting the inevitability that this disease will be with us for months, if not years to come. While a transition from pandemic to endemic may seem natural at this juncture in the outbreak, the trouble for markets is that policymakers continue to rely on playbooks that focus on halting a pandemic in the near-term, rather than addressing the reality that closing businesses and shutting down the economy could cause more long-term harm than short-term benefits.
A report from McKinsey & Company suggests that in order to adapt to a new reality surrounding the healthcare crisis, policymakers should focus on a four-point approach that 1) defines the new normal, 2) tracks disease progress, 3) limits illnesses and deaths, and 4) slows transmissions. While these suggestions seem simple enough, the authors of the reports concede that such an approach would require what they consider a momentous societal shift where every stakeholder plays an important role, this includes:
- Governments building consensus on goals, communicating superbly, and setting the right incentives
- Employers taking an elevated role, setting policies for their workplace and helping their employees think through the changes
- Health systems striking the right balance among competing demands and planning for the inevitable outbreaks and surges
- Individuals challenging the convictions they’ve developed in the past 18 months and adopting new behaviors
While such an approach seems ideal, the truth is that policy today remains largely reactionary, as evidenced in the latest travel bans. What’s more, the US Administration’s recently introduced vaccine mandates aimed at halting the viral spread likely will only exacerbate the US supply chain issues that have contributed to higher-priced consumer goods and persistently high inflation over the past few months.
What’s more, governments have relied on central banks to buffer the adverse effects of economic shutdowns and restrictions by increasing the availability of capital. Today, however, this approach shows its limits as supply constraints and labor shortages, coupled with easy money policies, contribute to historic inflationary pressures.
A Bumpy Road to Transition
Looking ahead to 2022, we believe that government and central bank policy will remain a key risk to market sentiment. By many measures, Covid is here to stay for the long-term. Even so, the policies employed to “flatten the curve” during the early months of the outbreak are likely not sustainable. To some degree, easy central bank policies and fiscal spending helped offset the economic impact of shutdown measures early in the pandemic.
Even so, central bank policy is now showing the limits of its effectiveness, and the likelihood of additional monetary and fiscal support next year could be limited should US economic growth begin to stall. That’s why we believe that a critical risk to the markets is continued myopic policy response to a long-term healthcare issue as new Covid variants and strains inevitably materialize.
On the other hand, one potential positive market narrative in the coming year likely could be the introduction of policies that reflect the endemic nature of the healthcare crisis, as outlined earlier in this report. Such an approach could introduce pragmatic ways to live with the virus over the long-term and let go of some policies aimed at the failed hope of stopping Covid in its tracks at the cost of economic growth.
Positioning for Policy Uncertainty
So how should you position your finances during this transition from pandemic to endemic? Well, there is little doubt that the ongoing healthcare crisis has challenged many of our financial independence plans for 2021 and beyond. Whether you’re still saving up for your early retirement goals or have already become financially independent, now is the time to carefully consider your savings and spending strategies for the coming year.
Saving for Financial Independence
If you’re still in the accumulation phase of your financial independence journey, now’s likely a good time to take a second look at how much you’ll need to have saved to cover your post-employment lifestyle expenses in the future. The combined effects of healthcare uncertainty and policies to curb viral spreads have put upward pressure on prices this year.
While it’s likely that the inflation rate could slow in the months ahead, the truth is that prices of goods and services will potentially remain elevated for years to come. Indeed, the rapid rise in home, auto, and other consumer goods has reset baseline spending needs for some individuals. From this perspective, your role as an asset accumulator will be to ensure that the baseline financial independence savings goal you’ve defined for yourself five, ten, or twenty years down the road are consistent with the reality of higher prices today. From there, you’ll need to determine if and to what degree your savings needs to increase today to meet your new financial independence number.
Preserving Your Financial Independence
If you’re already financially independent and living off of your savings, being prepared for a bout of market volatility while accounting for higher prices in the years ahead likely will be essential to preserving your wealth. No one has a crystal ball on where things are headed. That’s why during times of uncertainty, your investment process is vital to ensuring long-term financial success. To this end, we suggest that you take a multi-pronged approach to ensure that your assets are well-positioned to provide savings longevity.
The Black Friday selloff is likely to be the first of many market fits and starts in the coming year following a strong market rally.
First, as with the accumulators, take the time to reevaluate your long-term income distribution need when factoring in higher levels of inflation and market volatility using Monte Carlo simulations. After completing this analysis, you may find that your financial wealth could fall short of your high-confidence savings projections. If this is the case, now may be the time to adjust your near-term lifestyle spending trends by making minor adjustments to expenses can have a significant impact on your overall savings need.
Second, stay committed to a disciplined investment process. Periods of market uncertainty, like we experienced last week, might tempt you to go to cash in anticipation of a broader market selloff. On the other hand, after reevaluating your savings need, you may be tempted to increase your investment risk exposure to make up for a projected savings shortfall. Either way, when it comes to managing your wealth, focus on what you can control and stay committed to long-term outcomes.
Finally, ensure that you have enough cash on hand in the coming months to navigate periods of market uncertainty. The last thing that you’ll want to do is sell portfolio holdings to pay for household expenses when markets are in decline. Selling at inopportune times may lead to disappointment and reduce your likelihood of long-term retirement success, particularly if you’re not in a position to add to savings through employment income.
The Black Friday selloff is likely to be the first of many market fits and starts in the coming year following a strong market rally. Make no mistake, inflation certainly is a concern for households, businesses and market participants alike. Nevertheless, as we look into the coming year, we believe a key risk to market sentiment likely will be policy missteps that ignore the evolving nature of a Covid pandemic to long-term endemic. On the other hand, policies aimed at responding quickly to healthcare concerns while eliminating restrictions that reduce commerce friction could be a positive catalyst for market sentiment.
Mid-Year Outlook: Not Out of the Woods Yet
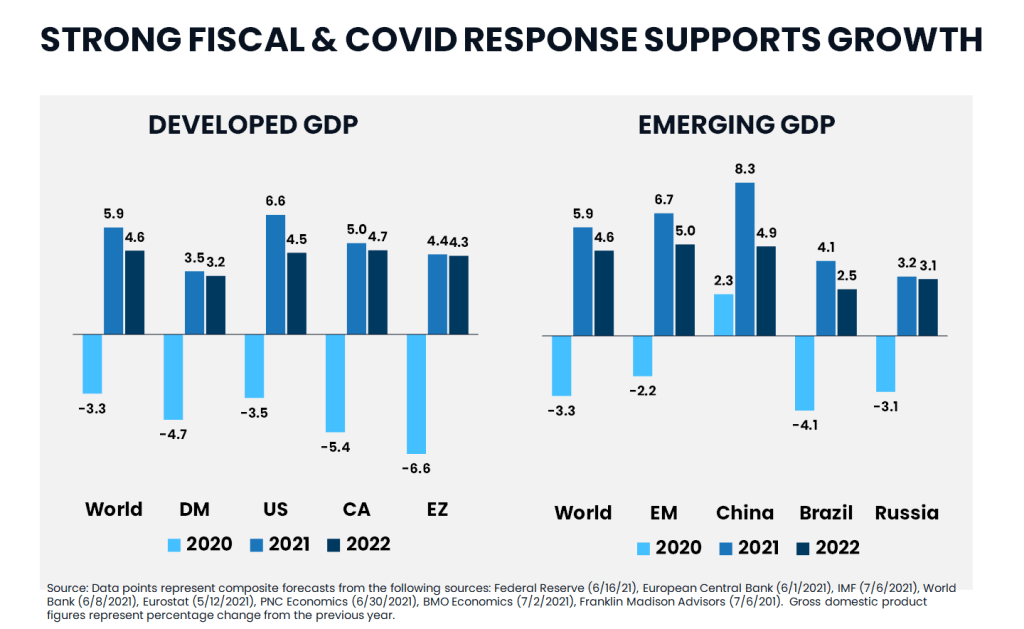
Investors have had good reason to celebrate this year, but is it truly time to let our guards down? Thanks to practical policy guidance, more than half of the US population has received at least one COVID-19 vaccine in 2021. Add to this the boost from a $1.9 trillion fiscal stimulus package introduced in March, and the US economy today is on pace for its most robust recovery in nearly 40 years.
So, how have the financial markets taken these improvements? Well, risk assets have responded to the positive health and economic developments by posting solid gains in the first and second quarters. Looking ahead, however, the market and economic outlook appear less promising. A resurgent COVID variant, accelerating inflation, and a notable lack of bipartisan support for additional fiscal stimulus pose challenges to economic and market momentum in the second half of the year.
Mid-year Review
Now, before discussing likely challenges to the markets and economy in the latter half of the year, let's take a moment to recall how we got here.
Stabilizing Economic Growth
It can be argued that ongoing fiscal and monetary stimulus and easing COVID restrictions led to improving business and consumer sentiment in the first half of 2021. According to government data, the US economy posted a 6.4% gain during the first three months of the year. And by some estimates, the US economic growth is expected to have come in around 8.7% in the second quarter.
For many households, the extra $1,400 per person stimulus checks, coupled with easing social distancing restrictions, likely contributed to this year's spending boom. For example, the latest retail sales data showed that spending at restaurants outpaced pre-COVID levels, rising to a record $67 billion in May.
It's also worth noting that in 2020, approximately 114 million people lost their jobs due to social distancing efforts and the economic downturn. Today, however, labor market conditions are on an upswing. For example, the US unemployment rate as of June was 5.9%, which remains elevated but nevertheless improved from 14.8% last April. Unemployment claims have also fallen back to levels not seen since early 2020 as some businesses have quickly reopened.
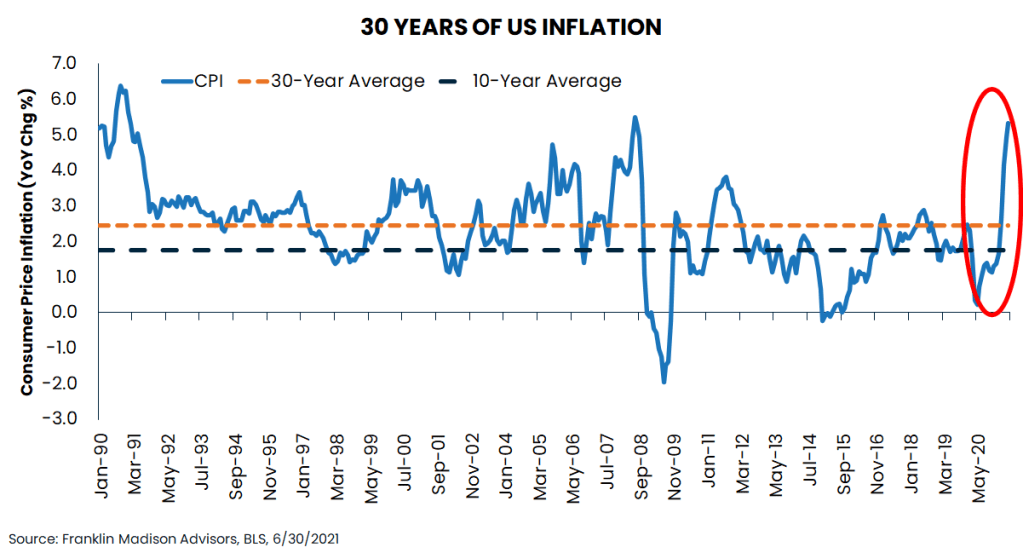
Now, one downside to this year's economic boom has been rising inflation. And as we recently wrote about in last month's report, a key reason for higher inflation today is ongoing supply chain disruptions. To be sure, global logistics bottlenecks have had lingering effects on the price of goods used in end-consumer products and manufacturing inputs alike. Add in trillions of dollars in fiscal and monetary stimulus, and a key concern for markets and households is whether inflation will truly be transitory.
We'll discuss this point about inflation more in a moment. But, for now, we can say with some confidence that the recent economic improvements have underpinned positive investor sentiment even as the nearly 16-month market rally shows signs of exhaustion.
Solid Market Performance
In terms of market performance during the first half of the year, the US remained one of the best-performing markets, led higher by small-cap stocks. For instance, the Russell 2000 Index was up over 17% during the first six months of 2021 as cyclicals rallied in anticipation of the US economic recovery. A 14% gain in the S&P 500 Index followed this positive performance along with a 12% move higher in the tech-heavy Nasdaq 100 Index.
Internationally, emerging markets lost momentum during the first half as COVID concerns in Asia and uncertainties surrounding China weighed on overall performance. Even so, the MSCI Emerging Markets Index posted a solid 6% gain during the first six months of the year. Across the pond in Europe, while economic conditions are anticipated to improve this year, ongoing health concerns have limited equity market gains to around 10%.
And while we're talking about risk assets, we would be remiss, not to mention the recent attention given to "meme stocks" and crypto. These highly speculative investments made a splash last year but have seemingly lost their fizzle recently. After peaking early in the second quarter, prices of these assets have given up much of their gains. And these highly volatile price swings are a crucial reason why we view such assets are speculative in nature.
From a fixed income perspective, the bond markets aren't quite so convinced that the US economy is entirely on solid footing. This point has arguably been seen in rising Treasury prices even as inflationary pressures move higher. For example, the yield on US 10-Year Treasurys fell 50 basis points from their April peak even as core and headline inflation surprised to the upside in the first half of the year.
At the same time, however, the low yield environment coupled with investor desire for income led to increased demand for high yield bonds, and thus driving down credit and quality spreads to levels not seen in several years.
On the commodities side, lumber prices have also made headlines with their exponential rise and sharp selloff this year. Even so, prices for real estate and commodities are higher on balance given solid demand for housing and as consumers get out and about in this post COVID world. To this point, the NAREIT All REIT Index gained 21% during the first half of the year, while the S&P GSCI Commodity index was up 30%.

Second Half Outlook: Not Out of the Woods Yet
Certainly, the economy and financial markets have shown solid improvements during the first half of the year. But a key question right now is, "can we let our guards down and rely on the positive developments to carry performance into the latter half of 2021?" The short answer is, possibly not.
The reason for this caution comes from the fact that market participants, households, and business leaders alike will have many unknowns to contend with during the second half of this year. To be sure, an ascendant COVID Delta variant, accelerating inflation, and policy uncertainties likely will dominate the market and economic narrative over the coming months.
Inflation May be a Drag to Growth
While the US economy has made significant strides this year, it's essential to note that lingering political and healthcare concerns coupled with uncertainties surrounding inflation remain potent headwinds to market sentiment. While we expect the US economy to expand at around 6.5% this year, this estimate reflects a deceleration from solid growth earlier in the year.
Of these issues, rising inflation and, more specifically, how policymakers respond to it will remain top of mind for many market participants. And it's this uncertainty that likely will contribute to ongoing bouts of market volatility in the months ahead. As noted earlier, much of the recent inflationary pressures have come from global supply chain issues related to COVID lockdowns.
Even so, in recent testimony to congressional leaders, Fed Chair Jay Powell indicated that if inflation does not slow down as expected, the "[Fed] will use [their] tools to guide inflation back down." While such language has raised market expectations for a rate hike later this year, the path to that outcome remains highly uncertain and a headwind to positive market momentum in the near term.
Variant Spread a Key Risk to Sentiment
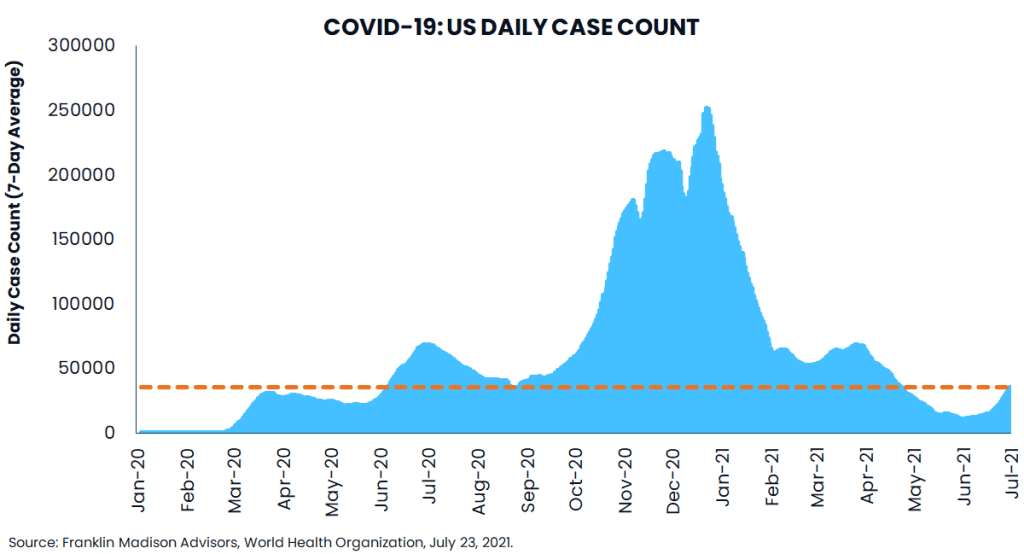
On the healthcare front, an infectious surge in the coronavirus Delta variant globally likely will give market participants reason for pause. Recent reports show that new cases are on the rise again in the US and are at their highest levels since mid-May.
Globally, less prepared economies are struggling to contain this highly contagious variant, which is putting downward pressure on economic growth projections. To this point, even countries that have seemingly overcome COVID, like Australia, have found themselves in lockdown once again.
What's more, a relentless spread of the Delta variant might once again complicate the US economic and market outlook as children return to school in the fall. Should efforts to contain the Delta variant fall short in less prepared economies (and at home), there's a potential for rolling global lockdowns, which could further upset global supply chains and keep prices elevated for an extended period.
Stay on Track to Financial Independence
So, what does this outlook mean for your financial independence journey? Well, while the economy and markets are indeed on the upswing, it's essential to note that we're not out of the woods yet. From a financial markets perspective, positive price action in risk assets this year has primarily been driven by an economic recovery narrative.
Lately, this narrative is coming under pressure as higher than expected inflation and the potential for another economic slowdown are bringing into question whether the Fed will raise interest rates sooner rather than later. The concern behind this approach is that policymakers may try to address inflationary concerns at a time when the economy is slowing, potentially reducing market liquidity and subsequently putting the markets on the back foot.
While Biden's infrastructure plan may offer another fiscal thrust to the economy, the latest iterations of the package may not provide the same impulse that the dual effects of monetary and fiscal stimulus provided early last year. From this perspective, positive market sentiment could begin to wane. Indeed, ongoing healthcare concerns, inflation worries, and policy uncertainties may all contribute to higher levels of market volatility in the months ahead.
So, what can you do to ensure that your plans for financial independence stay on the right track? Well, at this crossroads between still buoyant market sentiment and economic uncertainty, we recommend evaluating your risk management process and giving your attention to two key points of consideration.
Reposition Your Investments for Risk
First, whether you're still building wealth or relying on it to fund your post-employment years, now might be a good time to rebalance your investment portfolio. Sharpen your pencil and position your portfolio to take advantage of potential sales in pro-cyclical investments like emerging markets, small caps, and value stocks if you're in the wealth accumulation phase of your financial independence journey.
For those of you dependent on your wealth to remain financially independent, now may be the time to raise enough cash to meet living expenses in anticipation of a market pullback. This approach might involve taking some of your winning positions off the table, adding to cash to cover near-term lifestyle expenses, and reducing the need to sell at inopportune times if you're already dependent on retirement income.
Now is also a good time to evaluate trimming unnecessary risky positions in your portfolio and focusing on more high-quality, tax-efficient investments. At the same time, you'll want to be sure that your portfolio is closely aligned with your long-term asset allocation objectives. Why? Well, when market volatility does pick up, you'll want to ensure that your retirement nest egg has a fighting chance to quickly recover from a period of heightened market volatility.
Check Your Assumptions
Finally, it's hard not to ignore the rising cost of living. Whether inflation is truly transitory or not is yet to be seen. Either way, inflation rates may be unlikely to return to pre-pandemic levels once global supply chain issues are resolved. To this point, if you haven't already evaluated the inflation assumptions in your financial plan recently, now may be an opportune time to recheck them. The reason being is that higher than anticipated inflation over the long term could result in your spending more than expected in retirement and lead to cutting your financial independence plans short.
That's why it's essential to periodically review assumptions used in your retirement plan, evaluate whether those assumptions are generous considering the changing economic environment, and make necessary adjustments today to ensure that your financial independence journey is on track for the long term.
Biden’s Infrastructure Plan: Will a Deal Get Done?
City streets had been flooded for hours before the hurricane made landfall in Louisiana on the morning of August 29, 2005. Levees all around New Orleans had collapsed, and by 5 a.m., the city's largest canal, the 17th Street Canal, failed.
Over 1,800 souls lost their lives, and billions of dollars in damage was left in the wake of Hurricane Katrina. Scientists predict that once-in-a-generation natural disasters like this one may become more prevalent in the coming years, given the effects of climate change. Even so, President Joe Biden's infrastructure plan intends to address this genuine concern.
The American Jobs Plan
In a speech delivered just outside of Pittsburgh in late March, President Biden introduced the American Jobs Plan. This sweeping initiative would spend over $2 trillion to prevent infrastructure disasters like the one in New Orleans and provide a renewed foundation for businesses and individuals to compete globally in the twenty-first-century marketplace.
To be sure, President Biden's proposal is more ambitious than we've seen in generations. His package includes spending on preventable infrastructure failures while funding traditional bridge and road repairs. Simultaneously, the plan makes provisions for investments in quality-of-life essentials like clean water, quality education, and telecommunications improvements while funding caregiving assistance for an aging population and creating globally competitive U.S. manufacturing jobs.
Proposed Spending on Biden's American Jobs Plan

Following decades of false starts, it appears that the U.S. is finally on the cusp of beginning its most ambitious infrastructure program in years. But will a deal get done? Now, Joe Biden isn't the first president to propose ambitious infrastructure spending. In fact, many infrastructure plans have been introduced in recent years. From Clinton to Bush, Obama and Trump, each administration put forward its ideas to repair bridges, fix roads and future-proof the economy, only to face gridlock on Capitol Hill.
A lack of political will
There's little debate among members of Congress that U.S. infrastructure is in desperate need of repair. From preventable levee failures in New Orleans to a bridge collapse in Minneapolis and bus-swallowing sinkholes in Downtown Pittsburgh, politicians have voiced their concerns about the work that’s needed. Nevertheless, a challenge for previous administrations has been an inability to overcome a lack of political will to get a meaningful infrastructure bill passed through congress. Will the Democratic president’s proposal meet a similar fate?
On the surface, taxes and spending appear to be a central point of contention for some GOP members. To this point, the Biden administration is striving to find middle ground. Even so, a key challenge may be a deep-seated issue of politicians worrying that they'd be unable to defend a trillion-dollar bill to their constituencies who may not see the benefits of the legislation for years to come. So, what's changed that would enable an infrastructure deal to get done this time around?
Impetus for deal making
Well, first, there's the issue with China. Both Republicans and Democrats agree that China’s economic advance has come at a cost for U.S. businesses and workers. While taking on China directly is one approach to the matter, there's little doubt that failing infrastructure is hampering our country’s ability to compete with the world's second-largest economy. Therefore, addressing deferred maintenance and investing in technologically underdeveloped parts of the economy will be essential to responding to economic challengers and preserving our nation’s global leadership.
Second, before COVID-19, arguably few widely relatable examples existed to demonstrate how fundamental education, childcare, and eldercare are to the smooth functioning of the economy. The coronavirus nevertheless laid bare the striking deficit in U.S. social infrastructure. To be sure, many of us have had intimate experiences with the education and healthcare shortfalls amidst the pandemic. Looking ahead, it is difficult to dispute how investments in these vital areas of the economy will be essential to creating and supporting a competitive and productive labor force for generations to come.
And speaking of productivity, the pandemic showed how efficient technological infrastructure can keep some workers engaged and how investments in next-generation technology (like 5G) might further boost worker output. At the same time, however, the healthcare crisis exposed the stark inequalities as many households fundamentally lack access to necessary technological infrastructure. Whether it's for school, work, or to register for a vaccine, the technology divide further reveals economic weaknesses that must be addressed if we are going to promote tools that benefit everyone in all aspects of our lives.
Will a deal get done?
So, will Joe Biden's American Jobs Plan make its way into law this year? Will a deal get done? Well, politics is fraught with uncertainty, and truly anything can happen in the coming months. However, what is certain are the shortcomings in our transportation, technological and social infrastructure amidst rapidly changing natural and geopolitical environments.
Indeed, Katrina exposed the inadequacies of our infrastructure amidst climate change while COVID showed us how a lack of social infrastructure investment might put one of the most technologically advanced economies at risk of leaving its citizens, and truly, the nation as a whole, behind. The implications of these glaring disparities and shortcomings are today harder to ignore and might be reason why, after decades of fits and starts, politicians from both sides of the aisle may defend spending large sums to finally get a deal done.
Look for Investment Opportunities in a Biden Win
The outcome of next month’s Presidential Election is likely to be of great consequence for the US economy and financial markets. Given former Vice President Joe Biden’s recent gains in the polls, it’s possible that the market narrative driving markets could turn if Biden clinches a victory in November.
This narrative shift means that investment strategies that may have worked over the past six months could struggle to maintain their momentum as we move into the coming year. That’s why regardless of your political leanings, we believe that it is critical now more than ever to consider how a change in the White House might affect your investment portfolio in the coming years.
Can We Trust the Polling Data?
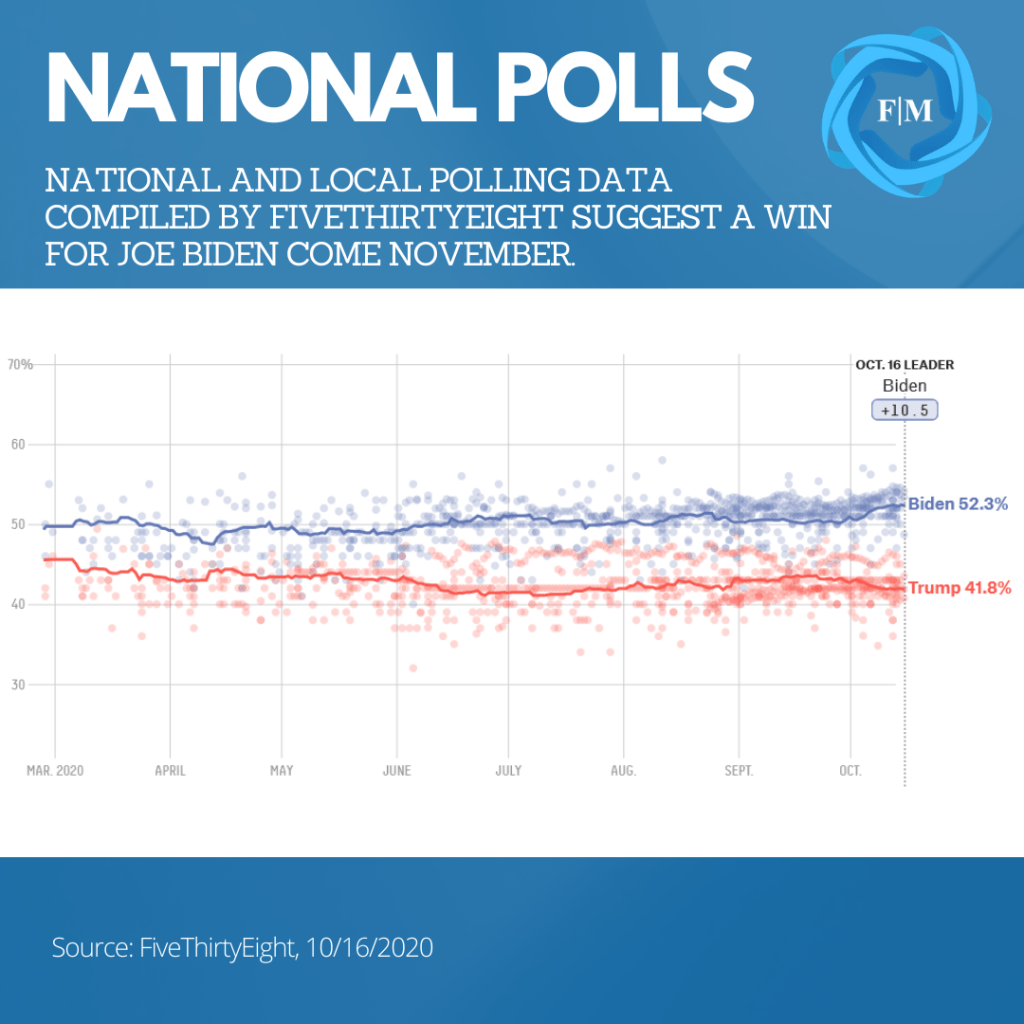
Who’s going to win the Presidential Election? Well, a lot can happen in a few short weeks. Nevertheless, Joe Biden has recently enjoyed a double-digit lead ahead of President Donald Trump in the national polls. According to surveys compiled by FiveThirtyEight, Biden is leading Trump by an average ten percentage points at the national level.
Even so, when it comes to presidential elections, what history has shown is that the polling data coming out of state-by-state contests are more instructive than the national figures themselves. And this point was made abundantly clear in 2016 as Hillary Clinton won the national popular vote but lost the electoral college as she trailed in battleground states.
How is Biden projected to do in these critical state races? Well, if elections were held today, data suggest a likely Democratic sweep in the Presidential and Congressional races. This outcome is reflected in data for crucial states like Florida, Pennsylvania, Michigan, and Wisconsin (states lost by Clinton) where polling is more favorable of Biden win.
So, what might such an outcome mean for your investment portfolio? Well, a Democratic sweep could bring significant changes in tax policy, fiscal spending, and infrastructure initiatives that may shift some investor preferences while at the same time bringing in a new set of investment opportunities. Let’s take a look at some of these potential changes in a little more detail.

Potential Pivot Out of Growth?
The tax plan outlined by the Biden campaign is a big deal. It’s crucial to remember that the Tax Cuts and Jobs Act (TCJA) passed in 2017 promised a boost to economic growth as tax rates on high earners and corporations were lowered significantly. Biden has promised to roll back certain provisions of the TCJA to pay for his administration’s economic policies. So, what exactly does this mean for the individual investor?
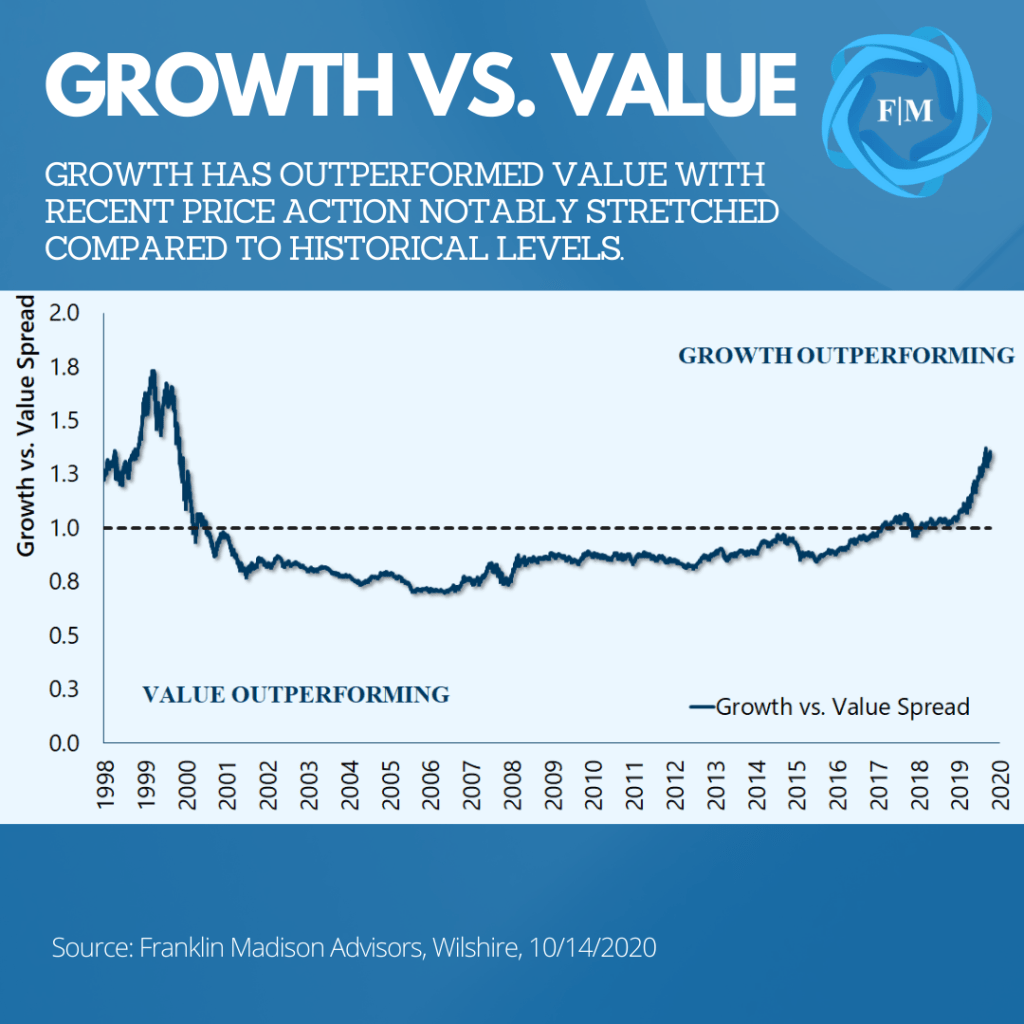
Well, under the scenario of a Biden win, there is a greater incentive for investors to cash out on asset classes that have performed well in recent years. To be sure, the rally in growth-oriented stocks has been seemingly unstoppable over the past few years. More recently, strong performance in this segment of the markets has been underpinned by a flood of cash resulting from government spending and easy central bank policies. Even so, investors will have to contend with two vital issues under a new administration.

First, the prospect of diminished after-tax corporate earnings likely will make it harder to justify holding investments already trading at a significant historical premium. Put differently, growth is expensive, and higher taxes won’t make them any cheaper. And second, the prospect of higher future capital gains taxes might incentivize some investors to lock in tax liabilities at today’s lower capital gains rates. From this perspective, it’s quite possible that the once favored growth/tech sectors could underperform the broader markets following a Biden victory.
While it might take months for a bill to make its way through congress, market participants likely won’t wait around to reposition themselves ahead of such a move. In fact, it’s quite possible that investors could rotate out of favored sectors shortly after an election day win. This means that market sectors that have benefited from lower taxes are likely to face headwinds given higher tax prospects.
Cyclical Opportunities
Another point to consider is that under a new administration, government spending will likely rise substantially due to additional fiscal stimulus and changes in economic policy. As of this writing, congressional leaders are still trying to strike a deal on another round of fiscal stimulus that would address the COVID-related economic slowdown. Whether this package is agreed to before or after the elections, another roughly $2 trillion in government spending will likely make its way into the economy in the months ahead.
This much needed fiscal boost comes at a time when data show that US economic growth is recovering but remains at risk of stalling out. Indeed, weekly jobless claims data this week showed that the number of individuals seeking unemployment benefits rose to a two-month high after declining in recent weeks. And without additional government spending, recent economic gains are likely to falter, leading to stagnating growth and a long road to recovery.
Under Democratic plans, a second stimulus bill would provide support for households and businesses and give aid to state and local governments (a point contested by GOP leaders). From an investment perspective, this additional fiscal boost to state and local governments could open the door to attractive income-oriented opportunities, most notably in the municipal bond space.
What’s more, for an economy struggling to regain its pre-coronavirus footing, relatively higher government spending levels would likely be favorable overall for economic growth. In such a scenario, the pivot away from growth-oriented sectors resulting from higher taxes might lead to greater favor for value and cyclically oriented parts of the market as government spending raises expectations of a faster economic recovery.
Infrastructure Spending and Industrials
It’s also important to note that Biden has proposed policies that could inject over $5 trillion into the US economy over the next decade, with infrastructure leading the spending push. Under the Build Back Better plan, a Democratic sweep could finally usher in a long-awaited infrastructure bill that puts individuals to work addressing the country’s crumbling infrastructure.
While the stimulus bill waiting in the wings could likely support a rally in cyclical sectors broadly, the Biden campaign’s proposed policies may also provide an additional boost to the industrial and materials sectors, specifically as money pours into national construction projects. What’s more, a Biden administration focused on achieving a carbon pollution-free power sector by 2035 might underpin opportunities in the green-energy oriented space and further support gains in certain Environmental, Social, and Governance (ESG) investments.
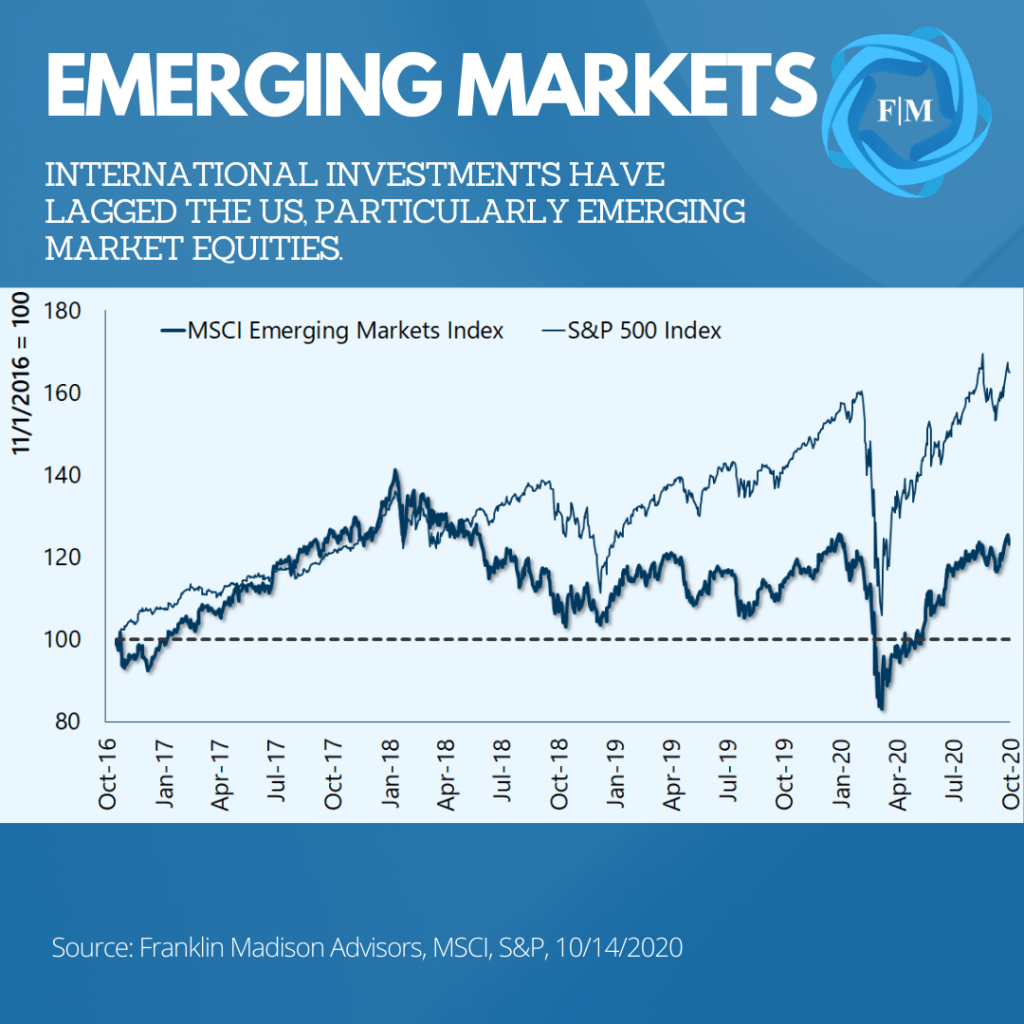
Reduced Foreign Policy Risk Premium
Finally, an administration change could reduce the foreign policy uncertainty premium that has arguably supported US over international investment exposure. On the China front, Biden is likely to push forward on completing a trade deal with China (and Europe). What's more, it’s also possible that the narrative surrounding trade negotiations under a new administration might present fewer surprises and thus even out policy uncertainties compared to Trade War related events in recent years.
This lower risk premium, combined with ultra-loose Fed policy, could place downward pressure on the US dollar and potentially incentivize increased investor exposure to global investment opportunities. Structurally, we’ve laid out a case for investing in emerging markets for the long-term, but such an outcome could be favorable for non-State Owned Enterprise (SOE) Chinese stocks in the short run.
Domestically, greater policy uncertainty could provide more favorable prospects in traditional high yield opportunities. Like international asset classes, high yield bond prices are susceptible to sudden swings in market sentiment. With a reduced policy risk premium, income-oriented investors might benefit from higher-quality “fallen angel” opportunities in the high yield space.
Look for Investment Opportunities in a Biden Win
Taken together, a Biden win might usher in a greater need for tax efficiency and less reliance on capital gains for income-oriented investors. A change in the White House may also mean a shift in the market narrative that is balanced less towards growth sectors and more towards cyclicals as fiscal spending boosts economic growth up in the coming year. Finally, the foreign policy risk premium that has favored US markets in recent years could open the door to more international opportunities as foreign policy-related volatility ebbs.
In either case, in the days leading up to the election, markets are likely to ebb and flow along with a host of unknowns. As an investor, you may be rethinking your market risk exposure or even contemplating exiting the markets altogether before election day. To be sure, whatever the outcome might be, November 3rd is likely to mark a turning point for the next chapter of the dominant market narrative.
Even so, during this time of uncertainty, we recommend that you consider these post-election investment opportunities before the narrative shifts while staying committed to your long-term investment plan and positioning yourself for higher levels of market volatility.
Are Stocks Setting Up for a Second Quarter Repeat?
U.S. stocks had a blockbuster second-quarter. Indeed, both the Dow and S&P 500 have posted their best returns in decades. How long can this outperformance last? With market sentiment still generally positive, some investors are asking whether supportive central bank policies and hope for a rapid economic recovery may be the set up for a third-quarter market surge.
We believe that the dominant narrative that had supported the second-quarter rally is increasingly coming under pressure. Stretched asset valuations and a historical precedent for weaker market returns argue for more caution in the coming quarter. As a result, we recommend that investors use recent market strength to reduce investment risk and raise cash through portfolio rebalancing.

Stocks Had a Stellar Second Quarter – What are the Chances of a Repeat?
Last quarter's rally came on the heels of a sharp market pullback. Efforts to flatten the curve in March led to a massive experiment that had not been tried in well over a century: shut down the economy to curb a pandemic.
Risk assets experienced a sharp selloff in the first quarter on the prospect of weaker economic growth but regained their footing at the start of the second quarter. The rally arguably was fueled by a hope that massive fiscal and monetary stimulus efforts could contribute to a rapid economic rebound.
For example, Congress and the Federal Reserve responded to ballooning unemployment and economic uncertainties by launching unprecedented stimulus programs. On the fiscal side, several million businesses in the US received financial support through the Paycheck Protection Program (PPP). The government also issued cash handouts to unemployed workers and households alike.
At the same time, the Fed ramped up purchases of government bonds and mortgage-backed securities. The central bank also launched its Main Street Lending Program to make it easier for small businesses to borrow money. In late June, the Fed began purchasing private firms' bonds through its Secondary Market Corporate Credit Facility (SMCCF). In a matter of weeks, the Fed increased its balance sheet by well over two trillion dollars – a feat that had taken years to accomplish during the Great Recession.
The critical takeaway here is that the second quarter market rally was built upon low price levels and expectations that policy efforts could support a rapid rebound in economic growth. This narrative, however, is increasingly coming into question.

History Suggests Softer Performance
Another important point to consider is that there is little historical precedent for a repeat of second-quarter market performance. We know this because we analyzed data to determine how markets have performed historically following a sizeable rally. Our work suggests that the return on the S&P 500 index in the third quarter could be less than half the 20% realized in the second quarter.
For example, history shows that the S&P 500 rallied 15% in the three months following market lows set in March 2009. How did the index perform in the next quarter? Well, the index gained only 5.5% in the next quarter. And this observation is not limited to just one period in time.
Looking at a distribution of returns going back to 1930, we find that market returns tend to come in between 0-10% in the quarter following a strong market rally at about two-thirds of the time. To be sure, the data showed that market performance on the heels of a massive rally was not only softer in the next quarter, but they were also consistently weaker 98% of the time.
The crucial takeaway here is that, from a historical perspective, strong returns do not beget even higher returns. While the historical data suggest that performance is quite likely to remain positive in the third quarter, from a purely statistical perspective, it's hard to make a case that we'll see even higher returns in the months ahead.
Unmitigated Healthcare Crisis
Finally, it's important to note that the healthcare crisis is not improving, and this will challenge the market's rapid recovery narrative. At the onset of the outbreak, there was a notion that if we locked down the economy and reopened in a deliberate, intentional way (think phase red, yellow, green), we'd be able to contain the coronavirus outbreak, and quickly have life get back to normal.
After initial success in flattening the curve, we're now seeing that COVID19 cases are reaccelerating weeks after much of the US economy has reopened. With vaccine trials still ongoing, and infection rates currently on the rise, there's a real risk that we may end up with a healthcare crisis more severe than the one we had in March.
Such an outcome could lead to delayed household spending and employer hiring decisions, challenging the dominant market narrative that supported second-quarter market performance. Indeed, with more state governors reversing or delaying plans to open their economies, it is becoming increasingly difficult to make a case that markets can continue to rally on hope of a sudden economic recovery.
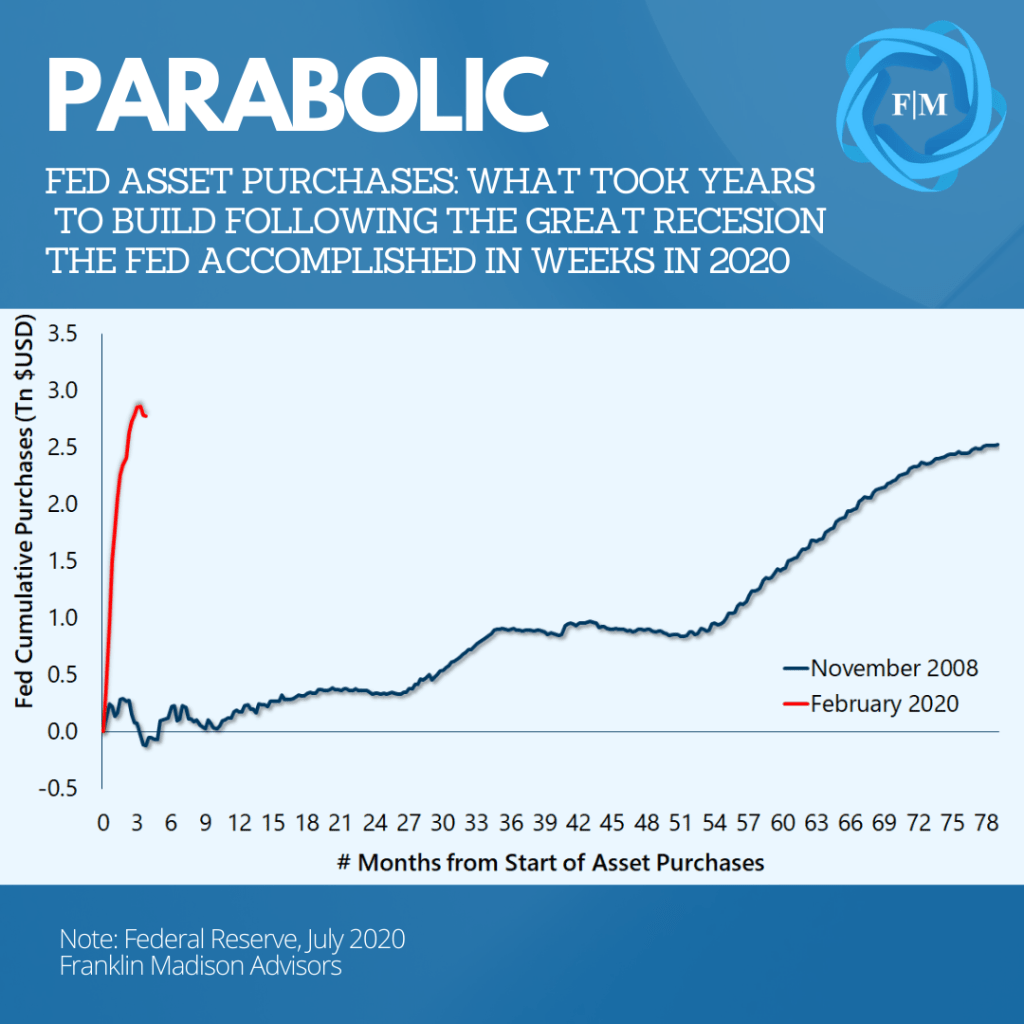
What Should Investors be Mindful of Heading into the Third Quarter?
Investors should be mindful of the fact that expectations for the future often drive market behavior. Presently, there are arguably two vital expectations supporting market sentiment: 1) policy response will fuel economic growth, and 2) economic growth will quickly recover. Right now, it's unclear whether monetary policy can do more than stabilize economic conditions.
Monetary Policy is not a Panacea
Monetary policy can only do so much to support economic growth. With that said, there is little doubt whether the Fed will pull out all the stops to stabilize growth. The Fed's willingness to support its full employment and inflation mandates is evident in the various programs mentioned earlier. Even so, monetary policy is not a panacea for market-related concerns.
Take, for instance, the Bank of Japan. This central bank has been buying public and private sector stocks, bonds, and real estate for years. It has implemented non-traditional measures such as a negative interest rate policy and yield curve control. Japan's economic growth has nevertheless been weak, and the performance of its markets has lagged its peers. A similar situation is present in the Eurozone.
Anecdotally, history has shown that markets tend to stage an early rally based on expectations of a massive game-changing catalyst, like an election, a rise in government spending, or a favorable change in monetary policy. Today, such expectations are playing out in mantras like "don't fight the Fed." Even so, what we've observed over the past couple of decades is that such rallies tend to wane as market participants eventually reset their expectations to the reality that policy alone does not heal what's ailing a struggling economy.
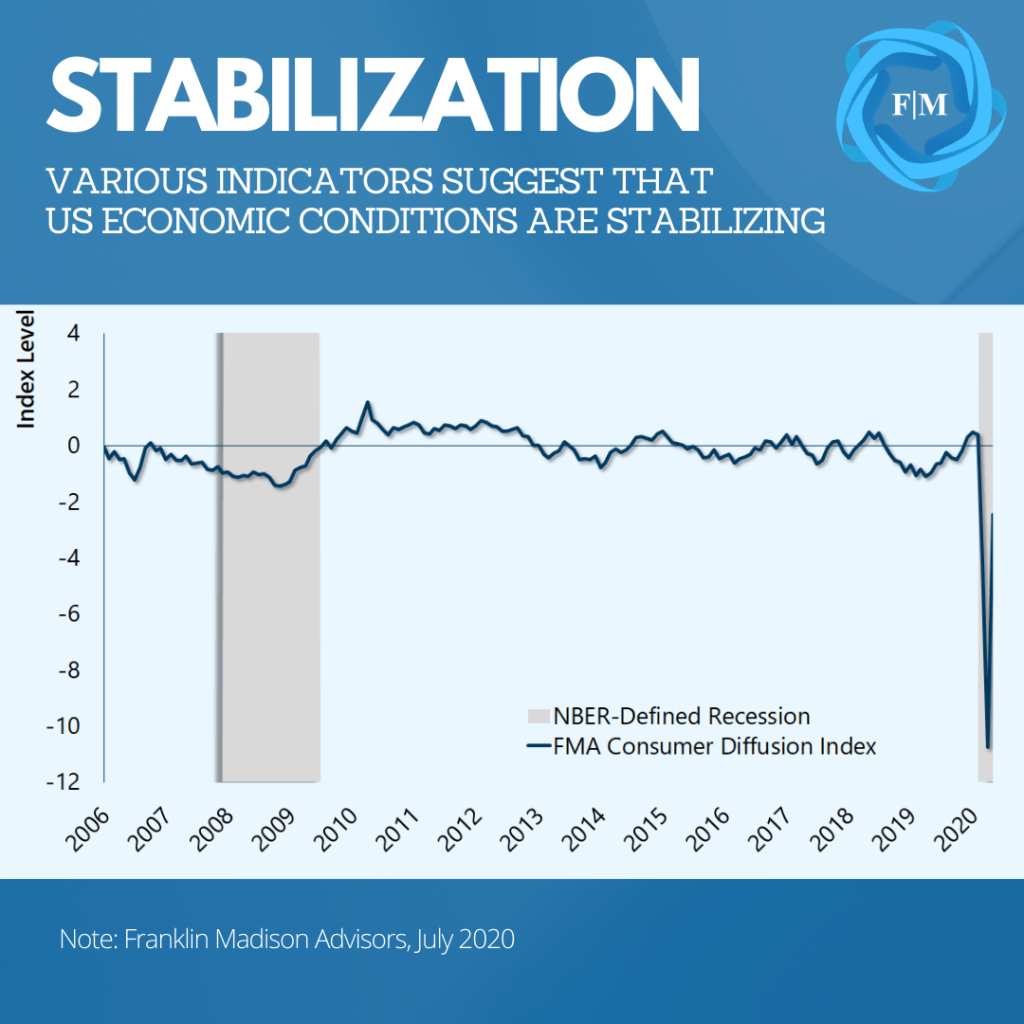
Economy stabilizing, growth likely to struggle
Another issue with which investors must contend in the coming quarter is that weaker growth will challenge market sentiment. While some data have improved, reports are not yet consistent with a robust economic rebound. To this point, the IMF recently downgraded its estimate of a US economic recession from -5% set in April to -8% (consistent with the Great Recession) in June.
This view does not dismiss the fact that by some measures, the economy is stabilizing. Our own consumer and business diffusion indices show that US economic activity is recovering from lows set in April. Even so, these backward-looking indicators need to be reconciled with forward-looking realities: households are increasingly likely to curb spending amid the ongoing healthcare crisis.
A rising number of states are reporting record one-day coronavirus infection rates. The effect of which has led some governors to postpone reopening their economies and others to shut down establishments like bars and restaurants. Prolonging the economic lockdown may curb the recent consumer spending recovery.
Compounding the problem of lower consumption is the fact that individuals willing and able to spend are finding it harder to borrow money. This issue is evidenced in the Fed's recent Senior Loan Officer Survey. It shows that banks are less willing to lend and that they are also raising lending standards. The implication is that individuals ready to spend, especially on big-ticket items like homes and cars, may find it increasingly difficult to obtain the loan necessary to complete their purchase.
Indeed, there's no question that the US economy is showing signs of having stabilized. Nevertheless, the ongoing healthcare crisis likely will alter household spending behavior and challenge market expectations of a quick economic recovery.
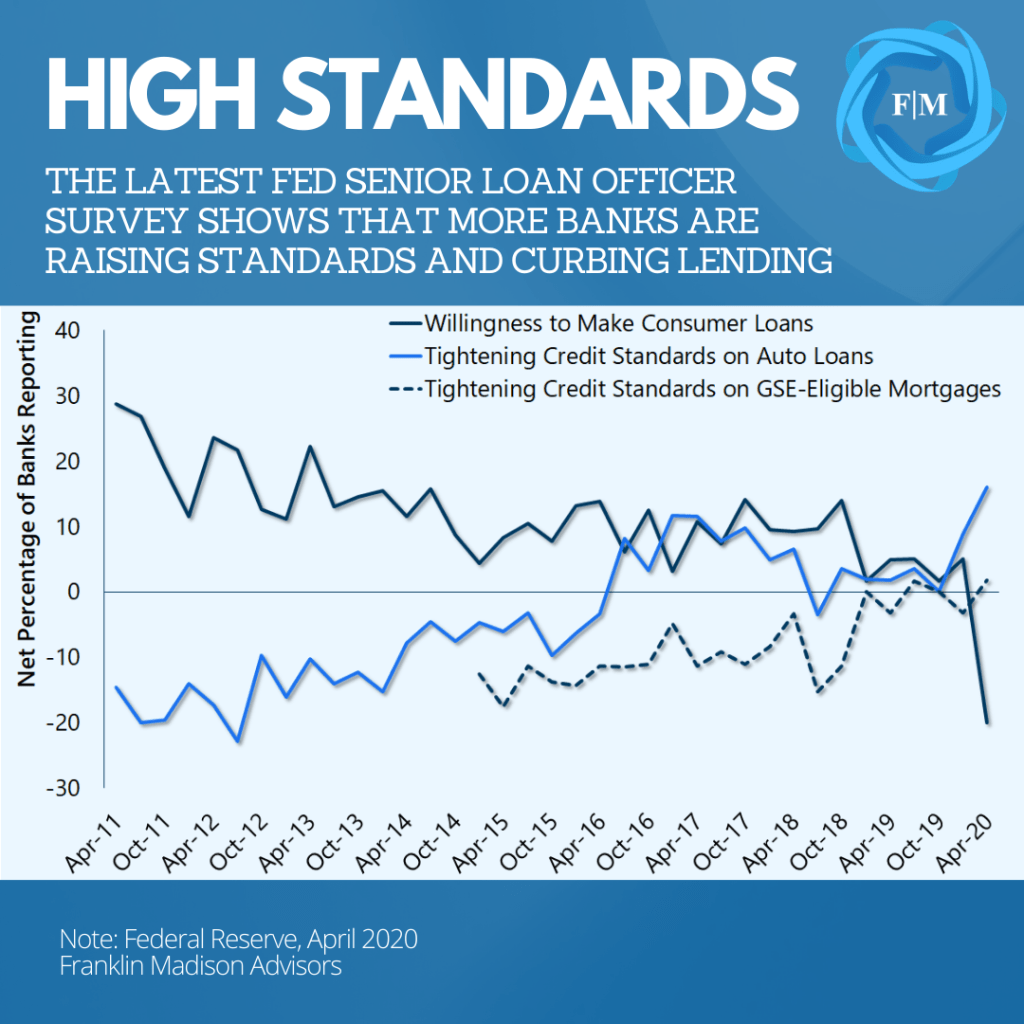
How should investors prepare for lower returns and ongoing uncertainties in the third quarter?
It's important to note that the second quarter rally has led to risk assets becoming expensive when measured by various valuation metrics. The combination of high asset prices and an unmitigated healthcare crisis may contribute to higher market volatility in the months ahead. In anticipation of a market pullback and increased volatility, we suggest that investors pare back recent gains to achieve two ends.
First, during this time of uncertainty, investors need to manage risk and ensure that their portfolios align with their long-term goals. Periods of market strength like we experienced in the second quarter can lead to portfolio drift. Therefore, we suggest that investors use recent market strength to trim winning positions and add to under-allocated holdings. This can be accomplished through portfolio rebalancing that realigns investment holdings with long-term target asset allocations.
Second, we recommend that investors prepare to use market volatility as an opportunity to raise cash. Periods of heightened market volatility may lead to selling assets at inopportune times. This is especially important given the tenable economic environment and ever present need to address unplanned life events. Therefore, we recommend that investors use this period of market strength to bring their portfolios back into alignment with long-term goals through rebalancing while at the same time setting aside some cash to meet unexpected needs.
Another Recession is Here. Now What?
It's unofficially official: we're in an economic recession for the second time in two years. At least, that's according to government data published this week.
This news comes from the Bureau of Economic Analysis' latest report on economic activity, which showed that U.S. Gross Domestic Product, or GDP growth, contracted during April, May, and June, marking the second straight quarterly decline so far this year.
And by some measures, two consecutive contractions in GDP is considered the start of a recession.
What is a Recession?
So, with all of this talk about a recession, some of you may be asking, “what exactly is a recession?” Well, as of late, there's little consensus as to the definition of a recession. In fact, the White House has been working hard this week to redefine what it means to be in a recession. Nevertheless, a recession can be defined as simply a decline in economic activity over some time.
And it's important to keep in mind that recessions are not caused by a single event, but instead occur as a result of many factors, including rising interest rates, higher inflation, declining consumer spending and investment, falling production capacity and rising unemployment.
Now, our country has been through 48 recessions since its founding. And since 1947, when government statistics were gathered more consistently, data show that we've been through about twelve recessions in the past 75 years.
Of those twelve recessions, ten of them have occurred when two quarterly GDP declines were in place. So, from this perspective, if we use history as our guide, we could safely say that a two-quarter decline in GDP growth is consistent with a recession.
So, Are We in a Recession?
Now, it's important to note that while we've experienced two consecutive declines in economic growth, the official measure of a recession is often broader than looking at GDP alone.
To be sure, the National Bureau of Economic Research, or NBER, considers several indicators before officially calling a recession. They look at what’s going on in the labor market, consumer spending, industrial production, and other measures before calling slowing growth a recession.
While some of these indicators have softened recently, they’re generally in what appears to be still positive territory. With that said, if we look back to the Great Recession, we find that while the NBER called the recession starting in December 2007, industrial production didn’t roll over until April of the following year.
We can even go back to the recession of 2001 around the Dot Com bust to find that there’s no singular measure of a recession. For example, while the NBER called a recession starting in March 2001, GDP did not even go through a two-quarter contraction during this period. Nevertheless, U.S. economic activity did experience a decline broad enough to have been considered a recession.
With all that said, the NBER does not have a track record of calling recessions in real-time, and often they confirm their findings only months after a recession has already begun or ended.
So, are we in a recession? Well, the short answer to this question is likely yes.
While the NBER hasn't officially come out and called a recession yet, there's a solid reason to believe that we may be in one today. Again, over the past 75 years, there's been a couple periods where the economy experienced a two-quarter decline, and a recession did not occur, and that was in 1947.
Since then, every recession has been accompanied by a two-quarter decline in GDP like we've experienced so far this year.
How Does a Recession Affect Me?
Now, given all the headlines surrounding recessions, you might wonder how today's current events affect you.
Well, how a recession might affect you depends on your situation and where you're at in your financial independence journey.
If you are in the accumulation phase, saving money and preparing for your definition of financial freedom, you may have some obstacles to navigate in the months ahead. For instance, layoffs tend to rise during economic downturns, so having an emergency cash reserve on hand to deal with a potential unemployment situation will be essential to navigating this period of economic uncertainty.
With that said, if your emergency savings are topped up, and you're feeling confident about your current job prospects, then a recession might provide you with an opportunity to buy financial assets at a discount or invest in distressed real estate or other business ventures as the economy weakness.
Now, you'll likely find yourself with a unique set of challenges if you're an individual in the distribution phase of your financial independence journey. For example, market pullbacks or bear markets often accompany recessions.
And by many measures, we're already in a bear market today.
So, if you're currently dependent on your investment savings to cover living expenses during retirement, then taking distributions from your portfolio when prices are down could mean locking in market losses at an inopportune time.
If you've been following along with our commentary over the past few months, however, then you'll likely know how imperative it is to have an adequate cash reserve to cover 12-18 months of living expenses during this time.
This cash buffer can allow you to maintain your standard of living even during a recession-induced bear market, while giving your portfolio enough time to recover once the economic outlook clears up.
While recessions can be devastating to individuals, businesses, and the economy at large, they are not always a bad thing: when the economy contracts it means financial resources are being allocated more efficiently. And this can help to correct imbalances within the system, especially after an extended period of loose monetary and fiscal policies and free-wheeling market conditions.
Fortunately for most people, it's possible to weather even severe economic downturns as long as you're prepared financially and emotionally.
Preparing for a Recession: Start with Your Plan
So how should you position your finances for weaker economic growth and heightened market volatility in the months ahead? Well, if you're an individual focused on mastering your financial independence journey, the short answer is to stay committed to executing on your long-term financial plan.
During times of economic and market uncertainty, for some of us, there's a tendency for our vision to narrow to the present, tempting us to change the way we handle our finances or investment allocations as a way to mitigate what appears to be an immediate financial threat.
Even so, if you have a well-structured financial plan and a disciplined investment process already in place, then the action that you'll likely need to focus on today is consistently doing the work necessary to execute your plan.
To be sure, if you have a well-crafted financial plan already in place, then those actions should be defined in your implementation schedule. Otherwise, developing a set of strategies to align your financial resources with your long-term goals should be a priority if you don't already have a comprehensive financial plan in place.
Certainly, a solid financial plan lays out how to connect the dots between your financial resources and ideal long-term lifestyle goals. At the same time, it identifies predefined strategies and tactics that you can tap into to manage adverse conditions when they inevitably arise in the near term.
Have Adequate Cash on Hand
Once your financial plan is in place, the next thing you'll likely need to focus on is getting back to the basics.
What do we mean by getting back to the basics? Well, what we mean here is ensuring that you have enough cash on hand to weather the impending economic storm, whether you're dependent on a job or a retirement nest egg to cover your household income needs.
When it comes to managing your portfolio during a recession, there's no substitute for cash. Sometimes it can be hard to get excited about cash, but in a recession, having some money in reserve can save your investments and keep their value whole while waiting out the downturn.
Cash is also necessary because it's a great way to rebalance your portfolio back toward its original goals if something causes some of your investments to perform poorly (which often is inevitable!).
Having cash on hand to be able to buy more shares of one security or another when prices decline may enable you to take advantage of opportunities and spread risk across various asset classes. This is one reason why we advocate for maintaining investment exposure across stocks, bonds, and real estate in both U.S. and international markets.
Assess Your Current Portfolio
The next step for investing during a recession is to get a good picture of your current portfolio. What's in it? How much risk are you taking? What are your investment goals, and how much risk can you stomach?
Now that you have a good understanding of where you stand, think about how to protect yourself during an economic downturn.
Don't Panic and Don’t Sell Everything
One essential way to safeguard your investment portfolio is to protect it from yourself. While headlines will focus on the negatives that recessions often bring, you'll likely need to remember that this is not the end of the world—it is just a temporary setback.
You likely already went through this back in 2020 and made it through in one piece.
Certainly, no one can predict what will happen next, but if you sell everything now, you may be selling at a loss and will regret it later.
Another Recession is Here. Now what?
When it comes down to it, various indicators suggest that we're likely already in a recession. And this time around, the government likely won't be ready to cut checks and support the economy as it had in the past.
That's why if you're serious about mastering your journey to financial independence, then now's the time to ensure that you have a solid financial plan in place, that your investment strategy is aligned with your long-term plan and that you're effectively executing on your implementation schedule.
If you are afraid of losing money in your investments, don't panic and sell everything; instead, get some professional advice from someone who knows what they're doing.
Most investors get through downturns just fine if they have a little patience and a good strategy.
Many investors who lost money during the Great Recession or during the Pandemic did so because they didn't have a diversified portfolio or got out of the markets altogether.
And there's no such thing as a perfect investment strategy. But if you have a plan and stick to it, you'll be in better shape than most.
If you've been through a recession before, you know how difficult it can be. But if you have a solid strategy and stick to it, it doesn't have to be all that stressful. The key is to have enough cash on hand to navigate market and economic uncertainty.
And again, stay calm and don't panic sell your investments just because there's bad news out there! Remember: recessions come and go. But over time, they can provide tremendous buying opportunities and allow the value of a diversified portfolio tends to go up in value over the long-term if bought at reasonable prices.