Five Reasons Why a Roth Conversion Might be Right for You
You've done everything right: you've worked hard, built a successful career, and saved for the future. But there's one piece of the puzzle that could quietly erode your wealth if you don't plan for it: taxes.
Retirement isn't just about how much you've saved, it's about how much you get to keep. And if most of your retirement savings are in tax-deferred accounts like a 401(k) or traditional IRA, the IRS has plans for that money. That’s why tax planning is crucial now more than ever.
In fact, when it comes to IRAs, those withdrawals you take in retirement will be taxed as ordinary income, and when you turn 75, Required Minimum Distributions (RMDs) will force you to take money out, even if you don't need it.
But here's the thing: what if you could pay taxes on your own terms?
What if you could lock in today's lower tax rates, reduce your future tax burden, and create a more flexible income strategy for retirement?
That's where a Roth conversion comes in.
In fact, by converting a portion of your tax-deferred retirement savings into a Roth IRA, you pay taxes on that money now and at a rate you can control.
In return, your Roth IRA grows tax-free, and when you need to withdraw in retirement, there are no additional taxes owed.
What's more, there are no RMDs, no surprise tax bills, and a better plan for passing wealth to your heirs when it comes to your Roth IRA.
But the big question here is is it the right move for you?
Well, the answer depends on several factors, including your current and future tax rates, your retirement timeline, and how you want to structure your income.
So then, let's break down five key reasons why a Roth conversion could be one of the smartest financial decisions you make in 2025.
#1 Would You Rather Pay Taxes at Today's Rates or Risk Higher Rates in the Future?
First things first, would You Rather Pay Taxes at Today's Rates or Risk Higher Rates in the Future? Think about it: do you believe taxes will be lower in the future? Or do you think they'll go up?
If you're like most people, you're betting on higher taxes. And that's not just a guess. The tax cuts currently in place are set to expire after 2025, which means tax rates for high earners could rise significantly. If nothing changes, the top tax bracket will jump from 37% back up to 39.6%.
And even if the Tax Cuts and Jobs Act is extended, there's no guarantee that tax rates won't go higher in the future given our country's massive debt burden.
Indeed, with rising government debt and shifting tax policies, higher taxes could become the norm. So then, if you wait to withdraw from your tax-deferred accounts in retirement, you could find yourself paying much more in taxes than if you had acted earlier.
That's where a Roth conversion lets you take control. Because instead of waiting to see what happens, you can lock in today's lower rates and create tax-free income for the future.
How so? Well, let's say you convert $500,000 from a traditional IRA to a Roth IRA today while you're in the 24% tax bracket. In this case, you'll likely owe $120,000 (24% of $500,000) in taxes today.
Now, let's assume you wait 10 years, but by then, higher tax rates push you into the 35% bracket. With that same amount, assuming no growth of your savings, you'd likely owe $175,000 (35% of $500,000).
That's a $55,000 difference, just for waiting.
And here's where it really adds up: if that $55,000 in tax savings were invested instead at an average 7% annual return, it could grow to over $400,000 in 30 years, all because you converted when rates were lower.
So then, by making a move today, you're not just reducing taxes, you're potentially adding hundreds of thousands of dollars to your retirement savings all by paying some tax today, to save a lot more in the future.
#2 Do You Want to Avoid Required Minimum Distributions (RMDs) That Could Inflate Your Tax Bill?
The next thing to consider when it comes to determining whether a Roth Conversion is right for you is whether you're comfortable paying your anticipated RMDs.
Now, you may not need the money, but the IRS does.
That's because by the time you're age 75, you'll be required to start withdrawing money from your traditional IRA or 401(k), whether you want to or not. And these Required Minimum Distributions (RMDs) aren't just forced withdrawals, they're taxable income.
Now, depending on how large your retirement accounts are, RMDs can push you into a higher tax bracket, trigger higher Medicare premiums, and cause more of your Social Security benefits to be taxed.
That's where a Roth conversion can help you get ahead of this problem. Because Roth IRAs aren't subject to RMDs, converting today means you keep more control over your income in retirement, instead of letting the government decide for you.
So then, how does this work? Well, let's say you're 65 years old with a $2 million traditional IRA, and it grows at 6% per year. Here's what happens if you don't convert any of it to a Roth.
By age 75, your RMD starts at $87,591 per year. But each year, Uncle Sam forces you to take out more and more money from your IRA each year. So then, by age 90, your RMD balloons to $258,741 per year.
That means you'll be withdrawing more and paying more in taxes, whether you need the money or not.
However, if you convert a portion of your IRA to a Roth before RMDs kick in, you might be able to reduce your future tax burden and avoid being forced into withdrawals you don't want to take.
Put a different way, this isn't just about tax savings, it's about having more flexibility in how you use your money in retirement. So then, wouldn't you rather make that decision yourself or have Uncle Sam force you to take money out of your savings? That’s where prudent tax planning comes into play.
#3 Do You Want to Leave More to Your Heirs Without a Tax Burden?
You've spent a lifetime building wealth, and now you're preparing to pass it on. But do you really want the IRS to take a big chunk of what you leave behind to your children?
Because here's the thing: if your heirs inherit a traditional IRA, they'll be forced to withdraw the full balance within 10 years, and every dollar they take out is taxed as ordinary income.
So then, if they're in their peak earning years, those withdrawals could push them into a much higher tax bracket, costing them hundreds of thousands in unnecessary taxes.
A Roth IRA, on the other hand, passes on tax-free savings to your heirs, and no forced distributions for a spouse. In other words, no income taxes for your kids and no surprises when they inherit your wealth.
How does this work? Well, let's compare a $1 million traditional IRA and a $1 million Roth IRA passed down to your children.
If the money stays invested for 30 years at 7% annual growth, here's what happens. With a traditional IRA, your heirs must withdraw all funds within 10 years, and assuming they invest it, after taxes, it grows to $5.8 million.
However, if you left behind the same $1 million in a Roth IRA, it's possible that the portfolio would grow tax-free to $7.6 million and be available for tax-free withdrawals. That's a $1.8 million difference, all because of taxes.
Even if your heirs don't need the money right away, a Roth IRA lets them delay withdrawals until it makes sense for them, avoiding tax spikes and keeping more of your legacy intact.
So then, if you're planning to pass on wealth, the question is simple: Do you want your money to go to your family, or to the IRS?
#4 Could a Roth Conversion Help You Save on Medicare and Social Security Taxes?
Most people don't realize that their Medicare premiums and Social Security benefits are tied to their taxable income. In fact, the more income you report in retirement, the more you could pay for healthcare and the less of your Social Security you'll actually get to keep.
How does this happen? Well, it happens because withdrawals from a traditional IRA count as taxable income. So then, even if you don't need the money, those withdrawals could push you above key income thresholds, and trigger higher Medicare premiums which could make up to 85% of your Social Security benefits taxable.
A Roth IRA on the other hand avoids this issue because withdrawals don't count as taxable income. That means you can take money out as needed without pushing yourself into a higher tax bracket or triggering unexpected penalties.
How so? Well, let's take a couple who are 67 years old and are planning to retire soon. They have $1.5 million in a traditional IRA and $60,000 in combined Social Security benefits per year.
Now, if they start taking $80,000 per year from their IRA, they're likely to face a few complications. First, their Medicare premiums likely will increase due to IRMAA (Income-Related Monthly Adjustment Amounts). Next, they could find that up to 85% of their Social Security benefits become taxable and so, their total tax bill and healthcare costs jump by over $112,000 over their retirement.
Now, let's say this same couple converts $300,000 over three years into a Roth IRA before claiming Social Security and Medicare. In this case, their taxable income stays below Medicare surcharge limits, their Social Security remains largely untaxed and they save over $112,000 in combined healthcare and tax costs.
So then, this isn't about avoiding taxes, it's about planning ahead, especially when it comes to balancing retirement income with goverment benefits. From this perspective, why give more to the IRS when you can keep more for yourself through prudent tax planning?
#5 Are You Planning a Move to a Lower-Tax State?
Finally, where you live in retirement matters a lot, especially if you're considering a Roth conversion.
In fact, if you're planning to move from a high-tax state like California or New York to a no-income-tax state like Florida, Texas, or Nevada, the timing of your Roth conversion could save you tens, if not hundreds of thousands of dollars in state taxes.
That's because when you complete a Roth conversion, you'll also end up paying state taxes in the year you convert. So then, if you do a Roth conversion while living in a high-tax state, you could owe state income tax on that conversion. But if you wait until after you move, you could pay zero state tax on the conversion.
How does this work? Well, let's say you have a $1.5 million traditional IRA and are moving from California to Florida. You decide to convert the full amount before moving and California state tax (13.3%) on $1.5M conversion leads to $199,500 owed in taxes.
Now, let's say you wait until after you move to Florida where you pay no income tax. Here, you could effectively save $199,500 in taxes just by planning your move before coverting.
But what if you plan to stay in a high-tax state? A Roth conversion might still be a smart move, especially if state tax rates are expected to rise. In other words, locking in today's rates could still be a win.
Regardless, if you're thinking about moving, or even if you aren't, state taxes should be part of your Roth conversion decision. Because when it comes to taxes, timing is everything.
So, What's Your Next Move?
Let's be honest. Nobody enjoys thinking about taxes. However, whether you think about them or not, you will pay them on way or another. So then, the real question is not if you will pay taxes, but when and how much.
Right now, you have an opportunity to do some prudent tax planning. Tax rates are at historic lows, and you still have time to plan. Most importantly, you have the ability to decide what happens next, which might not always be the case.
So what's your plan?
Are you going to wait and hope the tax code works in your favor? Are you going to let the IRS determine how much of your wealth stays with you and how much goes to them? Or are you going to take control of your financial future while you still can?
Here is what we know. Tax rates are expected to rise in the coming years. Required Minimum Distributions could force you to withdraw more than you need, potentially pushing you into a higher tax bracket. If you plan to pass on wealth, your heirs could face a significant tax burden unless you make a plan.
Medicare premiums and Social Security taxes can increase unexpectedly, but with the right strategy, you can avoid these unnecessary costs. And if you are planning to move to a state with lower or no income tax, the timing of your Roth conversion could save you thousands of dollars.
That sounds like a lot. But here's the good news.
You do not have to figure this out on your own. You have time to plan. You have the ability to make smart decisions today that will give you more financial freedom in the future. Most importantly, you have options.
That is why I am here. Let's run the numbers, talk through your options, and build a strategy that works for you. The best time to plan for your future is today.
If you are ready to take the next step, schedule a call and let's get started.

How to Prepare for Annual Tax Planning
This video provides a concise exploration of the three essential steps in year-end tax planning: evaluating taxable events, estimating your tax liability, and adjusting your withholdings or making estimated tax payments. These strategies are designed to help you avoid surprises and optimize your financial outcomes as the year concludes.
Key Benefits:
- Time Efficiency: Quick and effective ways to review your tax status.
- Accuracy in Tax Payments: Ensures you only pay what you owe, nothing more.
- Avoidance of Penalties: Helps you stay compliant and avoid potential penalties from underpayment.
- Financial Optimization: Identifies opportunities for tax savings and financial betterment.
Next Steps:
- Evaluate Taxable Events: Review major transactions and any new tax law changes.
- Estimate Tax Liability: Use previous tax rates and current year's income to estimate your liability.
- Adjust Withholding/Make Estimated Payments: Update your withholdings or make payments to cover any shortfall.
FAQs
Q: What types of income changes should I report for year-end tax planning?
A: Report any major increases or decreases in income, such as bonuses or changes in investment earnings.
Q: How can changes in tax laws affect my planning?
A: Tax laws can alter the amount of taxes you owe; staying updated can help you leverage benefits or mitigate losses.
Q: What if I find out I’ve underpaid my taxes?
A: Consider adjusting your withholding or making estimated tax payments to cover the difference and avoid penalties.
Schedule a Consultation
Ready to Optimize Your Tax Strategy? Let’s personalize your plan.
We’re here to help you navigate the complexities of tax planning with bespoke solutions that not only meet but exceed your financial expectations.
Tax Mistakes are Costly, Precision is Priceless
Making mistakes on your tax returns can cost you big time.
According to the IRS, nearly 17 million mathematical mistakes were made on tax returns filed in 2022.
And these errors not only involved not paying enough money to the government, it also involved leaving money on the table.
That's because, last year, the IRS made a last call to 1.5 million tax filers who were collectively owed $1.5 billion in refunds that they had yet to claim.
Could you imagine your name being on that list?
One year, I was working with a client who had surrendered an insurance product that no longer suited their lifestyle needs. It was one of those situations where the insurance agent was looking out more for their bottom line than they were for my client's best interest.
Nevertheless, my client got most of their money back from the insurance company. And when the tax documents came in the mail, in this case, a 1099-R, the taxable amount reported on their form was wrong.
Now, it wasn't just wrong. The cost basis was reported as zero, meaning that my client was on the hook for tens of thousands of dollars in taxes due to this one reporting mistake.
Fortunately, we got on the phone with the insurance company, and after some back-and-forth over a couple of weeks, we were able to sort out the situation, and my client had no reported tax liability in this situation.
But could you imagine being in that position?
Knowing that this insurance company already cost you in lost opportunities, and now you're potentially on the hook for a big tax bill?
I know my heart nearly stopped when I realized the consequences of that tax document.
But that episode drilled home the lesson that tax mistakes are costly, but precision is priceless.
That's because haphazardly filing your tax returns can result in financial and personal setbacks, especially when you're not paying attention.
Therefore, you should slow down and check for tax document irregularities, reporting omissions, and preparation errors as we approach the April 15 deadline.
The Costs of Rushed Tax Returns
Now, the truth is that many of us hate paying taxes.
And if you're one of them, you're in good company.
Indeed, according to a recent Gallup poll, nearly two-thirds of Americans surveyed believe that taxes are too high.
This natural repulsion to taxes can naturally leave any of us with a desire to put off completing our returns for as long as possible, especially when we know we're going to owe money, right?
Well, here's the reality of the matter: when it comes to taxes, the only person watching out for you, other than your advisor, is you.
Indeed, rushing through your returns this year can cost you money, peace of mind, and, ultimately, your self-confidence in achieving your financial goals.
And chances are good that when you owe money, the IRS will be quick to send a letter to your home or office.
But, when you're owed money, you can be sure that Uncle Sam won't let you know until you take the time to find out.
Financial Costs
Now, like I mentioned earlier, there's a financial cost for missing reporting errors that lead to you paying too much in taxes.
But there are also life-changing costs to not staying on top of your taxes that can have a profound life impact if you're not careful.
And, this is exactly what happened to Willie Nelson.
Now, as you'll likely recall, Willie Nelson was a renowned country musician who hit it big in the 1970's and 80's. And chances are, you've likely heard one of his songs like "On the Road Again," or "Always on My Mind."
And so, Nelson went on to make millions of dollars, but his run-in with the IRS is a classic tale of how a series of tax mistakes can lead to massive repercussions.
That's because, after a successful career, Nelson was hit with a whopping $32 million tax bill due to mismanaged funds and tax avoidance strategies gone awry.
In fact, the IRS ended up seizing some of Nelson's assets, but ultimately, to settle his debts, Nelson released an album called, "The IRS Tapes."
Fortunately, Nelson was able to pull himself out of his financial hole and eventually settle the issue with the government.
However, the ordeal taught him (and us) a truly valuable lesson: and that's that tax mistakes are costly, but precision—in finances and life—is priceless.
It's a stark reminder of the importance of keeping a keen eye on our financial obligations.
The Cost of Peace of Mind
Now, rushing to file your taxes can not only cost you money, it can also cost you peace of mind.
It reminds me of this one time that our family took a last-minute road trip.
Now, we didn't have any special destination in mind.
What it came down to was that we had some extra time on our hands, and we were in the mood for a short trip away from home.
Well, given the short notice, we rushed to pack our bags, and hurried to head off on our journey.
We were in a hurry to make the most of an otherwise long weekend.
But wouldn't you know it, there was something inside of me that said that I missed something.
Have you ever had that feeling? Like you moved so quickly on something that you have this feeling in the pit of your gut that something you forgot could cost you?
Well, I knew I should have checked the garage door.
And you know what happened? I ended up spending the first half of our trip worrying about whether I had closed the garage door, and it completely distracted me from our family time together.
That's why, when we're not precise with how you approach your returns, you might be haunted by questions like "Did I miss something?" or "Will everything be okay?"
This happens because you're anxious about the possibility of making mistakes and the consequences that could follow.
Tax mistakes are costly, but precision is priceless.
The Cost of Self-Assurance
And finally, while rushing through your taxes can cost you money and peace of mind, but the other thing that rushing does is that it can also cost you in terms of your self-assurance.
Now, I know that I sometimes confuse self-confidence with self-assurance.
So what's the difference?
Well, self-confidence is when you believe you can do things well, like solving a math problem or playing a sport.
It's about knowing you're good at certain things.
Self-assurance, on the other hand, is feeling good about yourself, even if you're not the best at everything.
It means you're okay with who you are, no matter what happens.
And so, if you've been working to get your financial house in order, have made positive progress after a long-stretch of chaos and suddenly find yourself with a letter from the IRS and a potential tax bill, your self-assurance could take a hit.
You can start doubting yourself and saying things like, "after all of this work, I should have just reviewed my return one last time."
To be sure, not being precise about your taxes can really shake your confidence, especially if you've been working hard to get your finances in order.
Indeed, imagine finally feeling like you've got everything under control, only to get hit with a surprise tax bill or audit because of mistakes on your tax return.
It's like taking a big step backward just when you thought you were moving forward.
This can make you doubt your progress and abilities, turning what was a source of pride, and that's prudently dealing with your money, into a source of stress.
That's why mistakes are costly, but precision is priceless.
How to File a Precise Return
So then, what can you do to ensure you're not rushing through your returns, paying Uncle Sam no more than necessary and not leaving money on the table?
Step #1: Review Your Tax Documents
Well, you can start by reviewing your tax documents.
It's crucial to check your tax documents, especially for things like accurate cost-basis reporting on 1099s.
That's because reporting institutions make costly errors more often than you think.
And so, if the numbers are wrong, you might pay too much tax.
That's why, as you go about your review process, ask yourself, "do my tax documents accurately reflect my current financial situation?"
Here what you'll want to do is consider any life changes or events over the past year, such as 401k transfers, annuity surrenders, or IRA withdrawals from various financial accounts.
And if you do find errors, make sure to proactively request a corrected 1099 when necessary because no one will tell you otherwise.
Step #2: Report All Your Income
The next thing you'll want to do is ensure that you've reported all your income.
Now, we've all let a small dividend income payment slide here or there.
But this step isn't just about paying your fair share. Indeed, not reporting all your income could lead to an IRS audit.
That's because the IRS checks income reported against information from employers and banks.
And this is especially the case if you have crypto income.
So then, audits mean more scrutiny and potential penalties.
That's why you'll want to ask yourself, "Have I received all tax documents necessary to report my income accurately?"
Take the time to review your W2s, K1s, and 1099s to ensure that you've received all required documents from reporters.
And follow up with your financial institution's website and download what you haven't received.
Step #3: Review your tax return before submitting.
And last, but certainly not least, you'll want to review your tax documents one last time before clicking that button to eSign your returns.
Now, even when a tax pro helps with your return, it's crucial to note that they can make mistakes because they're busy and are human, too.
That's why it's smart to check your taxes yourself before signing them.
This approach will help you catch any mistakes and potentially save you time and money later on down the road.
Here, what you'll want to do as you review your return is ask yourself, "Does my return reflect all events that have transpired in my life last year?"
If your money situation has mostly stayed the same, but your taxes look very different, then you may want to get another set of eyes on your return to ensure that everything is in order.
Tax Mistakes are Costly, Precision is Priceless
Either way, use these last few days to carefully evaluate the various components of your return to ensure you're setting yourself up for success.
And if you're worried about the April 15 deadline and unsure about anything in your return, file an extension.
No, filing an extension will not make you a target for an audit.
And it will actually help you avoid common mistakes that could lead to an audit down the road.
Either way, take some time to review your tax documents, income sources, and finalized tax return before clicking submit on your return.
Sure, you might just take your chances this time around.
But what could you do with an extra thousand dollars?
Maybe you're not anticipating a refund this year, but you could save yourself thousands in taxes if you had a major life change that involved your finances and a reporting institution made a mistake.
The point here is that it's worth taking a look.
Because ultimately, being a little more precise with your taxes could help give you peace of mind, preserve your self-assurance and take you one step closer to becoming the master of your financial independence journey.
Boost Your Wealth: Become a Tax-Efficient Investor
"Taxes are the price we pay for a civilized society."
This often repeated quote is carved into the entrance of the IRS's national headquarters building in Washington, D.C.
And it serves as a reminder that we all need to pay our fair share to maintain one of the highest standards of living in the world.
At the same time, however, growing your family's wealth from one generation to the next involves paying less in taxes, right?
So then, how do you balance these two seemingly competing ideas of paying your fair share and keeping more of your money?
Well, that's where being tax-efficient, especially when it comes to your investments, comes into play.
You see, while investing wisely is certainly crucial to building wealth, ensuring that you're not paying Uncle Sam any more than necessary is even more vital to this end.
That's because, when it comes to building wealth for the long term, the goal is to put as much money to work today while keeping more of what you earn down the road.
In fact, you can think of being tax-efficient with your investments, like planning for a long road trip.
In other words, just as you would carefully plan out your route to avoid costly tolls and commuter traffic, you also need to think strategically about taxes when it comes to your investment strategy.
And so, while being tax-efficient sounds complicated, the principles are relatively straightforward in that you put more money to work sooner rather than later, utilize investments that minimize how often you need to pay taxes and put your investments to work in the right savings buckets.
It's that simple.
Indeed, by focusing on becoming a tax-efficient investor, you could grow your savings faster, keep more of your hard-earned money, and increase your ability to maintain a lifestyle that supports your family for decades to come.
Making Tax-Efficient Contributions
Alright, so when it comes to becoming a tax-efficient investor, one of the first things you'll want to focus on is when you're actually putting your money to work.
Now, we're not talking about timing the markets.
In fact, what we're getting at here is understanding some of the more basic steps before even thinking about security selection.
More specifically, we're talking about where you put your money to work before Uncle Sam receives his share of your income.
And why does this matter?
Well, the reason is simple: the more money you can put to work today, the more wealth you'll have available to compound for the future.
For example, if you put $1,000 into an investment account each month on a pre-tax basis, and let it compound at 6% for 30 years, you'd likely end up with a million dollars when it's all said and done.
So far, so good, right?
But, what happens when Uncle Sam gets his share of your income before you start investing?
Well, assuming an effective tax rate of 25%, you'll only be able to put away $750 per month from your take-home pay.
And at the end of 30 years, you'll likely have a shortfall of a quarter-million dollars compared to putting your money to work on a pre-tax basis.
Now, the big takeaway here is that the less you get taxed when it comes to taking money out of your paycheck, obviously the more you can keep and compound for your and your family's future use.
And one way to avoid this outcome when it comes to tax-efficient investing is to put your money to work in a tax-advantaged account.
Understanding Tax-Advantaged Accounts
And so, what is a tax-advantaged account?
Well, here we're talking about accounts like 401ks where your money goes into the account before you see it on payday, and grows tax-free until you take the money out at retirement.
Health savings accounts, or HSAs, also offer tax-advantaged benefits and even allow you to take out your gains tax-free to pay for qualifying medical expenses either now or in the future.
There are also other tax-advantaged accounts that allow you to use your take-home pay to save money and not be taxed on the gains later on.
Here, we're talking about accounts like Roth IRAs and 529 plans, where your gains grow tax-free and, when the time is right, come out tax-free when you're ready to use them.
Either way, what you need to know is that tax-advantaged accounts are where your investments are held, and putting money into these accounts can help grow your savings faster over the long term.
Strategic Contributions
Now, when it comes to putting your money into these accounts, it's essential to maximize your contributions strategically.
Indeed, rather than spreading money across each available option, you'll likely want to think about how you can use these tools to meet your long-term financial goals.
How so?
Well, if retirement planning is your key concern at the moment, then maxing out your 401(k) contributions could be your go-to strategy, especially when you're aiming for a retirement that's as rich in experiences as it is in financial freedom.
And if saving for your children's education is your main focus, then putting your money to work in a 529 plan can be akin to planting seeds for a forest of knowledge that they'll one day explore, ensuring their educational journey is well-funded and aligned with their goals for their future.
Impact on Long-term Wealth Building
Either way, as you think about where and when to optimally put your money to work, you'll also want to take the time to focus more on your strategy than the tactics.
Indeed, while investing in a tax-advantaged way is clearly advantageous, it's not always beneficial.
That's because, in some situations, you'll want to keep money in a taxable investment account to address current and future lifestyle needs, and that's a point that we'll discuss in just a moment.
But for now, it's crucial to know that you can make a huge leap forward in being a tax-efficient investor simply by electing to put your money into a tax-advantaged account as your first investment decision.
Identifying Tax-Efficient Investments
Alright, so we've talked about how essential it is to put your money to work in the right accounts so they can grow tax-free.
The next thing you'll want to do when it comes to becoming a tax-efficient investor is to get to know your tax-efficient investment options.
Now, this step can get a little tricky.
That's because it's one thing to pick an investment option that's trading at a good price and aligns with your values.
And, it's another thing to understand the potential tax consequences of choosing one security over another.
Indeed, this approach is a delicate balance that requires a discerning eye and a strategic approach to ensure your portfolio is as tax-efficient as it is impactful for the long term.
Types of Tax-Efficient Investment Vehicles & Securities
Now, before we go any further, we need to make a distinction between terminology here, because otherwise, there's a good chance that we'll get lost in the weeds.
Investment Account
So then, let's start with an investment account. Now, as we mentioned earlier, an investment account is where your savings are stored.
Whether this is your employer-sponsored 401k, or a brokerage account you have at Schwab or Fidelity, this account is the base from which you'll do all of your investing.
Investment Security
Next, we have investment securities.
Now, an investment security represents your ownership interest in a company if you're buying stocks, or a promise that a company is making to you to pay its debt if you're buying fixed-income securities like bonds.
This is the essence of investing.
Pooled Investment Vehicles
And finally, you've got these investment vehicles like mutual funds and ETFs, where, instead of buying one stock or bond at a time, you buy into a pooled vehicle.
And what is a pooled vehicle?
Well, what happens here is that, instead of you taking the time to pick an ideal stock or bond, you give your money to a professional money manager who, you guessed it, pools your money with the money of other investors, and buys a collection of investments.
Tradeoffs: Securities vs. Vehicles
So then, when it comes to being a tax-efficient investor, it not only matters when you're setting money aside or what type of account you choose to put your money in, but also the kinds of investments that you're selecting to go into those accounts when it's time to put your money to work.
How so?
Well, when it comes to pooled vehicles, you typically have the choice between mutual funds and exchange-traded funds, or ETFs.
And while mutual funds have their advantages, more often than not, ETFs are known for their lower turnover rates, which translates into fewer taxable events, aligning ideally with your goal of minimizing your tax impact while staying invested in the market.
And tax-efficient securities, like municipal bonds, offer tax-free interest income, making them a stellar choice for someone in a high tax bracket looking to generate income without increasing their tax liability.
At the same time, investing in munis could mean supporting public projects that resonate with your community engagement values while enjoying tax-free income.
On the other hand, if technology and innovation is where your interests lie, then tech-focused ETFs could offer you exposure to this sector with the added benefit of tax efficiency compared to a mutual fund where expenses and capital gains could be a concern.
Ultimately, however, the tax efficiency of these vehicles and securities comes down to how they return money to their investors.
We'll talk more about putting the right securities in the right savings buckets in just a moment, but the key takeaway here is that the right investment options are designed to minimize taxable events, like producing dividends and interest, realizing capital gains, or doing so in an advantageous way.
Utilizing Appropriate Asset Location Strategies
Alright, so now that we've talked about why it's essential to put your money to work before Uncle Sam gets his hands on it, and the importance of choosing the right investment options, let's talk about putting the right investment options in the right savings buckets.
In other words, what we're talking about here is dialing in your asset location strategy.
Now, some individuals confuse asset location with asset allocation.
And this is an honest mistake, but there's a clear distinction here.
Indeed, as you'll likely recall, asset allocation refers to your decision to put your money to work between stocks, bonds, U.S. and international assets.
And how does this differ from asset location?
Well, instead of deciding between securities, asset location is more about the decision to put those same assets in the right buckets, whether that's a tax-advantaged, or taxable account, to ensure you're paying Uncle Sam no more than necessary and to optimize your after-tax investment returns.
In a way, it's like a strategic game of chess where each piece, or asset, is positioned to leverage its strengths fully, enhancing your portfolio's overall tax efficiency and, by extension, the long-term growth potential of your investments.
Asset Location vs. Asset Allocation
To be sure, when it comes to becoming a tax-efficient investor, it's crucial to appreciate that a lot of individuals get tripped up when it comes to understanding the distinction between asset location and asset allocation.
This distinction is so crucial that it's worth repeating.
Indeed, here again, while asset allocation refers to how you diversify your investments across various asset classes, asset location zeroes in on the type of account each of these assets are held in.
So then, the goal with asset location is to match investments with the account type that minimizes your overall tax footprint.
For example, placing high-growth investments in tax-deferred accounts like 401ks or IRAs can allow those investments to grow unfettered by taxes until you actually take them when you're no longer working.
Now, this is essential because when you stop working, and have a low or no income, you're likely to be in a lower marginal tax bracket when you start taking money out of your investment account and, hence, subject to a lower tax rate in retirement.
And so, how does this work?
Well, consider the case of interest-generating assets like bonds. Holding them in tax-advantaged accounts shields their interest payments from immediate taxation, preserving more capital to compound over time.
On the other hand, placing assets with a lower tax footprint, such as stocks held for the long term, in taxable accounts takes advantage of lower capital gains.
Strategies for Tax-Inefficient Securities
Now, the key to an effective asset location strategy is understanding the tax implications of each type of investment.
That's because tax-inefficient securities, such as REITs or certain actively managed mutual funds, can generate significant taxable income, making them prime candidates for placement in tax-deferred or tax-exempt accounts.
And so, this strategic placement ensures that the tax burden these investments might otherwise generate is minimized, preserving more of your wealth for future growth and an eventual distribution according to your legacy plans.
And so, how might this work for you?
Well, imagine that you're an investor passionate about the ever-changing trends in the tech industry.
Now, if such a scenario is calling to you, then you might choose to invest in a tech-focused, actively managed fund which is likely to come with high turnover and short-term capital gains.
Therefore, placing this fund in an IRA instead of a taxable account could shield those gains from immediate taxation and align them with your goal of maximizing investment growth while managing taxes efficiently.
Tailoring Strategies to Individual Needs
Now, as we mentioned earlier, the effectiveness of asset location strategies hinges on their alignment with your individual financial situation, goals, and broader wealth management strategy.
Indeed, it requires a nuanced understanding of your financial situation, such as your income, tax bracket, investment horizon, and retirement plans, as well as what's essential to you and the legacy that you're trying to build for your family.
For example, if "work optional" is part of your family's financial vision, then you might balance contributions to taxable investments with making it a priority to place growth-oriented investments in Roth accounts, where withdrawals can be taken out tax-free in retirement and help you support a lifestyle that values experiences over material wealth.
On the other hand, if philanthropy is going to be a cornerstone of your legacy, then considering how charitable giving can be optimized through strategic asset location, like donating appreciated securities from taxable accounts, can enhance your philanthropic impact while delivering enhanced after-tax returns.
Either way, employing an appropriate asset location strategy is a sophisticated approach that not only seeks to minimize your tax liability but also amplifies the potential for growing your wealth while making an impact.
Boost Your Wealth: Become a Tax-Efficient Investor
You know, when it comes down to it, becoming a tax-efficient investor is like charting a course through uncharted waters, where each decision influences not only the journey you're on now but the legacy you leave behind in the future.
That's why, by embracing the strategies we covered here today, from making tax-efficient contributions from the start, to selecting the right investment options and putting them in their ideal buckets, you're not just investing wisely, you're sculpting a future that echoes your values and is fueled by the generational wealth you're building today.
Remember, tax-efficient investing isn't just about growing your wealth but doing so in a way that aligns with your vision for your family, your commitment to societal contributions, and, ultimately, becoming the master of your own financial independence journey.
From Complexity to Clarity: Tax Tips for the Tech-Savvy and Wealthy
Tax season is now well underway, and most returns are due by April 15.
Are you ready?
Well, if you struggle with getting your returns filed, or simply don't know where to start, then we've got you covered this year.
That's because the secret to a stress-free tax season involves staying organized before you sit down to prepare your returns and by starting sooner rather than later.
Indeed, when you avoid the last-minute scramble to hunt down all of your necessary tax documents, and then ensure that you have enough time to carefully complete your return, you not only avoid racing against the clock and making mistakes along the way, but what you're doing is ensuring that you're filing a more accurate return that can help you avoid running afoul of the auditors.
That's why, while it seems like the tax deadline is still weeks away, you can still nevertheless get started preparing you returns by assessing life changes over the past year, gathering your documents in a centralized location, and determining the ideal way to file your returns this year.
Taking this approach will not only ensure that your taxes get filed on time, but it will also give you peace of mind, knowing that you've left no stone unturned when it comes to potential tax opportunities in the year ahead.
Get a Handle on All of Your Life Changes
Alright, so one of the first things you'll want to do as you prepare this tax season is to evaluate what's changed in your life over the past year.
Now, these changes can range from personal milestones to professional transitions and either benefit or hinder your financial situation, which underscores the importance of being proactive with your data gathering this year.
Indeed, the fact is that life events like getting married, divorced, the birth of a child, or even a loss in the family can dramatically alter your tax obligations.
How so?
Well, to start, if you've experienced changes in your family over this past year, like getting married, divorced, or the birth of a child, these changes will significantly influence your tax situation.
For example, getting married may allow you to file jointly, potentially leading to tax benefits you didn’t have when you were single, while a divorce could alter your filing status and subsequent tax liabilities.
At the same time, the addition of a child not only brings joy to your household, it also brings benefits like the Child Tax Credit, which can reduce your overall tax bill.
On the professional front, a promotion or significant salary increase might shift you into a higher tax bracket and require a more nuanced tax planning approach.
And, if you've started, bought, or sold a business in the last year, then these actions could come with their own set of unique tax implications.
At the same time, any changes in your investment portfolio, including the sale or purchase of stocks, real estate transactions, or receiving dividends and interest, will affect your capital gains tax.
That’s because each investment decision carries its own tax implications, and necessitates careful consideration in your tax planning.
Indeed, for you tech workers out there, if you've received any form of equity compensation, such as stock options or restricted stock units, these forms of compensation also require special attention because the timing of when you exercise stock options or whether you choose to sell vested stock can significantly impact your tax liabilities.
And finally, if you're planning for retirement or have made significant rollovers or Roth conversions, then these actions can impact your current and future tax situation depending on when and how much you've contributed, so you'll want to pay extra careful attention to these changes.
Getting Organized
So then, what can you do to ensure that you've accounted for all key changes in the past year?
Well, you can start with the basics and consider any significant events mentioned above, such as a change in employment, buying or selling property, marriage, divorce, or having a child.
Here again, these events can have notable tax implications, so then whatever key event in your life that happened, no matter how big or small, you'll want to document and make note of that change just in case.
Now, if you're working with a tax professional, then they'll likely provide you with a tax organizer to get a handle on all of these changes.
And what is a tax organizer?
Well, a tax organizer is a comprehensive tool that helps you gather and organize, you guessed it, tax documents and other pertinent information required to prepare your return.
Now, this tool is often useful because it often includes sections where you can record different types of income, deductions, credits, and any life changes that might affect your tax situation.
So then, by completely filling out a tax organizer, what you're doing is providing your tax professional with a clear and concise overview of your financial year. And this detailed compilation of information can help you and you preparer identify all possible deductions and credits and ensure that your tax return is both accurate and optimized for your financial situation.
Now, this is just a small example of the potential life changes that can have an impact on your overall tax situation and how to keep track of them.
The big takeaway here is that your tax situation is not static because it evolves with your life changes.
So then, just because you filed a certain way last year does not necessarily mean that you'll use the same approach in the year ahead.
That's why staying informed, seeking professional advice, and planning ahead are key to ensuring that these life changes work to your benefit rather than becoming unforeseen challenges.
Do the Work to Get Your Information Organized
Alright, so once you've got a handle on all of the changes that have taken place in the past year, the next thing you'll want to do is to stay on top of the tax documents that are likely now pouring in.
Indeed, staying organized and keeping track of all your tax documents early in the filing season is especially crucial when the stakes are high and your financial situation is complex.
How so?
Well, depending on the complexity of your financial situation, which can include multiple income streams, investments, and perhaps varying business interests, having all your documents in order, early on in the tax season, ensures that no detail is overlooked.
Indeed, taking this meticulous approach is crucial to avoiding errors that could lead to audits or missed opportunities for tax savings.
At the same time, getting organized sooner rather than later enables more effective tax planning.
That's because, with a clear and comprehensive view of your financial situation, you can better identify strategies to minimize your tax liability.
How so?
Well, such strategies might include timing the sale of investments to manage capital gains, making the most of deductions and credits, or optimizing charitable contributions in the year ahead.
So then, even a little bit of early preparation can give you the time to consider effective tax strategies thoroughly and implement them effectively.
And ultimately, time is often a scarce resource.
So then, by organizing your tax documents early, you reduce the last-minute rush to meet the filing deadline, freeing up valuable time to focus on your professional and personal life. This efficiency not only lessens stress but also ensures that tax filing does not become a disruptive burden.
Getting and Staying Organized
And so, what are some ways to keep yourself organized in the weeks ahead as you prepare to file your returns?
Well, to start, consider identifying and using a secure document vault. Now, a document vault is typically an online platform where you can safely store and access all your important tax documents.
This approach not only offers a high-level of security to protect your sensitive information but also provides the convenience of having all your documents in one place and is accessible from anywhere where you might be.
This approach is especially helpful when it integrates with your wealth advisor or accountants' systems because it further enhances efficiency and collaboration in your tax preparation and planning process.
Once your digital vault is established, the next thing you'll want to do is to start digitally cataloging your paper tax documents.
Now, you might find yourself in a situation where you have a mix of digital and paper records and are not sure what the best approach may be to keep track of it all.
So what do you do?
Well, the fact is that most tax professionals are moving toward a simplified digital format for documenting and filing. And so, taking a similar approach can help you stay in line with the trends.
So then, the simplest thing you can do is to use a scanning app on your smartphone to convert paper receipts, tax forms, and other documents into digital files. Then, categorize these files in your secure document vault using a consistent naming convention for easy retrieval when you're ready to file your returns.
Finally, try to develop a practice of setting regular intervals, perhaps monthly or quarterly, to review and update your tax document vault. Doing so not only ensures that everything is up-to-date but also helps you stay familiar with your financial situation, making it easier to identify potential tax-saving opportunities as you approach the year's tax filing deadline.
Knowing When to Hire Out the Work
Alright, so we've talked about evaluating life changes and staying organized by getting digital with your documents. The last thing that we'll cover here when it comes to ensuring a stress-free tax season is knowing when to hire someone to do your taxes and knowing when to do it on your own.
Now, if you’ve been comfortably filing your tax filings on your own for years, the decision to continue this practice or to fork out some extra money and hire a tax professional carries both advantages and disadvantages.
On the one hand, managing your own tax filings has likely given you a strong sense of control and a deep understanding of your financial situation. That's because this hands-on approach can be empowering and offer you direct insight into the nuances of your current tax situation.
And while doing your own taxes can save you money, as your wealth and financial situation becomes more complex, the limitations of this approach can become more apparent and even work against you.
That's because the intricacy of tax laws, especially for high-income individuals with diverse income streams, investments, and potential business interests, can be daunting. And so, the risk of overlooking a key deduction or making errors with your returns increases, and these mistakes can be costly, both in terms of potential penalties and missed opportunities for tax savings.
That's why hiring a professional, like an enrolled agent, certified public accountant, or a tax attorney, brings with it its own set of advantages.
How so?
Well, in many cases a tax professional can offer a unique expertise and perspective in a given practice areas, and because they're staying up-to-date on changes in tax laws, their approach ensures that your tax filings are not only compliant but optimized for your unique tax situation.
At the same time, delegating this responsibility to a professional can free up your time, and allow you to focus on your professional and personal life. And given your busy schedule and the value you place on family time and personal pursuits, this can be a significant benefit in and of itself.
The downside, of course, is the cost. Professional tax services, especially those equipped to handle complex situations, like knowledge about equity compensation or complex business filings, come at a price.
Even so, the value that you receive from these professionals can often come from the tangible dollars in taxes saved to the intangible value of knowing that you have someone in your corner to watch your back.
Knowing When It's Time to Hire a Professional
So then, if you're interested in hiring a tax professional, where should you start?
Well, the first thing you'll likely want to do is to start by assessing the complexity of your financial situation.
You can do this by reviewing your current financial situation and the changes you've noted throughout the year.
And if you find that the complexity of our household has increased significantly over the years as a result of personal or professional life changes, and you're spending an excessive amount of time trying to navigate these complexities, then that in and of itself might be an indicator that professional help could be something worth looking into.
Another thing to consider is the value of your time.
That’s because, as a high-earning individual with a busy lifestyle, you know that your time is valuable. That's why one thing you can do to evaluate the cost-benefit of hiring a professional is to calculate the time you spend on tax preparation and consider if this time could be better spent on your personal development or time with your family.
Finally, think about your long-term financial goals and how bringing in a tax professional could help maximize these outcomes.
Either way, your decision to hire a professional should be based on a comprehensive understanding of your current financial situation, changes in your life, understanding of tax laws, and past tax filing experiences.
If, after some reflection, you find that the scales are tipping towards needing professional help, then it would likely be a good idea to seek out a trusted tax advisor who can provide the expertise and guidance you need.
Kicking Off Tax Season: A Wealth Builder's Guide to Stress-Free Planning
You know, when it comes down to it, tax season can feel overwhelming, but it doesn't have to be.
Indeed, as we stand at the threshold of another tax season, with the April 15 deadline not too far off in the future, being proactive now can make the difference between a stressful and stress-free tax return season.
Indeed, by assessing your life changes over the past year and organizing your documents early, you'll likely feel more confident and less overwhelmed.
And by avoiding the last-minute rush to gather all your necessary tax documents and ensuring you have enough time to carefully complete your return, you're doing more than just beating the clock because you're filing a more accurate return, which is crucial not just for peace of mind but also for staying clear of auditors' scrutiny.
So then, as tax season kicks into full gear, remember that the sense of urgency you might feel as the deadline approaches can be mitigated with a bit of proactive planning.
Indeed, by following these steps and starting your tax preparations now, you're not just ensuring that your taxes get filed on time, you're taking one step closer to becoming the master of your own financial independence journey.
Tax Changes in 2024: What to Expect
Each New Year brings with it some form of change, especially when it comes to taxes.
But let's face it: with so much going on at the start of the year, who has time to keep up with all the tax changes, right?
Well, fortunately, I’ve been keeping an eye on some of the tax developments coming down the pike this year, so you don't have to.
And what did I find?
Well, beyond the usual inflation adjustments to tax brackets, deductions, and contribution limits, there are few material changes to note in 2024.
Even so, constant gridlock over a seemingly never-ending budget deal on Capitol Hill, coupled with general elections later on in the year, could likely complicate Federal returns once again.
And while we don't anticipate any meaningful tax legislation to pass in the current election cycle, certain portions of tax law are scheduled to sunset in the next couple of years, likely leading to higher taxes for many households.
So then, the big takeaway here is that while there are few legislative changes to worry about this year, there are still a few steps to consider today so you can take full advantage of tax changes now and into the future.
Check Your Opportunities for the Year
Alright, so as it concerns the 2024 calendar year, what are some of the changes that we should all be paying attention to when it comes to our taxes?
Well, to start, consider the annual indexing for inflation.
Now, as you know, the IRS annually makes adjustments to tax brackets, contribution, and deduction limits as a way to keep the tax system fair and relevant in an environment of rising prices.
And this year is no different.
Inflation Adjustments
Now, while we saw some notable cost of living adjustments given the high inflation rates in years past, the same can't be said for the 2024 calendar year.
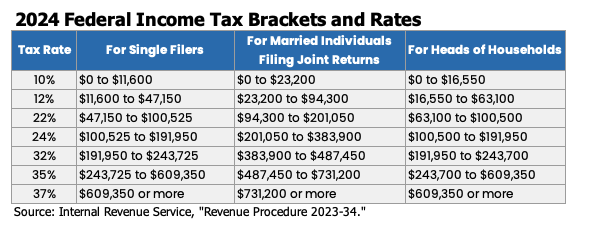
Even so, as far as tax brackets are concerned, while the marginal rates remain the same (10%, 12%, 22%, 24%, 32%, 35%, and 37%), there are still adjustments to the income thresholds that should be considered.
More specifically, for a married couple filing jointly, you can earn up to $383,900 and still remain in the 24% marginal bracket, which is an increase of around $20,000 from 2023.
The standard deduction is also getting an inflation adjustment this year, with married filing jointly households getting to claim $29,200 for 2024, compared to $27,700 in 2023.
Now, come tax time, you'll want to pay close attention to this figure because it will help you determine whether you should itemize or just take the standard deduction.
Either way, it's crucial to note that the 2024 adjustment won't apply until you file your returns in April 2025, so the 2023 figure is still relevant when filing this year's returns.
Adjustments to Retirement Savings
Alright, now shifting gears to retirement savings, the IRS also considers inflation when it comes to putting money away in your employer-sponsored plan or your IRA.
And this year, contribution limits for 401(k) plans and IRAs have increased by about $500.
What this means is that the contribution limits to your 401k rises to $23,000, from $22,500 in 2023.
At the same time, IRA contribution limits have moved up to $7,000 this year, from $6,500 and you still get that $1,000 catch-up contribution if you're over the age of 50.
Either way, these increases allow you to save more for retirement in a tax-advantaged way, which is especially important in an environment of rising prices and household expenses.
Other Adjustments
Now, other tax adjustments worth noting for households in higher tax brackets include changes to the gift tax and AMT exemptions.
More specifically, the basic exclusion amount for the estate tax is now over $13,610,000. Now, keep in mind that this figure applies to taxes on money you leave behind after your pass.
For many individuals, this estate tax will not apply to their situation, and in those cases where it does, there are still legal means to mitigate the potential taxes before you pass away.
Along these same lines, the annual gift tax exclusion applies to the money you give away while you’re still alive and the IRS has updated that giving limit to $18,000, or $36,000 per couple, per recipient in 2024.
And finally, as far as the Alternative Minimum Tax, or AMT is concerned, the phaseout limit has moved higher this year by around $62,400 landing at $1,218,700.
Even if your salary is well below this limit you’ll want to pay close attention, especially if you received stock awards from your employer.
Indeed, this figure is crucial to watch if you plan to exercise stock options this year or anticipate any other big equity awards coming through in 2024 because it could mean paying higher taxes in certain situations.
Nevertheless, this year’s inflation adjustment gives you a little more breathing room when it comes to AMT, but it’s something to watch nonetheless.
How to Prepare
Alright, so now that you know that many inflation-related tax changes are coming down the pike, what can you do to prepare for the year ahead?
Well, you can start by taking some time to get familiar with your income tax brackets.
Remember, the US tax system is progressive.
It's like the government has given you buckets ranging in size to fill as you bring in more income.
And so, each bucket you fill is taxed at a certain rate, starting with the smallest bucket and rising to the largest.
Now, as you earn money throughout the year, you fill the first bucket, then the next and so on.
And so, the tax you pay on each bucket is what we call your “marginal tax bracket.”
So then, with the IRS's inflation adjustments this year, the size of each bucket is bigger this year.
And this is a good thing!
And why's that?
Well, it’s because now you have more room to fill each bucket.
More specifically, this could be an opportune time to consider whether certain financial strategies, like realizing capital gains on a low-cost basis, concentrated stock positions, or converting a traditional IRA to a Roth IRA, could be a tax-efficient move.
Now, as far as the standard deduction is concerned, here again the 2023 rules apply for this year's return. Either way, you'll still want to evaluate whether it makes more sense for you to take the standard deduction or to itemize.
And how do you go about doing this?
Well, you might be better off taking the standard deduction if your itemizable deductions are close to the standard deduction limit.
On the other hand, taking standardized deduction might make less sense than itemizing if you're in a higher tax bracket, have completed a great deal of charitable giving, or have had significant medical expenses.
Now, when it comes to your retirement savings, the higher contribution limits for 401(k) plans and IRAs offer a chance to sock away a modestly higher amount into your qualified accounts in the year ahead.
So then, if your budget allows, consider increasing your contributions to these accounts because doing so can help you build your nest egg faster through pre-tax growth while reducing your taxable income for the year.
And this could potentially lead to some marginal tax savings.
Finally, if you're a W2 employee and anticipate the vesting of your stock awards or changes in your financial situation in 2024, then you may want to consider adjusting your tax withholding for the year ahead or making estimated tax payments.
This approach will allow you to avoid underpayment penalties and deal with the hassle of coming up with cash to pay taxes next year.
Beware Capitol Hill Gridlock
Alright, so as we continue to look ahead to potential tax events into the coming year, another thing to keep an eye on is gridlock on Capitol Hill.
And at this point, you might be thinking to yourself that gridlock is nothing to worry about now, so why should we be concerned at all in the future, right?
Well, that's because when Congress faces delays in passing spending bills or undergoes periods of dysfunction, it can directly affect the IRS's ability to carry out its duties effectively.
And one of the critical issues arising from congressional gridlock is the IRS's struggle with managing a backlog of paperwork, including the processing of tax returns and related documents.
Now, as you'll likely recall, this backlog started becoming more pronounced in 2020 as the pandemic disrupted the IRS's usual operations and was further complicated by budget cuts, a shrinking workforce, and outdated technology that the IRS has been grappling with for years.
As a result of these challenges, taxpayers have experienced significant delays in receiving refunds.
And, at the same time, the IRS has faced challenges in responding to taxpayer letters and phone calls.
So then, another government shutdown could likely throw a wrench into IRS operations for the coming year, assuming that Congress can't settle on a budget deal in the weeks ahead.
At the same time, last year's budget gridlock led to a cash shortfall at Treasury, resulting in the administration's use of extraordinary measures to fund operations, which included delaying refunds for some high earners.
Get Your Taxes in Order
So then, in light of the recent challenges facing the IRS, including delays due to budget constraints and operational issues, it's crucial now more than ever to file your returns promptly and, at the same time, ensure you're not overpaying taxes in the year ahead.
That's why, as tax season kicks off, filing your returns early can save you headaches down the road, especially considering the delays the IRS has experienced in processing returns.
Early filing also means your return enters the queue sooner, potentially leading to an earlier processing of your refund or allowing you to get ahead of any potential review issues that might arise.
So again, that’s why it’s essential to verify that your withholdings are dialed in appropriately to ensure that you're paying no more tax than necessary and to avoid giving Uncle Sam an interest-free loan with your money.
Stay Ahead of Future Tax Changes and Act Now
Alright, so now that you've considered inflation adjustments and Capitol Hill uncertainties, the final point you'll likely want to keep an eye on in the year ahead is potential long-term tax changes taking effect in the next few years.
And one of those changes that you'll want to focus on is the upcoming sunsetting of specific provisions of the Tax Cuts and Jobs Act (TCJA).
Now, as you'll likely recall, the Tax Cuts and Jobs Act was passed by Congress in 2017 and offered sweeping, you guessed it, tax cuts for households and businesses alike.
Now, these benefits included doubling the standard deduction and estate tax exclusion, a bump to child tax credits, and a reduction in the corporate tax rate, among some of the changes introduced.
But, these cuts were supposed to be temporary.
So then, unless Congress acts, some of the provisions of this law are expected to sunset, or go away, starting in 2026.
And so, what does this mean for you?
Preparing for TCJA Sunset
Well, the expiration of these provisions will likely lead to higher tax rates for many individuals, given a decline in the standard deduction, changes in eligibility for certain tax credits, and a reduction in estate and gift tax exemptions.
That's why understanding the impending sunset of the Tax Cuts and Jobs Act should be a crucial component of your financial planning process this year and next.
So then, as this legislation nears its expiration, what can you do to prepare for higher taxes?
Well, there are several strategies you should consider to optimize your tax situation.
First, start by realizing income now, when tax rates might be lower.
You can do this by taking a look at your current income levels and tax brackets and pay attention to opportunities to max out those buckets.
That's because, given the potential for increased tax rates down the road, you may want to accelerate income into the present years, where tax rates are currently lower.
And how do you go about doing this?
Well, this could involve strategies like converting traditional IRAs to Roth IRAs, which means paying taxes now but also avoiding higher taxes and offering tax-free growth and withdrawals later on down the road.
Indeed, with future higher tax rates, contributing to Roth accounts, where you pay taxes now and not later, could be beneficial, depending on your current situation.
Another point to consider when it comes to current and future tax brackets is capital gains.
That's because, if you hold assets that have notably appreciated (like your concentrated employer stock), then it might make sense to realize some of these gains now, under the lower tax rates.
This strategy, known as tax-gain harvesting, can be especially effective if you're currently in a lower tax bracket now and expect it to move higher in the future.
And finally, as you plan for the upcoming year, it's crucial to consider estate planning before the TCJA expires at the end of 2025.
Now, as noted earlier, the TCJA led to a significant, albeit temporary, increase in the federal gift and estate tax exemption. This move offers a rare opportunity to protect a larger portion of your and your family's wealth from future taxes.
Nevertheless, this exemption is set to revert to about $5 million, adjusted for inflation, after 2025.
That's why utilizing estate planning strategies like Dynasty Trusts, Spousal Lifetime Access Trusts (SLATs), and others can help lock in these higher exemption rates.
Preparing for Tax Changes in the Year Ahead
Either way, when it comes down to it, it's clear that change, especially when it comes to taxes, is inevitable in the year ahead.
So then, while the usual inflation adjustments to tax brackets, deductions, and contribution limits appear relatively stable for 2024, the fact is that political gridlock and the upcoming general elections suggest that the federal tax filing process could face a number of hiccups along the way.
And while no major tax legislation is expected to pass ahead of this current election season, it's nevertheless crucial to remember that certain tax laws are scheduled to sunset, potentially leading to higher taxes for some in the near future.
That’s why the key takeaway here is that even though 2024 might not bring many new tax changes, it's still crucial to be proactive about old tax changes going away.
And so, by understanding and planning for these changes now, you can position yourself to make the most of the current and future tax environment, which will ultimately take you one step closer to becoming the master of your own financial independence journey.

How Smart Investors Profit from Tax Loss Harvesting
It's that time of the year again, and apple picking and pumpkin patches not only usher in traditional fall routines, they also signal that it's time for an annual review of potential tax losses you can harvest from your investment portfolio.
And you know, just as farmers come together to bring in the fall harvest before winter kicks in, prudent investors should take the time to review their portfolios for opportunities to harvest tax losses this season.
Now, for some of you out there, the idea of "harvesting" losses might seem counterintuitive.
That's because when we think of harvests, we tend to think of taking gains, not losses, right?
Well, while this point may be relevant in most situations, the truth is that a harvest can also happen when you act to avoid leaving money on the table.
Indeed, the key to growing and preserving your wealth isn't just about how much you make, it's also how much you keep.
That's why, just as farmers harvest their crops to reap the benefits of their sewing efforts, investors "harvest" losses to minimize tax expenses.
And so, by realizing (or "harvesting") losses, you can offset taxable gains elsewhere in your portfolio and avoid paying Uncle Sam any more than his fair share.
With that said, this process isn't just about selling all your losses. Indeed, it involves making sure that you’re harvesting losses in the right accounts, being methodical in your approach, and avoiding common and costly pitfalls that could derail all of your tax-savings efforts.
What is Tax Loss Harvesting?
Alright, so now that you understand that tax loss harvesting is a crucial component of your journey to financial independence, let's talk a little more about what it is.
What is Tax Loss Harvesting
Now, at its core, tax loss harvesting is a sophisticated financial maneuver that allows you to turn the tables on your investment losses. You can think of it as a silver lining to the occasional cloud of a poorly performing investment.
That's because, instead of merely accepting an investment loss when market volatility picks up, you can use it to your advantage.
How so?
Well, imagine for a moment that you've invested in a promising growth sector in the market, but because of some macro or micro concerns, the value of your investment has declined. While this position is undoubtedly disappointing, tax loss harvesting allows you to sell that investment and realize, or "harvest," that loss.
Now, this strategy shines because you can use the loss from this sale to offset capital gains from other investments. And remember, there's no free lunch in the world of investments, so then the profit you make when you sell an investment for more than you paid, which is called a capital gain, comes with a tax liability.
So then, by offsetting these gains with your harvested losses, you can effectively manage and potentially reduce the amount of taxes you owe to the IRS.
So far, so good, right?
Well, good news doesn't stop there.
You see, the added benefit here is that for someone in a high tax bracket, like many of you tech professionals and business owners out there, this strategy can be especially beneficial because the money you save on taxes can be reinvested, allowing your wealth to compound more efficiently over time.
At the same time, if your harvested losses exceed your capital gains in a given year, you can typically use some of your excess losses to reduce your ordinary taxable income.
And if there's still a remaining loss after that? You can carry it forward to offset gains in future years.
What Tax Loss Harvesting Isn't
Now, as we dive deeper into the topic of tax loss harvesting, it's crucial to clear up some common misconceptions about this strategy.
And to start, it's essential to note here that tax loss harvesting isn't a luxury reserved only for the ultra-wealthy.
In fact, while it might seem like a strategy tailored to those with only the biggest portfolios, the truth is that you can harness its benefits to manage your tax liabilities even if your investments are more modest than the typical billionaire.
Another misconception to consider here is the belief that tax loss harvesting offers a permanent tax reduction.
Now, while this process can indeed offset your capital gains in the current year, this approach is more about deferring taxes due to a future date. In other words, you can think of it as a strategic pause that gives you more control over when you'll face certain tax implications.
And finally, there's more to this process than simply the benefit of its tax-saving powers.
To be sure, beyond the tax benefits, tax loss harvesting is a gateway to portfolio rebalancing. And this approach is crucial to your investment strategy because, by offloading certain assets, you're not just optimizing for tax, you're also creating an opportunity to realign your investments with your long-term goals and vision.
And so, don't fall into the trap of thinking of tax loss harvesting as a one-time strategy, or something to be pulled out of the toolbox only during a particularly turbulent market year.
At the end of the day, it's a dynamic approach that can be woven into your annual financial rituals, allowing you to consistently manage and potentially reduce tax liabilities year after year.
To be sure, when you boil it down to its core, tax loss harvesting is about making the best out of a less-than-ideal situation. And, even when the market doesn't move in your favor in a given year, you still have this proactive strategy in place to mitigate the impact of a pullback.
Why Tax Loss Harvesting is a Game-Changer
Alright, so now that we've discussed what tax loss harvesting is and isn't, let's take a few minutes and talk through why you specifically would want to implement this approach in your portfolio.
Optimized Tax Management
Now, as someone who's achieved significant financial success over the years, you're likely no stranger to the hefty tax liabilities that often accompany significant capital gains.
In fact, as your earnings have grown over the years, you've likely looked at your tax bill with resentment and scorn as the government seems to keep an evergrowing share of your hard-earned wealth.
And so, if this is you, then tax loss harvesting might be your secret weapon here.
Indeed, by strategically selling off those investments that haven't performed as expected throughout the year, you can use those losses to offset the gains from the thriving assets in other parts of your investment portfolio.
What's more, in a situation where your losses surpass your gains, you have the added advantage of offsetting up to $3,000 of your ordinary income. Now, this might not seem like much, but every cent counts when it comes to minimizing taxes.
What's more crucial, however, is that this approach offers you flexibility during tax season and could position you in a more favorable tax bracket, ensuring that you're not paying Uncle Sam more than his fair share.
Strategic Financial Planning and Rebalancing
Now, another benefit to consider is that beyond the immediate tax season, tax loss harvesting is your ally for long-term financial prosperity.
To be sure, the ability to carry forward losses means that you're equipped with a tool to mitigate potential tax impacts in the years ahead.
But there's another layer to this strategy that you may want to consider.
For example, when you decide to offload those underperforming assets, you're not just cutting losses. What you're also doing is freeing up capital, that can be reinvested in opportunities that better align with the current market conditions and your financial goals.
A Proactive Approach to Setbacks
And finally, when it comes to reasons why you may want to consider this approach, you can think of it as a reset button to your overall investment strategy.
How so?
Well, think about it for a minute. In your own journey to professional success, you've likely faced challenges and setbacks that have forced you to stop what you're doing and evaluate the choices you're making in life.
In a similar way, the process of tax loss harvesting offers you a fresh perspective on setbacks in your portfolio. Indeed, instead of viewing them as mere losses, you can now see them as strategic levers, ones that can be pulled to optimize your financial outcomes.
And so, knowing that you can use the losses from an investment or trade that has moved against you might be the salve you need to move on from a position that may have never been a good fit in your portfolio, to begin with.
To be sure, this approach doesn't just offer peace of mind, it empowers you. It ensures that even when the market throws you a curveball, that you have a well-thought-out strategy in place which allows you to turn potential challenges into tangible opportunities.
In essence, tax loss harvesting isn't just a financial tool, it's a mindset, or a way for you to continuously adapt, innovate, and thrive in the ever-evolving financial markets around you.
The Mechanics of Tax Loss Harvesting
Alright, so now that we've talked about tax loss harvesting and how you might benefit from this approach in your investment portfolio, let's walk through how you actually go about the process and cover some common pitfalls to avoid along the way.
Spotting the Decline
Now, the initial step in this strategy is like debugging code in a piece of software that you're writing. But in our situation, the work involves meticulously scanning your portfolio, and not for bugs, but for investments that have depreciated in value.
Now, it's essential to remember here again that this process isn't about labeling certain investments as failures. Instead, this approach is about recognizing the inherent volatility of the market and using it to your advantage.
Here again, by identifying assets that have fallen in value, what you're doing is not admitting defeat, but rather, you're positioning yourself to leverage these declines for potential future tax benefits.
Indeed, just like a savvy software engineer might use a software glitch as a learning opportunity, tax loss harvesting allows you to use market downturns as a chance to optimize your tax situation.
So then, as you review your portfolio, remember that spotting the decline isn't about dwelling on what went wrong. It's about forward-thinking, about understanding that in the markets, challenges can be turned into opportunities.
Cashing in on the Downturn
Alright, so now that you've spotted positions in your portfolio that have declined in value, the next move isn't to lament or second-guess your choices.
Instead, it's to cash in on the downturn. Now, as you cash in on this process, there are a few definitions that you'll want to keep in mind.
First, you'll want to take a loss on a position that has fallen in value relative to its cost basis.
And what is cost basis?
Well, simply put, cost basis refers to how much an asset was worth when you legally received it. This could be the value when your restricted stock vested, when you exercised your stock options, or when you initially purchased a security.
Now, another term you’ll want to get familiar with is understanding the difference between short-term or long-term capital-losses in your portfolio.
And what are we talking about here?
Well, when you sell an asset that you've held for one year or less and you get less than what you paid for it, you incur a short-term capital loss.
And to calculate this value, what you do is simply subtract the sale price from the purchase price. If the result is negative, that's your short-term capital loss.
On the other hand, if you sell an asset that you've held for more than one year and the sale price is less than the purchase price, then you have a long-term capital loss.
Again, what you'll do is subtract the sale price from the purchase price to determine the amount of the loss. Here again, if the result is negative, then that's your long-term capital loss.
So then, by selling these assets, what you're doing is taking a proactive step to "realize" the loss.
Now, in the financial lexicon, to "realize" a loss means to officially acknowledge it for tax purposes.
And so, by selling and realizing the loss, what you're doing is essentially turning a paper loss into a tangible tax benefit. Indeed, it's a way to harness the market's inherent volatility, transforming potential setbacks into strategic opportunities.
Staying in the Game
Now, after you've made the decision to sell and realize your losses, it's crucial to remember that the cash now sitting in your account isn't meant to just sit there and gather dust until the markets turn around.
And why's that?
Well, that cash is your ticket to staying in the game.
How so?
Well, imagine that you're at a farmer's market, and there before you are two fruit baskets.
Now, one basket contains apples you bought recently at a higher price, but due to unforeseen circumstances (maybe a sudden influx of apples in the market), the value of your apples has fallen.
And what about the second basket? Well, the other basket is empty, but it represents the potential for new investment opportunities.
Now, let's say that a vendor at the local farmers market offers to buy your apples but at a lower price than you had initially paid. Here, you realize that if you sell now, you'll be realizing a loss.
But here's the twist, right next to this guy who wants to buy your apples is another vendor selling oranges at a rather attractive price, and you believe that the demand for oranges will rise soon.
So then, you decide to sell your apples and take your "loss." With that said, however, instead of walking away with just cash, you immediately buy the oranges and put them in your second basket with the money you received from the apple sale.
Are you still following along?
Ultimately, what you've done here is swapped apples for oranges, and redeploying your capital at a given price level.
And so, what happens next?
Well, a week later, you return to the market and find that the demand for oranges has indeed skyrocketed. So then, you can either hold onto your gains or sell your oranges at a profit that not only covers the loss from your apples but also provides for additional gains.
And, what's the key takeaway here?
Well, the takeaway is that you didn't "lock in" a loss when you sold the apples, but rather you strategically redeployed your capital.
And the truth is that you likely won't be able to make up your investment losses in a week.
However, by focusing on the price level at which you're redeploying rather than the loss you incurred, what you're doing is you're positioning yourself for potential future gains.
Navigating the "Wash Sale" Rule
Now amidst all this repositioning, there are some regulations that you'll want to keep in mind as you consider tax loss harvesting, and that's the IRS's "wash-sale" rule.
And what is the "wash-sale" rule?
Well, let's say that you've just offloaded a stock that hasn't been performing so well.
Now, if this were a software glitch, you'd quickly patch it and move on, right?
Well, when it comes to investing, if you rush to buy a stock that's "substantially identical" to the one you just sold, either 30 days before or 30 days after the sale, then you're potentially running up against the wash-sale.
And why is this rule even here in the first place?
Well, the IRS, in its bid to ensure fair playing field, set up this rule to prevent investors from gaming the system.
Essentially, it stops you from selling a stock to claim a tax loss only to immediately buy it back in anticipation of a rebound.
And why does this matter to you?
Well, understanding the nuances of this rule is crucial to effectively leveraging tax loss harvesting. You see, it's not just about recognizing a loss, it's about strategically navigating the aftermath of that decision.
In fact, if you run afoul of the wash-sale rule, then all those losses that you've so meticulously cashed in on could be considered worthless, leaving your harvest a fruitless one.
So then, what can you do to avoid running afoul of the wash-sale rule?
Well, the first thing you can do after selling a security at a loss is to wait at least 31 days before repurchasing that same security. This will ensure you're outside the 30-day window that the IRS monitors for wash sales.
And if you don't plan on purchasing that same investment or if you're eager to reinvest the proceeds from the sale immediately, then consider investing in a different security that isn't what's considered "substantially identical" to the one you sold.
For example, if you sold a specific company's stock, you might invest in another company within a different sector or in a broad-based index fund. This way, you're still putting your money to work, but without violating the wash-sale rule.
And the last thing to consider here is that you'll likely want to be cautious with automatic investment plans, like Employee Stock Purchase Plans (ESPP) and dividend reinvestment plans (DRIP) during this period.
That's because, if these plans purchase a "substantially identical" security within the 30-day window, it could inadvertently trigger the wash-sale rule.
That's why it might be wise to temporarily halt these automatic purchases or ensure they're directed towards different securities as you go about your tax-loss harvesting this season.
How to Profit from Tax Loss Harvesting
Now, as the leaves turn color and the crispness of fall reminds us of nature's ever-changing cycles, it's essential to remember that seasons aren't the only things that undergo perpetual change.
Indeed, the markets, much like your chosen profession, is in a constant state of flux.
But with change comes opportunity, and just as farmers meticulously tend to their crops, awaiting the right moment to harvest, you too have the power to harness the fluctuations in your investment portfolio.
Remember, tax loss harvesting isn't merely a financial maneuver, but rather, it's about recognizing that in every downturn, there's a hidden path for growth.
So then, as you stand at the beginnings of another seasonal change, remember that the essence of prudent money management isn't just about the gains you make but also about ensuring that with every decision you make when the market twists and turns, you're always one step closer to becoming the master of your financial independence journey.
Plan Your Way into Tax-Free Income
Let’s face it, no one likes paying Uncle Sam more than his fair share. But what if there was a way to take advantage of financial planning techniques to not only grow your savings, but also help protect your family and transfer wealth tax-free?
Sounds too good to be true, right?
Well, it’s more possible than you think. And as a highly driven individual, you likely have multiple streams of income to consider, like your salary, bonuses, stock options, and perhaps even revenue from a side hustle or business.
And with these multiple income streams and your high earnings, you’re likely setting yourself and your family up for an even higher tax liability in the years ahead unless you do something about it today.
That’s where tax planning comes in.
Now, tax planning is essential because it provides a structured approach to minimize the taxes you owe. And without adequate tax planning, you could end up paying more to Uncle Sam than necessary, which reduces the amount of wealth available to you and your family.
To be sure, the financial decisions you make today can have significant tax implications on your future wealth. That’s why understanding how to harness techniques to gain tax-free income can help you avoid paying thousands to the IRS, leave more to your family, and to ultimately make more informed financial decisions.
Understanding Legit Ways to Produce Tax-Free Income
Alright, so, when you hear tax planning you might think to yourself, “isn’t creative tax planning what got Al Capone put away in jail?” Well, the truth is that the US tax code, as complex as it is, has features written into it that gives certain advantages to those individuals with the time and patience to see them through, like sidestepping taxes on income.
To be sure, tax-free income is like a treasure that’s hidden in plain sight. It's income you or your loved ones receive that, as the name suggests, is free from obligation to the IRS. And what this means is that every dollar you receive stays a dollar, without a portion being reduced by what you would otherwise owe to Uncle Sam.
Now, it’s essential to keep in mind that we all earn income under a progressive tax system here in the United States. And what does this mean? Well, a progressive tax system means that the more money you make, the more you will owe Uncle Sam because your tax rate rises, or progresses, with your rising income.
And this rising tax rate doesn’t apply just to your wage income. In fact, in many cases it also applies to your interest and investment income applied towards the substantial savings you’re likely to receive now and into retirement as well. That’s why it’s essential, now more than ever, for you to understand some of the basic techniques of creating tax-free income so you can substantially boost your wealth while legally mitigating your future tax liability.
And, so, what are those techniques?
Well, when it comes to reducing your future tax obligations, there are generally three ways to produce tax-free income for yourself and your family. The first is putting money away in a tax-free investment account. The second option is to purchase securities or insurance products that offer tax-free income now and into the future. And, finally, you can mitigate a significant tax liability through the decisions you make about your home, when you gift money to loved ones and the decisions you make before you pass away.
Tax-Free Investment Accounts: Vehicles to Hold Taxable Investments
Alright, so let’s talk about some ways to use investment accounts to mitigate your tax liability. Now, before diving deep down this rabbit hole, let’s take a moment to make a distinction here between tax-free investment accounts and tax-free investment products.
And why is this important?
Well, it’s important because investment accounts and financial products are in many ways entirely different beasts. For example, tax-free investment accounts, like Roth IRAs, 529 Plans and HSAs act as shelters or holding containers, that allow a range of otherwise taxable investments within them to grow tax-free.
On the other hand, tax-free securities or insurance products like municipal bonds or life insurance, offer tax advantages inherent to the instrument itself, regardless of the account they're housed in. Indeed, another way to think about this is that tax-free accounts shelter holdings from future tax liabilities, while tax-free products inherently sidestep income tax altogether.
Ok, so then with this distinction in mind, let's explore tax-free investment accounts in greater detail.
Roth IRA – Tax-Free Lifestyle Savings
More specifically, let's start with the Roth IRA. Now, a Roth is an individual retirement account and acts like a container that offers specific tax breaks for the otherwise taxable investments you hold inside. And the way it works is that you put money into a Roth IRA using after-tax, take-home dollars.
And now while you don’t get an immediate tax break for your contributions to this account, the magic happens as your investments grow and when you start to withdraw your funds later in retirement. That’s because all the withdrawals, including earnings from the investments, are received tax-free if you meet certain conditions.
529 Plan – Tax-Free Education Savings
Another investment account that allows you to earn tax-free returns is a 529 Plan.
Now you may have heard of a 529 Plan before.
But if you haven’t, a 529 plan is an education savings program designed to encourage you to save for your or your children’s future education costs. Now, these plans operate in much the same way as a Roth IRA, meaning that you fund them with money you've already paid taxes on.
And while there's no federal tax deduction on the front-end for these contributions, the investments still grow tax-free so that when it’s time to use these funds for qualified education expenses, the withdrawals often come out without owing a cent to the IRS.
HSA Savings – Tax-Free Healthcare Savings
And finally, when discussing tax-free investment accounts, we can’t forget about Health Savings Accounts, or HSAs. Now, these accounts are a little different from Roth and 529 accounts in several ways.
How so?
Well, for starters, these accounts allow you to set aside money on a pre-tax basis before Uncle Sam gets a cut of your pay. What’s more, the contributions you make to this account grow tax-free, meaning you don’t pay taxes on dividends, interest or capital gains and for an added benefit, the money comes out tax-free when it’s time to spend your savings.
Therefore, an HSA creates tax-free income by providing a tri-fold tax benefit which is pre-tax contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses.
Tax-Free Considerations
So then, with all this discussion about tax-free income from these various investment accounts, you might be asking yourself, “these benefits all sound great, what the catch?” Well, while each of these accounts offer tremendous benefits, there are some things that you’ll want to consider.
For example, in most cases, you can’t money out of a Roth until you’re at least 59 ½ (or have a qualifying event) and there are limitations about when and how much you can put into the account. Now, there are ways around these limits, but that’s a discussion for another time. Even so, if you expect to be in a higher tax bracket by the time you reach retirement age, then looking into Roth contributions might be worth your time.
As for 529 and HSA accounts, there are a few things you’ll want to consider before you start putting money into these accounts. For starters, while you can begin taking money out of the accounts almost immediately after making contributions, you need to keep in mind that to qualify for tax-free status on those withdrawals, the money must be used for qualifying expenses.
Either way, the big takeaway here is that if you’re looking to put money to work now so you can fund your future lifestyle, education or healthcare expenses in a tax-free manner, then you should consider looking into a Roth IRA, 529 or HSA account.
Unlocking the Hidden Gems: Tax-Free Financial Products and Securities
Alright, so now that we’ve talked about certain tax-free investment account types out there, let’s talk about financial products and securities that offer similar tax advantages.
Here again it’s essential to make the distinction between accounts and products or securities. Remember, accounts are like baskets that hold all kinds of investments and shelter them from taxes.
And when it comes to securities and financial products, on the other hand, they can exist either inside or outside of a financial account and offer tax-free income.
Insurance Products: Tax-Free Income and Financial Security
For example, insurance products, like disability, long-term care and life insurance can be purchased directly from an insurer, or through your employers group coverage, without opening a specific type of financial account. That’s because these types of products are more like contracts between you and the insurer, rather than purchasing an investment security in the open market that needs to be held in an account.
And so, how does the tax-free aspect of these products factor in? Well, imagine that you decide to purchase a disability insurance policy. Essentially, what you're doing is entering into a contract with an insurance company to safeguard your income against the potential risk of being unable to work due to illness or injury.
Alright, now, fast forward to a situation where you unfortunately become disabled and start receiving benefits from this policy. In this situation, these benefits typically would come to you tax-free if you've paid the premiums with after-tax dollars.
And when it comes to long-term care insurance, this type of coverage operates in a similar way, except that it helps defray future costs associated with extended medical care with the benefits paid out from such a policy generally coming to you tax-free.
Now, life insurance is another insurance product that offers tax-free income, but this time not to you specifically, but to your loved ones instead. Here an insurance company offers what’s called a death benefit to your designated beneficiaries upon your passing. And, typically, this death benefit is like a gift received tax-free by your beneficiaries.
With all of this said, it’s essential to keep in mind that there are some situations where insurance payouts could be taxable. For example, in certain situations, if policy premiums are paid by your employer, then you could find a portion of your disability or long-term care proceeds taxable. And on the life insurance side, if your estate is the beneficiary of your policy, then you could find yourself paying estate tax on the state side, or federal tax if that life insurance policy pushes your estate above certain exemption limits.
Financial Securities: Exploring Tax-Free Investments
Ok, so now that we’ve talked about insurance products, let’s take a few minutes to talk about tax-free securities. Here again, whereas an insurance policy is a contract between you and the insurance company, purchasing a tax-free security, like a municipal bond, often times means holding the security in a financial account.
Now, municipal bonds, also known as "munis," are certain investments where you’re lending money to a municipality, such as a city, county, or state. And these entities often borrow money from investors to finance public projects, like building schools, highways, or sewage systems.
And here's where the tax-free part comes into play.
The borrowers pay you interest for lending them money, and, because of laws that are currently in place for these muni bonds, the interest income that you earn is typically exempt from federal income taxes. So, instead of giving a portion of your investment returns to the government, in many ways, you're allowed to keep all of your earnings.
What’s more, depending on the specifics of the bond and where you live, your interest income might also be free from state and local income taxes. And so, as a result, investing in municipal bonds from your own state could provide an even greater tax advantage and offer a completely tax-free source of income in some instances.
Now, when it comes to investing in tax-free securities like munis, there are some key caveats to keep in mind. For example, munis may offer lower interest rates than other bonds, so it’s crucial to evaluate whether the tax exemption makes them more attractive on an after-tax basis relative to taxable bonds.
And another thing to keep in mind is that while the income you receive from munis is often tax-free, you’re still likely to pay capital gains tax from selling a municipal bond before maturity. And finally, it’s crucial to keep in mind that you don’t get a double benefit from holding a muni in a tax-sheltered investment account like an IRA, 529 or HSA account, so that’s something to keep in mind as well.
Real Estate and Estate Planning: Strategies for Tax-Free Asset Transfers
Alright, so now that we’ve talked about how various financial accounts and products can help you navigate the tax man in the present, let’s talk about how navigating real estate and estate planning can also lead to tax-free asset transfers for yourself and your loved ones.
Tax-Free Income from Real Estate: Capitalizing on Home Sales
To start, let’s focus on how you can generate tax-free income from the sale of your home. Now, when you sell real estate, you’re likely to make a capital gain if the sales price is higher than what you originally paid for it. For example, if you bought your house for $500,000 and you sell it for $750,000, then your potential capital gain is $250,000.
Now, imagine that you've decided to sell your home in a high-cost part of the country so that you can move to a more affordable cost-of-living state. So, to go about this approach, you make your preparations and after the sale, you find that you've got a capital gain of $250,000. And because you met the necessary criteria, the entire amount is exempt from taxes, leaving you with a sizable sum of money you can now use however you want.
Now, it’s crucial to keep in mind that in order to make this all work you must meet certain criteria to be eligible for this exclusion. The first requirement is that you have owned the property for at least two years during the five-year period ending on the date of the sale. This is what’s known as the ownership test. The second condition is that the home must have been your primary residence for at least two years during that same five-year period, also known as the use test.
And finally, you’re not allowed to have excluded the gain from the sale of another home during the two-year period prior to the sale of your current home. That’s because this rule ensures that you’re not flipping homes and constantly taking advantage of this tax benefit over and over. Even so, if you meet all of the criteria to get the exclusion, you could tap your home as a source of tax-free income as a way to hasten your journey to financial independence.
Gifting Tax-Free Income: Sharing Wealth While Reducing Taxes
Alright, so now that we’ve talked about using real estate to generate tax-free income, let’s take a few moments to talk about gifting and estate planning to set your loved ones up for tax-free income in the future.
Now, some individuals may feel overwhelmed by the mere mention of the term estate planning. And if that’s you, that’s ok because we recently published a post on how to navigate the complexities of estate planning to make it work for you, so be sure to check out that resource.
But for now, let’s talk about a few ways that you can transfer assets to your loved ones without paying income tax. The first way is through gifting. Now, when you gift assets or money to someone while you’re still alive, it can potentially allow them to avoid giving a portion of that money to Uncle Sam.
How so?
Well, that’s because when you’re gifting an asset, what you’re doing is essentially passing on the responsibility for any income generated by those assets to the recipient. And, if the recipient falls within a lower tax bracket than you or if they have deductions or credits that offset the income, they may end up paying little or no tax on the gifted income.
Let’s look at an example to explain this a little better. Now, let's say that you have investments that generate significant income each year, and you’re in a high tax bracket. By gifting some of those investments to a family member or loved one who is in a lower tax bracket, any income generated from those investments may be taxed at a lower rate or possibly not taxed at all, which can result in tax savings for the receiver. Now, while we’ve talked about transfers of assets, this approach also applies to cash gifts.
Now, cash gifts are a little different than asset transfers, it's crucial to note here that there are specific rules and limitations surrounding gifting for tax purposes. For instance, there is an annual gift tax exclusion that allows you to give a certain amount to an individual each year without triggering gift tax consequences, which is currently $17,000 or $34,000 for a couple.
Tax-Free Inheritance: Step-Up in Basis and Its Wealth-Building Potential
Alright, while gifting allows you to provide tax-free income to your loved ones while you’re still alive, inheritance planning allows you to offer tax-free income after you pass away, and one way this is done is through a set-up in basis.
And how does this work?
Well, let's say you inherit a million-dollar investment property from your wealthy uncle Frank who recently passed away. Now, the trouble is that Uncle Frank has depreciated that property over the years, and it now has a low cost-basis. Normally, if you were to sell that asset, you would have to pay taxes on the capital gains.
However, with a step-up in basis, what happens is that the cost-basis of the inherited asset is adjusted to its fair market value at the time of the Uncle Frank’s death. In other words, the cost basis for tax purposes is "stepped up" to its current value, erasing any potential capital gains that may have accrued during Frank’s lifetime.
Now, when it comes to bequeathing, or transferring your assets, this step-up in basis can come as a substantial advantage for individuals who inherit assets with significant appreciation. That’s because it allows them to potentially sell the asset and realize a profit without owing capital gains taxes on the appreciation that occurred before the inheritance.
So then, from an estate planning perspective, thinking about which assets you want to gift now and which ones you want to leave as an inheritance is a critical component of creating tax-free income through the estate planning process.
Plan Your Way into Tax-Free Income
Indeed, by now, you’ve likely come to realize that tax planning is a cornerstone of a sound wealth management strategy. In many ways, it's the unsung hero that safeguards your hard-earned wealth, curtails tax liabilities, and unearths the chance for tax-free income. And by mastering these techniques and tactics, you can sail through the labyrinth of the US tax code and harness many strategies to create wealth that lasts a lifetime.
To be sure, tax-free income can come from tax-advantaged investment accounts like Roth IRAs, 529 Plans, and HSAs. That’s because they offer tax-free growth of otherwise taxable investments, and, eventually, tax-free withdrawals for specific purposes like funding your lifestyle, healthcare, or education expenses.
Beyond investment accounts, certain financial products and securities carry their weight in gold when it comes to tax-free income. That’s because insurance policies like disability, long-term care, and life insurance can serve up tax-free benefits under certain situations, which ensures that your income is secure and offers financial protection for you and your loved ones. And, at the same time, investments in tax-free securities like municipal bonds can provide you a tax edge, which can exempt the interest income from federal, state, and even local income taxes.
And, as we just discussed a moment ago, it’s essential to remember that real estate and estate planning can be a real game-changer in generating tax-free income. Indeed, by decoding various tax strategies and deploying them effectively, you can take one step closer to becoming the master of your own financial independence journey.
Is a Roth Conversion Right for You?
A Roth conversion is a critical consideration for many high-earning tech professionals and business owners, but is it right for you?
To be sure, as you delve into the work of planning for your financial independence journey, it's essential to understand the intricate dance between taxable and tax-free retirement accounts. And as we've pointed out in recent articles, with a strategic approach, you can make the most of your hard-earned money and ensure a comfortable retirement that aligns with your aspirations.
But, now, at what point should you consider a Roth conversion?
Well, picture this: You're diligently setting aside a portion of your earnings in a traditional 401k or a similar taxable retirement account. It's a tried-and-true method, offering immediate tax benefits, but there are long-term implications that you may not have considered.
For example, as your savings grow, so does the potential tax liability. From this perspective, then, the question arises, "how can you strike a balance between receiving tax advantages today and dealing with a future tax burden?"
That's where tax-free retirement savings vehicles like Roth IRAs come into play.
That’s because with a Roth IRA, you pay taxes on your contributions upfront, but the growth and withdrawals are entirely tax-free in retirement. It's like planting seeds today that will blossom into a tax-smart future.
But, again, the big question here is is this the right strategy for you? Should you maximize your 401k contributions to take advantage of immediate tax benefits? Or would it be wiser to prioritize Roth IRA contributions, offering tax-free growth potential. So then, how do you navigate these choices and find your optimal balance?
Now, make no mistake, retirement planning is rarely a one-size-fits-all endeavor because it's about crafting a strategy that suits your unique circumstances. That’s why as you embark on the journey of maximizing your retirement savings, understanding the interplay between taxable and tax-free accounts is paramount.
By strategically considering your order of operations, leveraging 401k contributions, evaluating your traditional and Roth IRA options, and even delving into the realm of Roth conversions, you can lay a solid foundation for a financially secure future.
Understand the Difference Between Tax-Deferred (Taxable) and Tax-free Retirement Accounts
Now, as you embark on your journey towards financial independence, it is crucial to grasp the distinction between taxable and tax-free retirement savings contributions. This understanding likely will empower you to make informed decisions about your savings options, optimize tax efficiency, and potentially enhance the longevity of your retirement savings.
Now, to achieve these objectives, one powerful tool at your disposal is a Roth conversion. Before delving into its benefits, let's explore the concept of taxable retirement savings options like the 401(k) and Traditional Individual Retirement Account (IRA), as well as tax-free options such as the Roth IRA. That’s because by understanding these choices and how they differ, you can strategically plan for your future in a more thoughtful manner.
Tax-Deferred (Taxable) Retirement Savings
So, what exactly is a taxable retirement account? In simple terms, it refers to savings accounts like 401(k)s and Traditional IRAs, where contributions grow without tax consequences in the present, but future withdrawals are subject to ordinary income taxes.
401(k) Plans
And how does this work with a 401(k)?
Well, as you’ll recall, these types of accounts are employer-sponsored retirement savings programs enabling you to allocate a portion of your pre-tax earnings towards your retirement fund.
Now, one notable benefit of these accounts is that the contributions you make are not taxed in the year that the income is earned. This reduces your taxable income, allowing your savings to grow tax-deferred and potentially reducing your overall income tax liability. Furthermore, any employer matching contributions effectively yield a 100% return on your own savings.
However, when it comes time to withdraw funds from your 401(k), these distributions are treated as ordinary income and subject to taxation. This makes 401(k)s tax-deferred accounts, as all distributions are typically taxed either upon withdrawal or when required minimum distributions (RMDs) become mandatory.
Traditional IRA
Now, let's shift our focus to the tax-deferred cousin of the 401(k): the Traditional IRA. Similar to a 401(k), a Traditional IRA allows you to defer taxes on contributions made with after-tax income.
Contributions to this type of account are typically tax-deductible, reducing your taxable income for the year. Like a 401(k), capital gains, dividends, and interest earned within a Traditional IRA remain untaxed until you start withdrawing funds.
Even so, upon withdrawal or when RMDs are required, the distributions are taxed as regular income, with the tax bracket in retirement determined by your total annual income.
Tax-Free Retirement Savings
Alright, now that we’ve explored tax-deferred accounts, let's now turn our attention to tax-free retirement savings options. These include accounts like the Roth IRA, where contributions are made with after-tax dollars, and withdrawals are completely tax-free.
Roth IRA
And how does a Roth IRA work?
Well, as we mentioned earlier, a Roth IRA is funded with after-tax income, meaning you contribute to the account using your take-home pay. And while this may seem less advantageous compared to pre-tax contributions, the real benefit lies in tax-free withdrawals during retirement.
That’s because, as long as the Roth IRA has been open for at least five years, and you are at least 59 ½ years old, any distributions you make from this account will be entirely tax-free.
And this makes the Roth IRA a compelling choice if you anticipate being in a higher tax bracket during retirement, expect future tax rate increases, or simply want to avoid mandatory distributions altogether.
Now, after exploring the differences between taxable and tax-free accounts, the question remains, “how do you decide which type of account to fund?” Well, the answer depends on several factors.
Current vs. Future Tax Bracket
If you anticipate being in a lower tax bracket during retirement compared to your current situation, sticking with a 401(k) or Traditional IRA may be advantageous. That’s because by deferring taxes now and paying a lower tax rate upon withdrawal, you can potentially minimize your overall tax burden.
However, if you expect to be in a higher tax bracket in retirement, a Roth IRA becomes a more appealing option. That’s because paying taxes upfront allows you to enjoy tax-free withdrawals later, effectively sidestepping potentially higher taxes in the future.
Now, it's crucial to note that you don't have to choose one account type exclusively. In fact, a mix of both taxable and tax-free retirement savings accounts can provide optimal flexibility and tax diversification. This approach allows you to manage taxable income in retirement and hedge against future changes in tax rates.
Indeed, understanding the differences between taxable and tax-free retirement savings options is a crucial step when considering a Roth conversion. Both types of accounts offer unique advantages and disadvantages, and the right choice depends on your individual circumstances, including your current income, expected future income, and retirement goals.
Consider Your Order of Operations
Alright, now that we've discussed the differences between taxable and tax-free accounts, let's review your order of operations when it comes to savings contributions. Just like solving a complex math equation, there's an ideal way to put your income to work before fully converting your savings to a Roth IRA.
Maximizing Your 401k Contributions
So, then, where should you put your money to work first?
Well, when it comes to saving for retirement, your employer-sponsored retirement plan, such as a 401k, can be a potent resource. That’s because these plans offer unique advantages that significantly enhance your long-term savings strategy.
And as we’ve mentioned before, one of the biggest benefits is the potential for an employer match. Now, this happens when your employer contributes additional money to your 401k based on how much you contribute in the first place.
And it's essentially free money, providing an immediate 100% return on your investment that you can't get through most other retirement savings strategies. And the fact is that many people leave money on the table every year by not taking full advantage of the employer match.
And so, why is an employer match so important?
Let's consider an example to illustrate why matching is so important. Suppose your employer offers a 100% match on your contributions up to 6% of your salary. If you contribute 6%, your employer adds an additional 6% (i.e., 100% of your 6% contribution). That’s why failing to contribute that 6% in the first place means missing out on that extra 6% from your employer, effectively leaving money on the table.
So then from this perspective, the first step in maximizing your retirement savings should always be to contribute at least enough to your employer-sponsored retirement plan to fully capture your employer's matching contribution.
Now, it’s also worth noting that the Internal Revenue Service (IRS) sets limits on how much you can contribute to these types of retirement accounts each year. As of 2023, the maximum contribution limit for a 401k, 403(b), or TSP is $22,500. And if you're aged 50 or older, you can contribute an additional $7,500 per year. And this catch-up contribution is designed to help individuals who are closer to retirement age bolster their savings.
So then, if your financial situation permits, consider maximizing your contributions to these accounts up to their limits. Doing so not only allows you to take full advantage of the tax benefits these plans offer but can also significantly enhance your long-term savings due to the power of compounding on a pre-tax basis.
Taking Advantage of Traditional IRA Contributions
Alright, so now that you’ve taken full advantage of your employer's 401k match or reached your contribution limit, another smart strategy to consider is funding a Traditional IRA. A Traditional Individual Retirement Account (IRA) offers numerous advantages that can help you grow your retirement savings more effectively and efficiently.
And the primary advantage of a Traditional IRA is the tax deductibility of contributions. That’s because any money you contribute to a Traditional IRA can be deducted from your income for a given tax year, effectively reducing your taxable income. This means you'll owe less income tax, freeing up more of your money for saving or investing.
And as of 2023, the contribution limit for a Traditional IRA is $6,500 per year. And this contribution limit applies collectively to all of your IRAs, including both Traditional and Roth accounts.
While the tax benefits of a Traditional IRA are notable, it's crucial to be aware of certain limitations that apply if you or your spouse have a retirement plan through work. The IRS imposes income limits that can reduce or even eliminate your ability to deduct your Traditional IRA contributions if you or your spouse are covered by a workplace retirement plan.
For example, in 2023, if you're covered by a retirement plan at work, the deduction for contributions to a Traditional IRA is phased out for singles and heads of household with modified adjusted gross incomes (MAGI) between $73,000 and $83,000.
For married couples filing jointly, where the spouse making the IRA contribution is covered by a workplace retirement plan, the income phase-out range is $116,000 to $136,000. If you're not covered by a workplace retirement plan but your spouse is, the deduction is phased out if your combined income is between $204,000 and $214,000.
Now, it’s important to note that these income ranges are subject to change and can vary from year to year, so it's essential to verify the current ranges with the IRS before making a contribution.
So then, if you're eligible, it's wise to contribute the maximum amount to your Traditional IRA each year. Doing so provides you with an immediate tax deduction and allows your savings to grow tax-deferred over time. This means you won't owe taxes on your investment earnings until you start taking distributions in retirement, enabling your money to compound more effectively.
Prioritizing Roth IRA Contributions
Now, once you've maximized your contributions to your 401k and Traditional IRA, the next logical step in your retirement savings journey is to consider a Roth IRA. While Roth IRA contributions don't provide an immediate tax deduction like Traditional IRA contributions, they offer several unique benefits that make them a valuable part of a balanced retirement savings strategy.
Now, before we talk about these benefits, let’s take a step back and recap what makes a Roth different from a Traditional IRA or employer-sponsored plan.
Unlike 401k and Traditional IRA accounts, contributions to a Roth IRA are made with after-tax dollars. This means you pay income tax on the money before contributing it to the account. While this might seem like a disadvantage compared to tax-deductible contributions, it still offers a significant payoff down the line in the form of tax-free withdrawals.
To be sure, with a Roth IRA, both your contributions and the earnings on those contributions can be withdrawn tax-free during retirement, provided the withdrawals meet certain qualifications. This means the money you invest in a Roth IRA today could grow substantially over time, and all of that growth will be yours to keep when you retire.
Now, as of 2023, the Roth IRA contribution limit is the same as that of a Traditional IRA which is $6,500 per year and $7,500 for those aged 50 or older. Even so, with a Roth IRA it’s essential to note that certain income restrictions can limit your ability to put money into these accounts.
For those filing single and head of household, the ability to contribute to a Roth IRA begins to phase out at a modified adjusted gross income (MAGI) of $129,000 and is eliminated entirely at $144,000. For married couples filing jointly, the phase-out range is between $204,000 and $214,000.
Put simply, if you make too much money, more often than not you likely can’t make a direct contribution to a Roth IRA.
Even so, the Roth IRA is a powerful retirement savings tool because it allows you to pay taxes now in exchange for tax-free income later. This can be particularly beneficial if you anticipate being in a higher tax bracket in retirement than you are currently or if you believe that tax rates are likely to increase in the future.
And by contributing to a Roth IRA, you're essentially locking in your current tax rate. This could result in substantial tax savings in the long term, as you won't owe taxes on the growth of your investments when you start taking distributions.
Additionally, Roth IRAs aren't subject to required minimum distributions during the account owner's lifetime, unlike Traditional IRAs and 401ks. This flexibility allows you to manage your retirement savings and withdrawal strategy on your terms.
Calculate the Benefit of a Roth Conversion Using the NPV Approach
Alright, so what if you find yourself in a position where you’ve maximized your contributions to your employer-sponsored plan, and taken full advantage of your Traditional IRA but make too much money to contribute to a Roth IRA? Well, you could consider doing a Roth conversion.
And what is a Roth conversion?
Well, a Roth conversion is the process of transferring assets from a traditional IRA or 401k into a Roth IRA. Now, as we’ve mentioned before, this is a strategic financial decision that can offer significant tax benefits, enabling you to maximize your retirement savings. However, like any financial decision, it entails complexities and requires careful consideration.
Indeed, understanding the benefits of a Roth conversion is just one aspect of the puzzle. To determine if it is the right move, you need to compare the cost of the conversion which is essentially the taxes you would have to pay now versus the potential benefits which is mainly the tax-free withdrawals in the future.
And how do you do this comparison? Well, this is where the net present value (NPV) approach comes into play.
The NPV approach is a financial calculation used to determine the present value of an investment while taking into account the time value of money. In essence, it calculates the worth of future cash flows in today's dollars.
And when applied to a Roth conversion, the NPV calculation helps compare the current tax cost of the conversion with the present value of future tax-free withdrawals. And so, how do we determine if the NPV is good or bad?
Well, if the NPV is positive, it suggests that the present value of the future benefits of a Roth IRA outweighs the immediate tax cost, indicating a beneficial conversion. Conversely, a negative NPV suggests that the conversion may not be advantageous.
How to Calculate NPV for a Roth Conversion
To calculate the NPV for a Roth conversion, several variables need to be estimated:
- Current Tax Cost: This represents the tax amount you would pay if you converted your traditional Individual Retirement Account (IRA) to a Roth IRA today. For example, if you have a traditional IRA worth $100,000, and your current tax rate is 25%, the tax cost of converting to a Roth IRA would be $25,000.
- Future Tax Savings: This estimates the value of the tax you would save on distributions from a Roth IRA in the future. Unlike traditional IRAs, Roth IRA withdrawals are tax-free during retirement. To calculate this, you need to estimate your future tax rate and the expected annual withdrawal amount. For instance, if you anticipate withdrawing $50,000 per year from your Roth IRA in retirement and expect your tax rate to be 25% at that time, your annual tax savings would amount to $12,500.
- Discount Rate: This is an estimate of the rate of return you could expect to earn on your investments if you didn't convert to a Roth IRA. For example, if you expect your investments to earn an average of 6% per year, this would be your discount rate.
- Investment Horizon: This refers to the number of years until you plan to start withdrawing money from your retirement account. If you intend to retire in 20 years, your investment horizon would be 20 years.
Once you have estimates for these variables, you can use the following formula to calculate NPV:
NPV = (Future Tax Savings / (1 + Discount Rate)^Investment Horizon) - Current Tax Cost
The result of this calculation will provide you with the net present value of your Roth conversion in today's dollars. A positive NPV suggests that the conversion is likely a good financial decision, while a negative NPV suggests that you may be better off not converting to a Roth IRA.
Considerations When Using the NPV Approach
Make no mistake, the Net Present Value (NPV) approach is a powerful tool in the decision-making process when considering a Roth IRA conversion. With that said, this approach is not without its complexities, that’s because this approach relies on several estimates and assumptions that can significantly influence the results.
The Impact of Changes in Tax Law
Now, one fundamental assumption in an NPV calculation is that current tax laws will remain constant. However, tax laws are subject to political forces and can change over time.
For example, future changes could affect the tax benefits associated with Roth IRAs, such as tax-free distributions, or modify the tax rates applicable to Traditional IRA distributions. If income tax rates were to decrease in the future, the tax savings from a Roth conversion would be less than what you might have estimated using current rates.
Predicting Your Future Tax Rate: A Not-So-Certain Exercise
Another factor to consider when conducting conversion analyses is that the trajectory of your future specific tax bracket is largely unknown. Indeed, while determining your current tax rate is relatively straightforward in the present, estimating your future tax rate can be much more challenging. That’s because numerous factors can influence this rate, many of which are difficult to predict accurately.
And these factors can include changes in your income, whether from employment, investments, or retirement distributions, which can significantly impact your future tax bracket. And even your personal circumstances, like a change in marital status, can also alter your future tax liabilities.
The Role of the Assumed Rate of Return
And, finally, another key assumption in the NPV calculation to take into consideration is the discount rate, which represents the assumed rate of return on your investments. This rate plays a pivotal role in determining the present value of future tax savings or costs.
Now, while history is typically a useful indicator of market direction, predicting the rate of return can be challenging due to the variability of market conditions and investment performance. And this uncertainty is a key consideration when performing an NPV analysis because the rate of return significantly influences the results of the NPV calculation.
That’s because a higher assumed rate of return reduces the present value of future tax payments, making a Roth conversion appear less attractive. Conversely, a lower rate increases the present value of these future tax savings, potentially favoring the conversion.
Either way, using the NPV approach to evaluate a Roth IRA conversion is a powerful method for understanding the potential long-term financial impact of this decision. However, it's important to remember that this calculation relies on estimates and assumptions that are subject to change. That’s why it’s essential to consider multiple scenarios and work with a professional who can provide personalized advice based on your specific circumstances.
Is a Roth Conversion Right for You?
Taken together, in the ever-evolving landscape of preparing for financial independence, the thing that remains constant is the need for a strategic and informed decision-making process. And, as high-earning tech professionals and business owners, you possess the power to shape your financial destiny and secure a measure of financial independence that reflects your purpose and values.
Remember, the path to financial freedom is as unique as your fingerprint. That's why it's essential to understand the intricacies of balancing taxable and tax-free accounts, strategically leveraging your 401k contributions, and making informed choices regarding traditional and Roth IRA contributions.
And by calculating the net present value of a Roth conversion, you can gain a clearer understanding of the potential benefits and make decisions that align with your long-term goals and help ensure that you're making a decision that's right for you.
Indeed, by understanding the various tradeoffs, considering the order of operations, and harnessing the power of Roth conversions, you'll be well-equipped to make confident and informed decisions about your wealth. Even more crucial, doing so will take you one step closer to becoming the master of your own financial independence journey.
The Market Feels Unstable — Here’s How to Stay on Track
There are times in market cycles when economic, geopolitical, and financial conditions converge in ways that create palpable uncertainty. In many ways, it can feel like standing on the precipice of an abyss.
Today, I would argue that we are in just one of those moments.
Often, it’s not just one event, but a cascade of interconnected developments that lead one to conclude that things are about to get bad.
History Often Rhymes
Early on in my career, it started with the failures of Bear Stearns and Lehman Brothers, the nationalization of Fannie Mae and Freddie Mac, and the bailouts of AIG and Citi, all of which signaled the fragility of the global financial system in 2008.
In 2020, early reports of health warnings, travel restrictions, and border closures eventually escalated into a near-total shutdown of the global economy, prompting widespread existential fear.
Now, in early 2025, we are experiencing heightened uncertainty as the resumption of trade wars with ambiguous objectives, shifting geopolitical alliances, and a retreat from post-war global institutions and a seeming move towards isolationism create a new political and economic reality. These shifts pose significant implications for the global economy and financial markets.
Needless to say, there is much to worry about in the current political, economic, and market environment. It’s enough to make any sane person want to bury their savings in their backyard.
How to Navigate the Uncertainty
That said, having been through multiple market cycles, being an avid student of history, and considering my background in macroeconomic strategy, I would like to share some thoughts on how to frame today’s environment and what you can do about it financially.
Firstly, I want to acknowledge that we are in the midst of an anxiety-provoking time in U.S. history. I am not going to discount the legitimate fear that many of us may be feeling right now amidst all the political tumult and economic uncertainties. This is a natural response.
With that said, when it comes to investing and the markets, it’s crucial to remember that we’ve been through similar challenges in the past. And with history as our guide, during times like these, it’s essential to remain committed to a long-term, disciplined investment strategy.
Make no mistake, what’s happening today will have significant implications for years to come.
Why It’s Essential to Stay Committed for the Long-term
However, history has shown that, from a capital markets perspective, risk assets tend to sell off during political and economic inflection points, before eventually recovering. These ebbs and flows are a natural part of the market process when key narratives change.
In fact, over the past 100 years, there have been many paradigm-shifting political and economic events, but stock prices continued to march higher thereafter. This point is evidenced in Figure 1.
To be sure, financial markets, after periods of uncertainty, do eventually recover as investors eventually adapt to new political or economic paradigms. Indeed, as figure 1 illustrates, risk asset prices are naturally biased to the upside because if they weren’t, then investing would not be much different from gambling, would it?
Nevertheless, you might say that now is not the right time to be in the markets and that you would prefer to get out. However, history has also shown us that exiting the markets at the wrong time could lead to major disappointment down the road.
For example, Figure 2 shows how missing even the best five days over the past 20 years could have led to significant missed opportunities in the markets. Indeed, back in 2008, it is arguable that peak market fear occurred at the end of the year, just a few months before the market bottomed out in March 2009.
Similarly, in 2020, peak fear occurred in late February before markets bottomed out in March and then took off again in April. Therefore, trying to time the markets or get out when it feels like things are starting to get bad might work against you over the near- and long-term.
Practical Steps to Take
So then, amidst all of this, what should you do about it all?
Well, in uncertain times, many investors often find themselves torn between taking action and standing still.
Here are six key strategies to consider regardless of where you stand today:
#1 Know Your “Sleep Well Number” (Cash Management)
When it comes to cash management, during times like these, it is crucial to know your “sleep-well” number. Depending on where you are in your retirement journey, having enough cash on hand to cover six to eighteen months of living expenses is something to consider now.
Having this number available will enable you to avoid making knee-jerk decisions with your portfolio, enable you to stay committed to your long-term strategy and avoid selling assets at an inopportune time.
#2 Rebalance Your Portfolio
Rebalancing your portfolio now allows you to take some risk off the table. Markets have rallied handsomely over the past eighteen months, which means that your current holdings are very likely out of alignment with your strategic asset allocation.
Rebalancing includes taking gains from positions that have done well in your portfolio and adding to positions that are underallocated in your portfolio relative to your strategic allocation. This approach ensures that you’re not taking any more risk than necessary with your investments.
#3 Stick to Your Long-term Plan
When in doubt, stick to your plan. Remembering your long-term plan is essential during market uncertainty. That’s because it is easy to become distracted and search for a salve to relieve the unease in the near term when things start going off the rails.
However, it’s crucial to remember that your financial plan was created to help you navigate not just the good times, but also uncertain times like the ones we’re experiencing today.
#4 Reconsider Big-Ticket Purchases
If you are contemplating purchasing a new home, car, or other big-ticket item, you may want to consider holding off on any moves for the next few months. This approach will allow you to preserve cash and ensure that you are not locking yourself into a decision at an inopportune time.
#5 Sharpen Your Pencil
At the same time, it is worth sharpening your pencil. Warren Buffett is known to have said, “Be fearful when others are greedy, and greedy when others are fearful.” Depending on your living situation and cash position, fear-driven market sell-offs often provide opportunities to purchase assets at a discount.
If you are in a solid cash position, keeping an eye out for favorable buying opportunities once we have more clarity on the political and economic environment could be worthwhile.
#6 Consider Tax Planning Opportunities
Finally, market sell-offs also present an opportune time for tax planning. And a key tax planning approach includes completing a Roth conversion. That’s because lower portfolio values often translate to lower taxable values. Remember, Roth conversions are not just a fourth-quarter tactic but a year-round opportunity.
Similarly, market downturns can present opportunities for tax-loss harvesting. This approach involves selling stocks at a loss and buying a similar but not identical asset. Even if you do not have gains to offset the losses, you can carry forward the losses as a tax asset to offset future capital gains.
The Big Takeaway
When it comes down to it, the big takeaway from an investment perspective is to stay invested for the long term even though the near term seems so uncertain. While we may be headed for a dark period in the months ahead, I am reminded of how essential it is to remain optimistic.
Viktor Frankl, a Holocaust survivor and author of the book, “Man’s Search for Meaning”, points out in his work that those who adapted and sought meaning in each moment, especially in trying times, had greater ability to endure trials and uncertainty than those who did not.
Make no mistake, we are likely headed for some very trying times in the weeks and months ahead. From a political and social perspective, we do not have a roadmap for navigating what lies ahead, which means we will have to take things one moment at a time. As difficult as that may be, however, finding purpose and direction in uncertain times has always been a defining trait of those who successfully emerge from such events.
What’s more, from a financial perspective, history has repeatedly shown that uncertain times like these often create opportunities for those who stay the course. That’s why having a solid financial plan and a disciplined investment strategy is essential now more than ever. While the near-term outlook may be uncertain, remaining objective and committed to a well-thought-out financial plan continues to be the best way forward.