1Q26 Market & Economic Recap & 2Q26 Outlook
Key Updates on the Economy & Markets
The first quarter of 2026 was one of those periods that reminded investors why markets don't move in a straight line.
Stocks started the year on solid footing with January modestly positive, February quiet, and then March arriving with a jolt. The escalation of geopolitical tensions in the Middle East, including the closure of the Strait of Hormuz, sent oil prices surging and rattled markets in ways that few anticipated heading into the year.
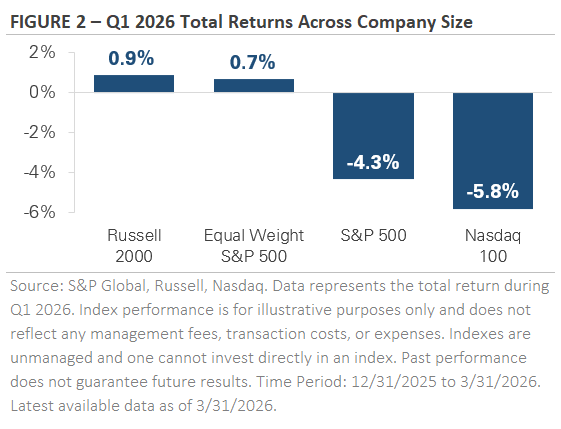
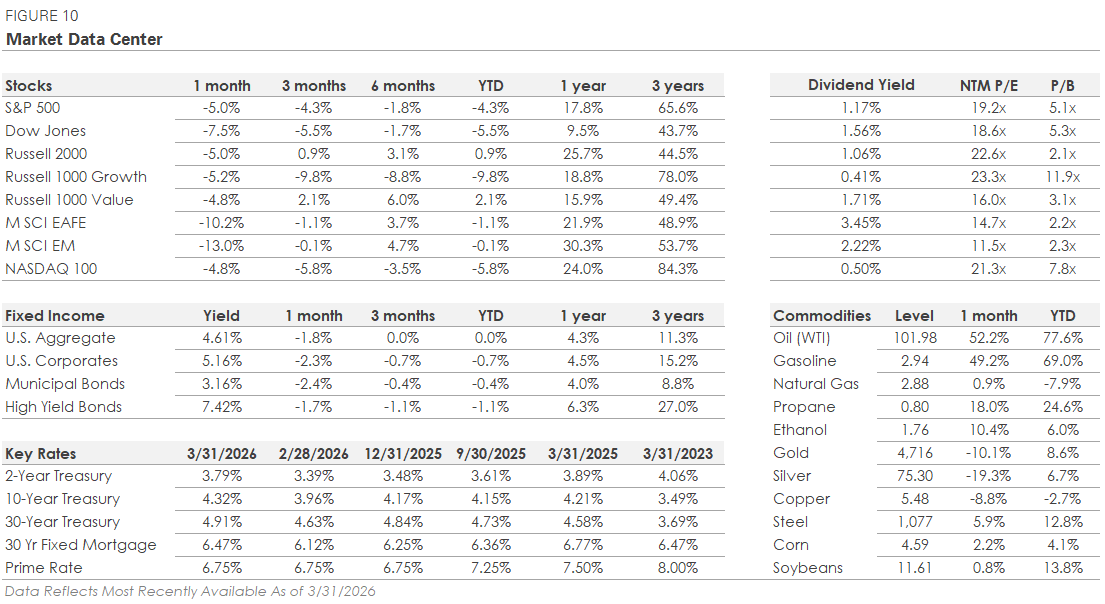
By the time the quarter closed, the S&P 500 was down -4.3%, with the bulk of that decline concentrated in a single month. And if you looked only at that headline number, you might walk away with a grim picture.
But the quarter was more nuanced than the index suggests, and I think it's worth taking a step back to understand what actually happened and what it means for your portfolio going forward.
Higher Oil Prices Changed the Rate Cut Conversation
Indeed, to understand why March felt so disruptive, you have to start with oil.
Crude prices had already been moving higher before tensions escalated with supply concerns tied to Venezuelan output pushing prices up nearly 13% in January, and climbing another 4% in February as geopolitical risks continued to build.
Then March arrived.
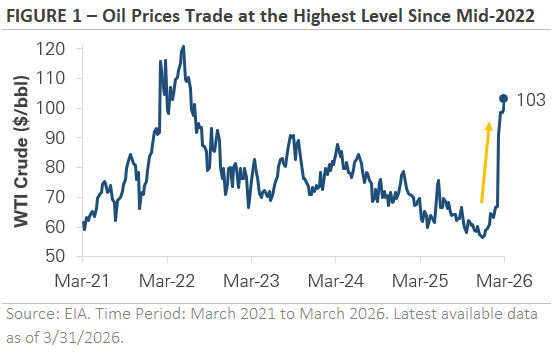
The conflict between the U.S. and Iran intensified, and the closure of the Strait of Hormuz, a waterway that carries roughly 20% of the world's oil, sent crude prices surging nearly 50% in a single month. For the full quarter, oil prices rose more than 70%, reaching levels not seen since mid-2022.
And why does that matter for your portfolio?
Because oil prices don't exist in a vacuum. Higher energy costs flow through to what consumers and businesses pay for goods and services. And as a matter of fact, you've likely already noticed it at the pump, as gasoline prices have risen nearly a dollar per gallon since late February.
And this is happening at a moment when inflation was already showing signs of firming before the conflict began. The Federal Reserve's preferred inflation measure, Core PCE, remains near 3%, and producer prices have been trending higher.
So then, coming into 2026, the market expected the Federal Reserve to cut interest rates two to three times by year end.
That expectation quietly eroded as the quarter progressed.
And by the time March ended, those rate cuts had been priced out entirely, and there was even early discussion about whether a rate hike might come back into the conversation.
The situation is still evolving.
The Strait of Hormuz remains closed as of quarter-end, negotiations are ongoing, and oil is trading near $100 per barrel, a signal that the market expects the disruption to persist for some time.
The April and May inflation reports will be the first data to fully reflect the energy price surge, and they'll go a long way toward shaping the Federal Reserve's next move. In the meantime, headlines out of the Middle East are likely to continue influencing how both stocks and bonds behave in early Q2.
Diversification Quietly Did Its Job
Now, one of the most important, and most overlooked, stories of Q1 was what happened beneath the surface of the S&P 500.
The S&P 500 is a market-cap weighted index, meaning the largest companies carry the most influence over the index's return. When those large companies, particularly those in the technology sector, sold off, the headline number felt worse than what most diversified investors actually experienced.
To put it in perspective, the average S&P 500 stock outperformed the broad index by nearly 5% in Q1. Small-cap stocks, as measured by the Russell 2000, actually gained nearly 1%. And international stocks finished the quarter with a gain of nearly 1% as well, outperforming the S&P 500 by more than 5 percentage points.
And what drove that gap? Well, there were two competing forces at work.
The first was a rotation away from mega-cap tech stocks. For the past two years, a handful of the largest companies drove the majority of the market's gains.
In January, investors started moving away from that concentrated trade. The rotation accelerated in February when concerns about artificial intelligence disruption spread through the software sector, and markets began to price AI not just as a productivity enhancer, but as a potential replacement for entire categories of professional services.
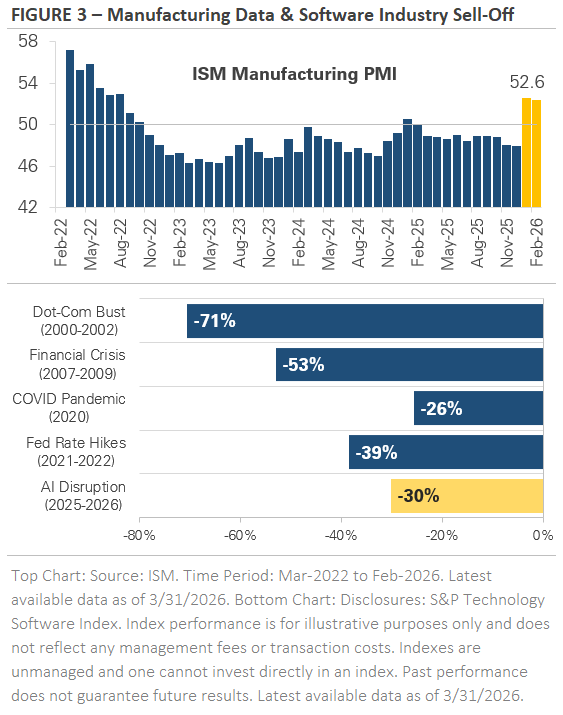
The software sector has now declined nearly 30% from its peak last October, one of the largest non-recessionary drawdowns in over 30 years.
The second force was a genuine improvement in manufacturing activity. After spending nearly a year in contraction, the ISM Manufacturing Index crossed into expansion territory in February and held there in March.
That's a meaningful sign for the economy and potentially for corporate earnings.
Indeed, the manufacturing sector had been a soft spot in the economy since 2022, and the data suggested it was gaining real traction before the conflict began. Industrials was one of the few sectors to set a new all-time high during the quarter.
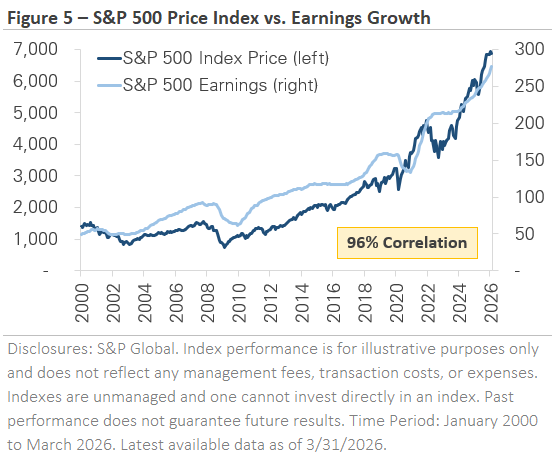
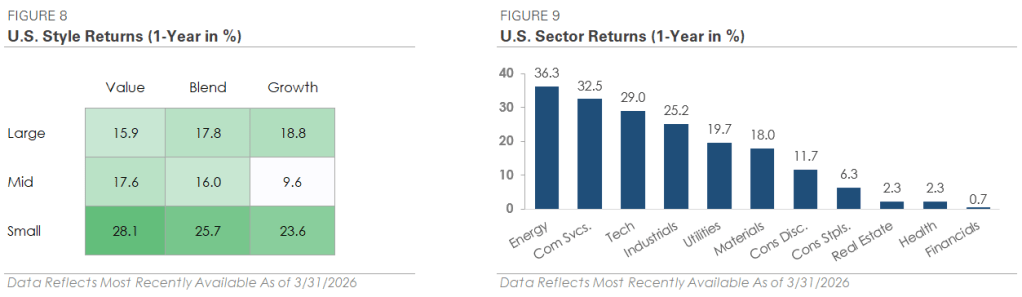
Across the broader equity market, six of the eleven S&P 500 sectors outperformed the index, a sharp contrast to recent years when gains were driven by just a few names. Energy led everything with a 38% return as oil surged.
Materials, Utilities, and Consumer Staples each gained more than 7.5%. On the other end, Technology, Consumer Discretionary, and Financials each declined more than 9%.
The gap between the best and worst sectors was wide. But for investors with diversified exposure across company sizes, sectors, and geographies, the quarter felt more moderate than the S&P 500 return alone would suggest.
Diversification didn't eliminate the volatility. It helped manage it, and that's exactly what it's designed to do.
Bonds Navigated a Volatile Quarter
The bond market had its own version of the quarter's turbulence.
Interest rates rose in January as tariff concerns resurfaced, then fell sharply in February as growth worries, particularly around AI disruption, pulled investors toward safer assets.
March reversed that move quickly.
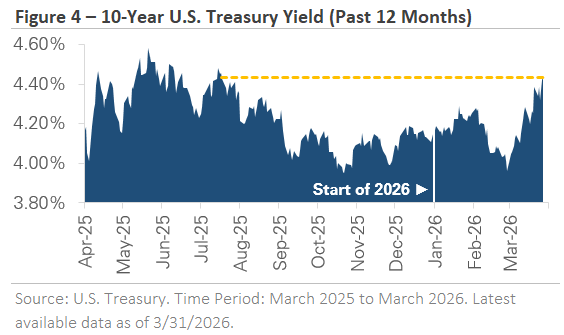
And as oil prices spiked and rate cut expectations faded, yields climbed again. The 10-year Treasury yield ended the quarter near 4.32%, its highest level since mid-2022. The 2-year yield rose nearly 0.35% for the quarter, reflecting how quickly rate cut expectations shifted.
The Bloomberg U.S. Aggregate Bond Index finished the quarter flat, a meaningful step down from the 1% or better returns it produced in each of the prior four quarters. Corporate bonds modestly underperformed higher-quality Treasuries, and credit spreads widened to their highest levels since early 2025.
That widening reflects caution, not crisis, with corporate spreads remaining well below the levels reached during past recessions and financial dislocations.
And what are we to take of all this data?
Well, the bond market is telling us that investors are being careful, but it's not telling us something is broken yet.
What to Watch in Q2
As we move into the second quarter, the central story remains the same: the Middle East, oil prices, inflation, and what the Federal Reserve does next.
Progress toward resolving the Strait of Hormuz closure would ease energy costs and give the Fed more room to maneuver on rates. However, a prolonged disruption means higher oil prices have more time to work through to consumers and businesses, keeping inflation elevated and leaving the Fed in a difficult position.
From a data perspective, the April and May inflation reports are the ones to watch. They'll be the first readings to capture the full impact of higher energy costs, and they'll shape the rate outlook for the rest of the year.
While you're watching those headlines, I want to offer some perspective on the bigger picture.
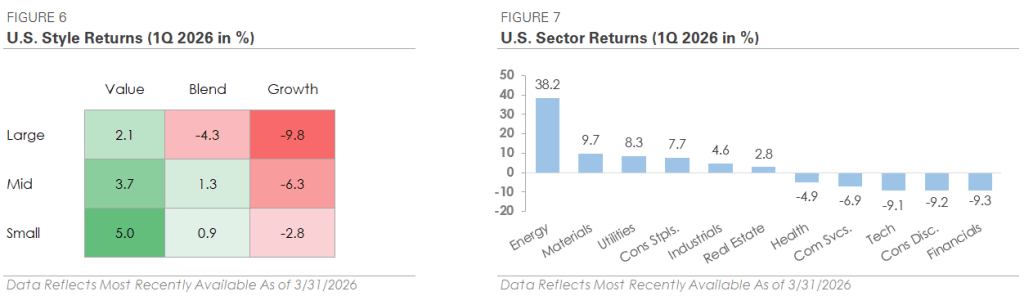
Over the past 26 years, corporate earnings and stock prices have moved together with a 96% correlation.
When earnings rise, prices generally follow.
When earnings deteriorate, as they did in 2001, 2008, and 2020, prices tend to fall with them. What's notable about today's environment is that earnings estimates have continued to rise even as the S&P 500 has pulled back.
Analysts still expect earnings growth in the coming quarters, and profit margins to remain healthy.
Put differently, the market's decline in Q1 was driven by uncertainty around oil, inflation, and Federal Reserve policy, not by a deterioration in the underlying fundamentals that drive stock prices over time.
And that distinction matters.
Certainly, uncertainty is uncomfortable, but it's different from a breakdown in the economic foundation.
The quarter also reinforced something I believe deeply in that staying invested, staying diversified, and keeping a long-term perspective is one of the most effective strategies available to investors. The areas of the market that led over the past two years underperformed in Q1.
Investors with broad exposure across company sizes, styles, and geographies experienced a meaningfully different quarter than the headlines suggested.
When it comes down to it, markets will work through the uncertainty in the Middle East. The data will come in, the Fed will respond, and conditions will shift, as they always do.
In the meantime, your plan was built for periods like this one, and I remain confident in the approach we have in place.

Weekly Market Recap: Oil Shock, Jobs Data, and a Holiday Pause
Market trading this week was driven by a rebound in stocks, rising oil prices, and Friday’s jobs report.
Stocks moved higher through Thursday, even as energy markets reacted to renewed geopolitical tension. Then today, with stock markets closed for Good Friday, the latest payrolls data showed the labor market is still holding up, while bond markets remain open for a shortened session.
By Thursday’s close, the S&P 500 had gained 3.4% for the week, the Nasdaq rose 4.4%, the Dow added 3.0%, and the Russell 2000 climbed 3.3%. That rebound helped markets recover from part of last week’s weakness, but the tone underneath the surface was still shaped by geopolitics.
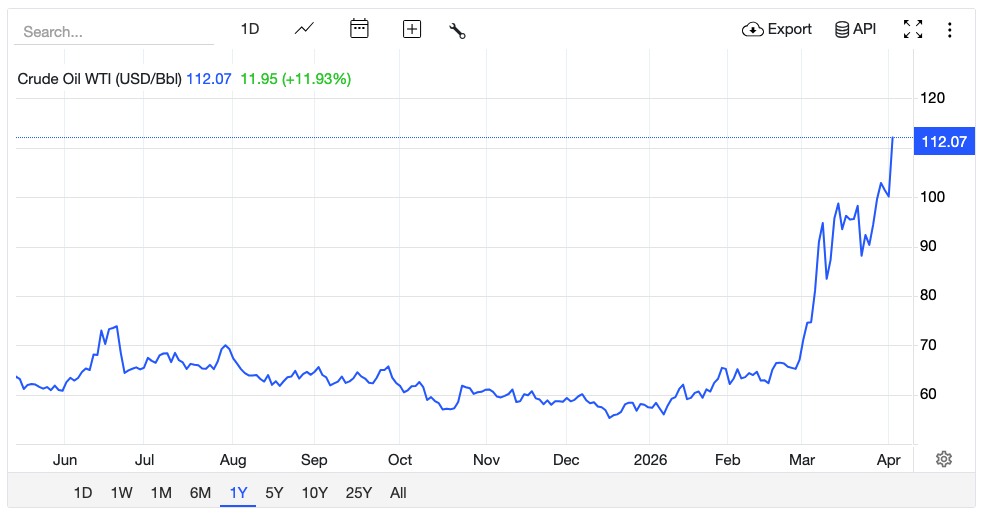
Oil surged sharply after the latest U.S. rhetoric on Iran reduced confidence in a near-term diplomatic resolution. WTI crude closed Thursday at $111.54 per barrel, while Brent ended at $109.03.
Then on Friday morning, the March jobs report showed payroll growth of 178,000, an unemployment rate of 4.3%, and average hourly earnings up 0.2% month over month and 3.5% year over year.
The week’s other key data reinforced the idea that the economy has not rolled over. ISM Manufacturing came in at 52.7 in March, marking a third straight month of expansion. That matters because it suggests the economy is still holding up even as oil prices rise.
In other words, recession fears did not get confirmed this week, but the inflation side of the equation became harder to ignore.
Key Takeaways
Oil Prices Remain the Market’s Pressure Gauge: Last week, falling oil supported hopes that the conflict might cool off. This week, that changed. The renewed spike in crude is a reminder that geopolitical risk is still feeding directly into inflation concerns and broader market sentiment.
Markets Rebounded, but the Backdrop Is Still Fragile: This week’s rally was constructive, especially because gains were broad enough to include small caps. But the rebound happened alongside a major jump in oil, which means the recovery in stocks did not come with a clean improvement in the macro backdrop.
The Labor Market Still Looks Resilient: Friday’s jobs report helped reinforce that the economy is still holding together. That may ease immediate recession concerns, but it also makes it harder to argue that the Fed will have clear room to turn more dovish if energy prices stay elevated.

Tax Update: What You Need to Know Before April 15 and Beyond
April 15 is close. And whether you're putting the finishing touches on your 2025 return, navigating a tax bill you weren't expecting, or thinking through how this year's changes affect your bigger financial picture, this issue covers the ground that matters most right now.
Mega Backdoor Roth Might Not Be Your Biggest Tax Problem
A mega backdoor Roth might not be the best use of available dollars if you already have sizable pre-tax balances in IRAs or retirement accounts. While a mega backdoor Roth can help move new savings into a tax-free bucket, large pre-tax balances may already be creating a future tax problem.
As those balances continue to grow, they can create future RMD pressure, which may increase taxable income, affect Medicare premiums, and reduce tax flexibility later in retirement.
If you already have a large pre-tax retirement balance, the bigger long-term tax issue may not be where to direct your next dollar. It may be the future tax burden attached to money you’ve already saved. A mega backdoor Roth can still be valuable because it helps position new savings for tax-free growth. But if large pre-tax balances are likely to create future RMD pressure, partial Roth conversions may deserve greater priority because they directly reduce that future tax liability.
Click Here to Read the Full Article >>>
The April 15 Deadline: What You Actually Need to Do
Most individual 2025 federal returns are due April 15. If you're not ready, you can file for an extension and buy yourself until October 15 to submit the paperwork. What the extension doesn't buy you is more time to pay. If you owe, that amount is still due on April 15. Pay what you can today and avoid letting interest and penalties compound on the difference.
If a refund is coming your way, file as soon as possible and set it up for direct deposit. IRS has been sending letters to filers who left bank account details off their returns, asking for that information within 30 days. Miss that window and your check comes by mail. At that point you could be waiting six weeks or more past the deadline before you see any money.
If You Owe and Can't Pay
The most important thing is to file your return on time anyway. The penalty for filing late is steeper than the penalty for paying late, so don't let one problem create two.
From there, IRS gives you options. If your total balance (tax, penalties, and interest combined) is $50,000 or less, you can set up a simple payment plan directly through your IRS online account. For more complicated situations, an offer in compromise may let you settle for less than you owe. IRS will want a full picture of your assets and income, and the central question they're evaluating is whether you can realistically pay the full balance. The application fee is $205, though low-income filers are exempt.
One important caution: be skeptical of any firm promising to slash your tax debt for a fee. IRS uses the phrase "offer-in-compromise mills" for these operations, and they rarely deliver what they advertise. If you're facing a difficult tax debt situation, let's work through it together.
Gifting in 2026: More Room to Give
The annual gift tax exclusion rose to $19,000 per person this year. That means you can give up to $19,000 to as many individuals as you choose without filing a gift tax return, paying any gift tax, or touching your lifetime exemption.
If you are single with three family members you want to benefit, that's $57,000 in excludable gifts in a single year. And if you want to give more, larger gifts don't automatically trigger tax. They simply require a Form 709 filing. You won't owe actual gift tax until you've used your full $15 million lifetime exemption.
If legacy planning is part of your broader picture, now is a good time to revisit how your annual gifting strategy fits in.
Retirement Accounts: What's Changing and What's Worth Watching
If you're 70½ or older and making charitable gifts, qualified charitable distributions remain one of the most tax-efficient giving tools available. For 2026, you can transfer up to $111,000 directly from your IRA to a qualifying charity. That amount isn't included in taxable income, doesn't raise your adjusted gross income, and counts toward your required minimum distribution for the year.
Currently, QCDs to donor-advised funds are not permitted. A bipartisan bill in Congress would change that, allowing DAF contributions to qualify the same way direct charitable gifts do. It's worth watching as the legislative calendar develops.
Also worth knowing: the Department of Labor recently pulled back the 2024 regulations that expanded who qualifies as an investment advice fiduciary for retirement accounts. The five-part test under ERISA has been restored, effectively ending a regulatory saga that began in 2016.
The AMT: A Quiet Change With Real Impact
The alternative minimum tax doesn't generate much conversation, but a change embedded in the One Big Beautiful Bill could affect a meaningful number of higher-income households beginning with 2026 returns.
The OBBB permanently extended the higher AMT exemption amounts from the 2017 Tax Cuts and Jobs Act, which is good news. But it also lowered the income thresholds at which those exemptions begin to phase out. Starting in 2026, the phaseout begins at $1 million for married couples and $500,000 for single filers. The exemption also phases out more quickly once those thresholds are crossed.
In practical terms: more filers will owe more in AMT starting in 2026 compared to 2025, particularly those with significant itemized deductions, incentive stock options, or certain investment income. If any of those apply to your situation, it's worth running the numbers before the year gets away from us.
IRS Reform: Rare Bipartisan Progress
There's unusual agreement on Capitol Hill right now around reforming how IRS operates. Senate Finance Committee leaders from both parties have introduced a 63-provision bill aimed at strengthening taxpayer rights and making it easier for individuals and businesses to challenge IRS determinations.
Two provisions worth noting: one would let the Tax Court waive the standard 90-day deadline for filing deficiency case petitions when there are legitimate reasons for the delay. Another would require IRS agents to get written supervisory approval before formally notifying a taxpayer of an assessable penalty.
The bill also proposes regulating unenrolled tax preparers by requiring continuing education and a background check before receiving a preparer ID number. Recent research found significant error rates among this group, particularly on refundable credits and Schedule C items. It's one more reason credentialed, integrated advice matters.
A Few Practical Notes
Filing for a deceased family member. If you're handling a return for someone who has passed, the process varies depending on whether you're a surviving spouse or a personal representative. IRS has a clear, step-by-step interactive guide called "How do I file a deceased person's tax return?" that walks you through each scenario.
IRS enforcement priorities. IRS is actively scrutinizing a handful of abusive tax schemes, including bogus self-employment tax credit promotions, overstated withholding claims, and improper refundable credit filings through Form 2439. If you've seen promotions related to any of these, reach out before taking any action.
529 accounts for home purchases. Two House members have proposed allowing first-time home buyers to use 529 funds tax-free toward a home purchase, with no dollar limit. We don't expect it to gain serious traction, but it reflects how wide the conversation has gotten around housing affordability.
As always, if any of this raises questions about your specific situation, I want to hear from you. Tax planning isn't just about what you owe in April. It's about making sure the decisions you make today still make sense five, ten, and twenty years from now.
Weekly Market Update: Middle East Ceasefire Headlines, Volatile Oil Prices, & Stock Market Rotation
Weekly Market Recap
Market trading was influenced by ceasefire headlines this week.
The S&P 500 rose early after the administration reported talks with Iran, then reversed to close down nearly -0.5% as Iran denied negotiations and the diplomatic window narrowed.
Meanwhile, the market rotation from early 2026 resumed, with small caps, value stocks, and the equal-weight S&P 500 outperforming. Oil dropped nearly -10% on Monday's ceasefire headline before recovering to close the week down roughly -5%.
Treasury yields ended the week higher despite falling mid-week, credit spreads tightened modestly, and the VIX remained elevated.
The week ahead brings the expiration of Trump's five-day strike pause on Iranian energy infrastructure, along with consumer confidence and ISM Manufacturing PMI, the first major economic data releases that will capture the full impact of the war and the oil shock.
Key Takeaways
Oil Prices Remain Volatile
Oil markets whipsawed this week as ceasefire headlines between the U.S. and Iran drove sharp swings in both directions. Prices plunged more than -10% early in the week after President Trump described productive discussions and announced a five-day pause in strikes, raising expectations for a diplomatic resolution.
Those gains reversed when Iran denied active negotiations and later rejected a formal U.S. ceasefire proposal that included reopening the Strait of Hormuz, which remains closed. Iran's counteroffer signals that diplomatic channels are open, but no agreement is imminent.
Bottom Line: Oil prices are unlikely to stabilize until there is clarity on whether negotiations can produce a lasting agreement. Each headline-driven swing is a reminder of how much geopolitical premium remains embedded in energy markets, as well as the stock market.
Markets Traded on Ceasefire Headlines
U.S. equities traded higher early in the week, but reversed lower as the week progressed. The S&P 500 rose over +1%, with most of the advance coming Monday after reports of U.S.–Iran negotiations sparked a broad relief rally.
Markets then pulled back the following session as oil rebounded and uncertainty around a deal resurfaced, staged a rebound when news of a formal ceasefire proposal emerged, and ultimately traded lower as tensions escalated again.
Bottom Line: Stocks remain highly sensitive to ceasefire signals, with the direction of oil prices serving as the most reliable real-time indicator of investor confidence in a diplomatic outcome.
The Stock Market Rotation Resumes
Market leadership broadened again this week as the rotation away from mega-cap stocks reasserted itself. The Russell 2000 outpaced the S&P 500 during the early week rally, and the equal-weight S&P 500 outperformed the cap-weighted index as value stocks pulled ahead of growth.
The divergence is consistent with the trend that emerged in early 2026, when investors began moving toward smaller companies, value stocks, and more economically sensitive areas of the market.
Bottom Line: The rotation paused during the market volatility, but it started to reappear this week. One week doesn't confirm a trend, but the broadening is showing up across multiple measures simultaneously, which is more credible than small-cap leadership alone.
Rate Hike Probabilities Creep Into Fed Pricing
Interest rate expectations shifted again this week as investors began pricing in the possibility that the Federal Reserve could raise rates later in 2026. Futures markets showed rate-hike probabilities rising above 50% in late 2026, with the market starting to price in a rate hike due to concerns that a sustained rise in oil prices will reignite inflation.
At the same time, inflation expectations have reversed slightly lower, suggesting markets still view the current inflation pressures as temporary rather than structural.
Bottom Line: The debate has shifted from the timing of cuts to the possibility of a brief hike, and that repricing matters for duration positioning. If oil stabilizes and inflation expectations remain anchored, the probability of a rate hike could fade.

Here’s Why Concentration Risk Matters
Lately, investors have had no shortage of headlines to process. Geopolitics, interest rates, and questions about the economy have all competed for attention. Those stories matter, and they can certainly move markets in the short run.
But beneath those headlines, another shift has been taking place. And that’s that market leadership has been changing in a subtle way.
And this change is worth paying attention to because leadership changes are often where concentration risk gets exposed. That’s because the stocks and sectors that led in one environment do not always lead in the next. And when the market begins to reassess those winners, the repricing can happen quickly.
This is one reason diversification still matters, especially in a year like this.
A Reminder From Software Stocks
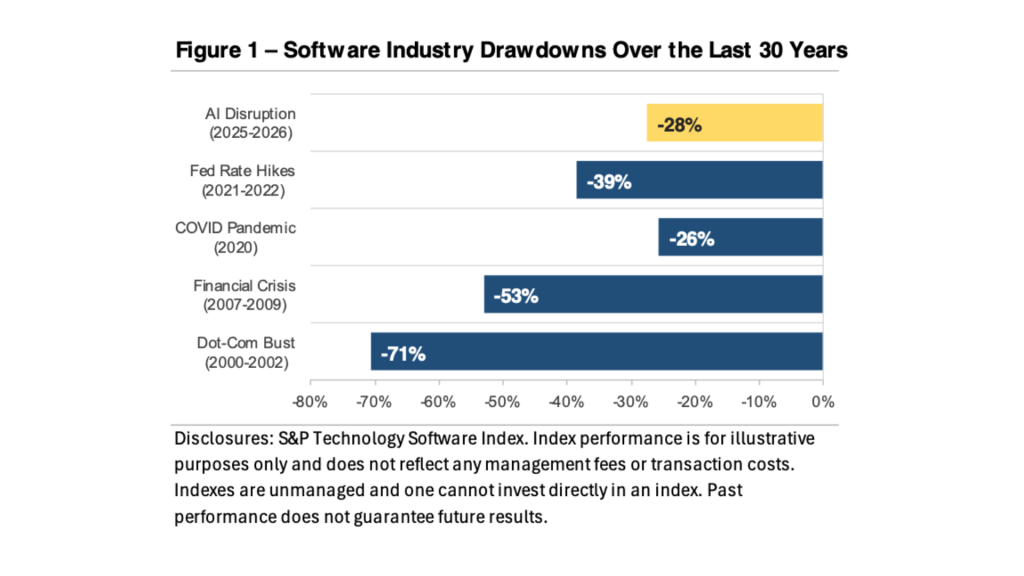
One of the clearest examples has come from the software industry, which has fallen nearly 30% from its peak since last October. The move makes it one of the largest non-recessionary drawdowns in the group in more than 30 years.
And that historical context matters because the two biggest software drawdowns before this one happened during recessions, in the dot-com bust and the 2008 financial crisis, when earnings were under pressure and businesses were pulling back on spending.
Now, it’s worth noting that the 2022 decline was different because that selloff was driven by the Federal Reserve’s aggressive rate-hiking cycle, and software stocks fell nearly 40%.
This time, however, the catalyst appears to be different. The market is not primarily reacting to recession fears or rising rates. Rather, it appears to be reacting to uncertainty around artificial intelligence and what it could mean for future business models as we’ve discussed in previous reports.
What Changed Earlier This Year
The selloff in software picked up speed in January and February after a series of AI product launches suggested that general-purpose AI tools may be able to handle tasks that had previously required specialized software, often at a lower cost.
That mattered because it changed the market’s framing.
For the past two years, AI had largely been viewed as a productivity tool, something that could help existing businesses become more efficient. But earlier this year, investors began asking a different question: what if AI does not simply improve some business models, but starts to pressure or replace parts of them?
Software stocks felt that shift first. Then the concern spread into other areas, including financial data providers, commercial real estate services, and logistics companies.
In other words, this was not just about one corner of the market having a bad stretch. It was a broader reminder that when investors begin to question the durability of future earnings, yesterday’s leaders can suddenly look much more vulnerable.
Where Things Stand Now
By late February, some of the more extreme fears around AI disruption began to cool, and markets started to stabilize. Analysts pushed back on the most aggressive replacement narratives, and the conversation became more measured.
The question shifted from whether AI would replace entire industries to which businesses are genuinely vulnerable, and which may be able to adapt, defend their position, or even strengthen it.
Since then, some of the hardest-hit stocks have rebounded. Even so, the software industry remains down more than 25%, and the broader question is still unresolved. AI is likely to remain a force that shapes leadership across markets, especially in software and other professional-service-oriented industries.
What This Means for Your Portfolio
For investors, the lesson is not that every new innovation requires a major portfolio change.
The lesson, rather, is that market leadership can shift quickly, and concentrated positions can become more vulnerable when the narrative changes. Even strong, well-established businesses can be repriced in a short period of time when the market starts applying a different set of assumptions to future earnings.
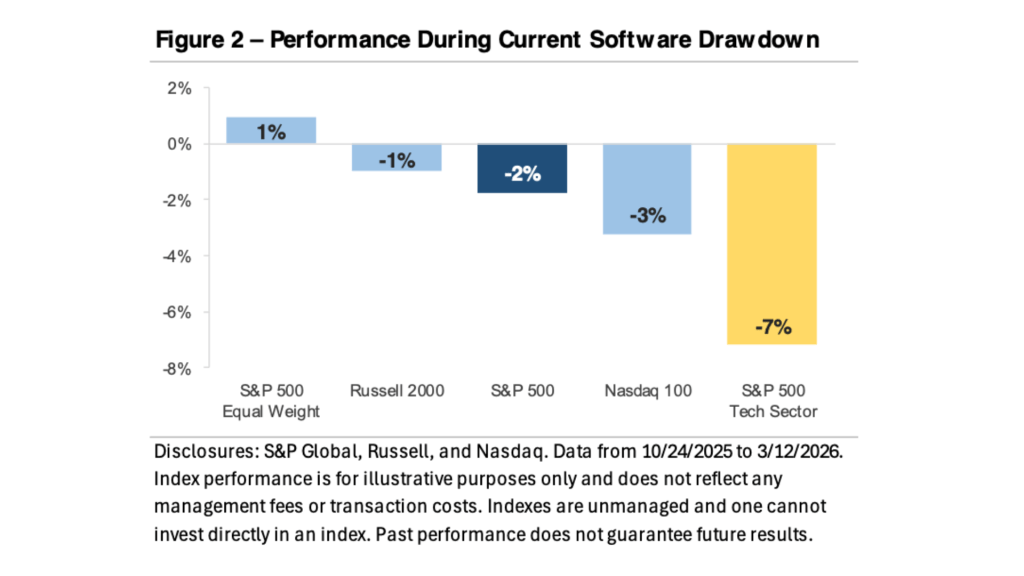
At the same time, this period has also been a useful reminder of why diversification works. The pressure has been meaningful in some concentrated parts of the market, but much more limited for diversified investors. International stocks and the average S&P 500 stock have posted gains, while small caps, the broader S&P 500, and the Nasdaq 100 are each down only modestly.
That does not remove uncertainty. But it does reinforce an important principle.
A disciplined portfolio is built not just for the trends we expect, but for the leadership changes we do not. And in an environment like this, diversification across sectors and asset classes remains one of the most practical ways to manage risk without losing sight of long-term goals.
Mega Backdoor Roth Might Not Be Your Biggest Tax Problem
You've worked hard to build a sizeable retirement account. Now you’ve heard about a strategy called the mega backdoor Roth, and it sounds like the next smart move.
Maybe it is, but before you redirect another dollar, there's a question worth asking first, “is where you put your next dollar actually your biggest tax problem?”
For a lot of people I work with, the answer is no.
What the Mega Backdoor Roth Actually Does
Here's what I mean. The mega backdoor Roth is a legitimate tax planning tool. That’s because it allows you to contribute after-tax dollars to a 401(k) and then convert those dollars into a Roth account, creating a larger pool of money that can grow tax-free. For the right person in the right situation, it is absolutely worth pursuing.
But the strategy is often discussed in isolation, as if the only question on the table is where to put new savings. And for people who already have large pre-tax balances sitting in traditional IRAs or old 401(k)s, that framing misses the real issue.
The real issue is what’s already in the account.
The Hidden Tax Burden Inside Your Pre-Tax Retirement Accounts
How so?
Well, when you contribute to a traditional IRA or a pre-tax 401(k) over a thirty-year career, you build up a balance that feels like wealth because it is wealth. But it is wealth with a tax bill attached to it, and that bill does not come due until you start taking money out.
And for most people, that moment arrives in retirement, either by choice or by requirement. The IRS calls those requirements RMDs, or required minimum distributions, and they begin at age 73. At that point, the government sets a minimum amount you must withdraw each year whether you need the income or not.
This is where large pre-tax balances can quietly become a tax problem in disguise.
How RMDs Can Increase Your Tax Burden in Retirement
As those balances grow over time, the RMDs attached to them grow too. And when you layer those distributions on top of Social Security, a pension, or other retirement income, you can find yourself pushed into a higher tax bracket than you expected.
If that’s not enough, it can get even more complicated. Higher taxable income in retirement can trigger IRMAA surcharges, which are income-based adjustments to your Medicare Part B and Part D premiums.
It can also affect how much of your Social Security benefit is subject to tax and ultimately, it can reduce your flexibility to make smart financial decisions, because so much of your income is no longer optional.
So then, when someone with a seven-figure traditional IRA asks me whether they should pursue a mega backdoor Roth for their new savings, my honest answer is this that the strategy might help at the margins, but it is not addressing the source of your future tax pressure.
It’s putting a fresh coat of paint on a house that needs foundation work.
Why Partial Roth Conversions May Deserve Greater Priority
So what’s the solution here?
Well, the strategy that deserves more attention in situation with high balance pre-tax accounts is the partial Roth conversion. Rather than focusing only on where to direct new dollars, a partial conversion takes money that already exists in a pre-tax account and moves it into a Roth account.
You pay the tax today, at a rate you can plan around, and in exchange you reduce the size of the account that will generate mandatory distributions later.
When done thoughtfully over several years, especially in the lower-income years between retirement and when RMDs begin, a Roth conversion strategy can meaningfully reduce your future tax burden and give you back flexibility you did not know you were losing.
How to Think About Both Strategies Together
Here’s the key takeaway: the mega backdoor Roth still has a place in this conversation.
If you have the cash flow to fund it and you have already addressed the larger pre-tax balance issue, positioning new savings for tax-free growth is a smart move.
But it is a second step, not a first one.
The bigger point is that tax planning in retirement is not just about optimizing where you put your next dollar, it’s about understanding the full picture of what you have already saved and what that savings will cost you when it comes out.
And the best time to address that future tax liability is before it becomes unavoidable. If your pre-tax balances are growing faster than your plan accounts for, that conversation is worth having now.
Market Update: Geopolitical Tensions & Your Financial Plan
Given the deeply concerning headlines about the conflict in the Middle East, I imagine this is a time of worry for you as it is for many.
While the violence and loss of life is distressing, I want to reassure you that your financial plan is designed to weather turbulence, and I’m watching the situation closely on your behalf.
There are still many open questions about how the geopolitical situation will unfold, and near-term market volatility is likely amid the uncertainty.
Some Historical Context
However, in times like these, the chart below offers important historical context in that the U.S. has navigated many challenging periods in the past, so staying focused on your long-term plan is critical.
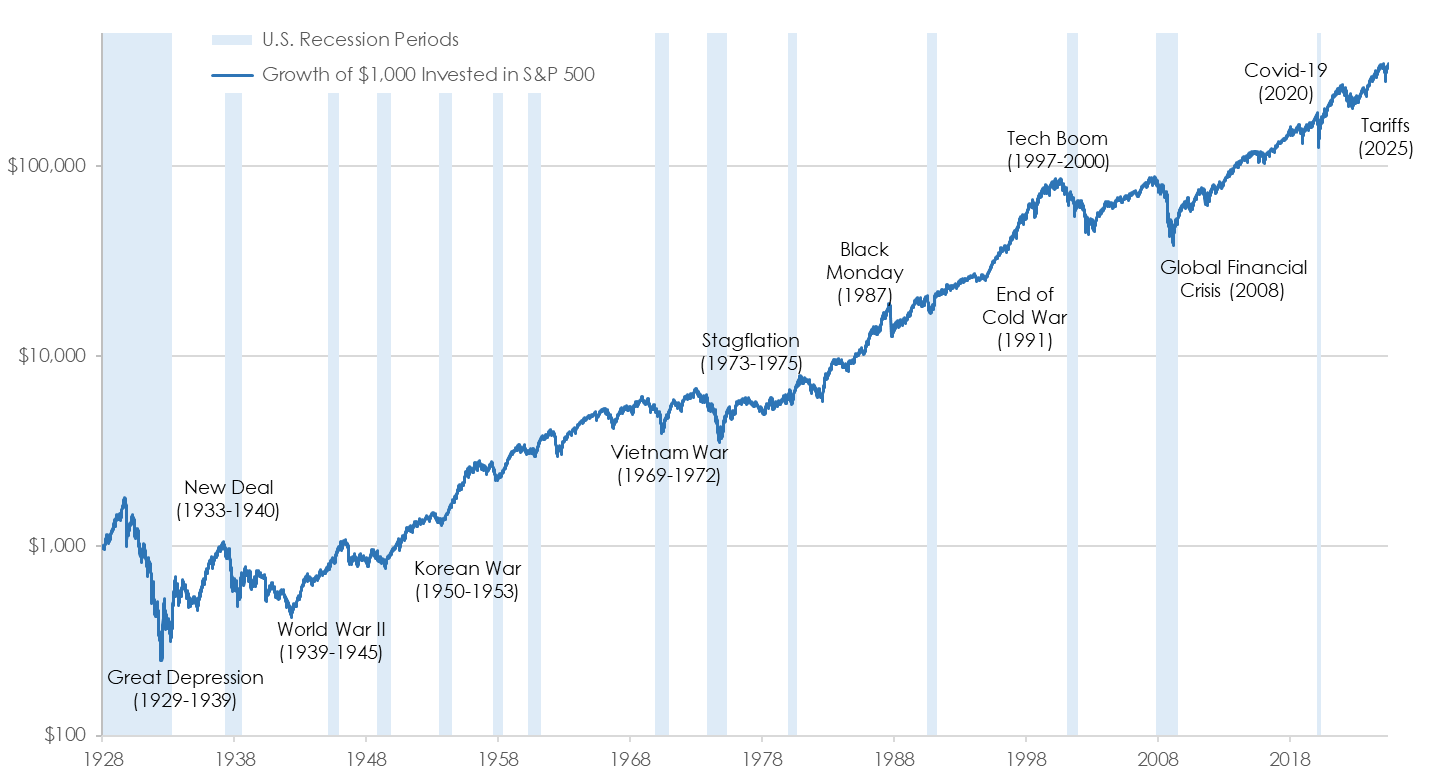
Indeed, history has shown the wisdom of sticking to your investment discipline and not overreacting to short-term events, difficult as that can feel in the moment.
What to Do Next
As a next step, I would recommend reviewing last week’s email (see link below) because the key takeaways bear repeating:
- Maintain your long-term asset allocation and diversification
- Keep appropriate cash reserves so you're not pressured to sell at bad times
- If needed, we can discuss adjusting your spending temporarily to relieve stress
https://franklinmadisonadvisors.com/cio-corner/market-volatility-heres-what-to-do-about-it/
Rest assured, if I’ve personally worked on your plan with you, your portfolio is built to withstand choppy markets, and we are monitoring developments diligently and ready to make prudent adjustments if warranted.
If You Still Need Help
Ultimately, I'm here as a resource and sounding board for you.
Please don't hesitate to schedule a quick call or reply to this email with any specific questions or concerns you have, I'm happy to talk things through and revisit any details of your plan so you can feel more confident.
While the macro situation is troubling, I have deep faith in the resilience of our country and economy. We will get through this, and I remain optimistic about the long-term future.
Market Volatility – Here’s What to Do About It…
After what feels like nearly a year of markets going straight up, even a modest pullback can feel like a personal hit.
One week you’re checking your account balances with a little extra confidence. And then the next week, when risk assets are sliding and headlines are loud it can feel like the mood shifts fast, right?
So here’s the real question: Should you be worried about market volatility, or should you be expecting it?
Why volatility feels worse after a long rally
Well, while I can tell you that market volatility is a natural part of any market cycle, you’re likely to feel differently these days.
That’s because when markets grind higher for months, we get used to it. That steady climb starts to feel normal and it starts to feel earned.
And when the market finally takes a breather, it can like something broke and make you want to put your money into something “safe”.
The fact is, however, that markets do not move up in a straight line, even when the market and economic backdrop is strong. To be sure, routine pullbacks are part of healthy markets, and part of what keeps longer-term uptrends from overheating.
Even so, minor pullbacks could feel like a sign of a bigger impending move for some individuals.
So, what do you do if you’re feeling this way?
Well, the first step is a simple reframe.
Why this pullback feels different: AI disruption and shifting leadership
Indeed, one reason this bout of volatility feels so intense is that it isn’t only about prices. It’s also about narratives, or the stories that drive market behavior.
Lately, markets have been reacting sharply to AI-related news, including concerns that rapid innovation and shifting leadership can pressure yesterday’s winners and accelerate competitive disruption.
For example, law professionals used to rely on expensive software to give them an edge in their practice. Today, AI can do what the attorneys and software do at a fraction of the cost.
This matters because investors often underestimate how quickly a “winner” stock can turn into a “why is this selling off?”
Because here’s the thing: AI is not merely a theme. It’s a force that can reshape profit pools.
What seemed like an mere augment to business processes is now demonstrating, in real-time, how quickly the innovation can displace earnings potential in more legacy parts of the tech industry.
And when that happens, the market rarely reprices politely over years. More often, it reprices in weeks. And that volatility is what we’re seeing today.
So yes, news about AI being disruptive, including to seasoned incumbents, can absolutely be a catalyst for volatility. The risk is not that the AI story disappears.
The risk is that markets get ahead of themselves, timelines disappoint, competition shows up faster than expected, and leadership rotates while investors are still anchored to the last set of winners.
Nevertheless, time and time again, markets have shown how quickly sentiment can change when the market decides the future arrived sooner than expected.
Markets participation is broadening, and that's not a bad thing
There’s another dynamic worth paying attention to and that’s that market participation is broadening, even as the overall indices chops around.
In other words, it isn’t just the same ten stocks pushing the markets higher. Lately, investors are paying more attention to broader areas of the market, which is a theme we’ve highlighted in recent months, including meaningful moves in small caps.
Now, broadening isn’t a bad thing because it can be a sign of a healthier market structure. But, it does comes with a tradeoff.
That’s because when leadership rotates and participation broadens, dispersion increases. In other words, some sectors rally while others stall out or drop. And this increased disparity can make the market feel more volatile even if the index level does not look dramatic.
So, if you’re looking at your portfolio and thinking, “Why does this feel worse than the headlines suggest?” it’s because the market movements more uneven these days.
The cycle is later, but that does not mean recession is imminent
Another reason we’re likely seeing more market volatility is that we’re likely later in the economic cycle.
Indeed, the latest read on fourth quarter GDP and softening labor market data suggest that economic growth is slowing. This is leading to more economic surprises and frankly, markets are more sensitive to surprises than they were earlier in the cycle.
But “late cycle” does not automatically mean “recession is imminent.”
To be sure, in one of our previous reports, we described an environment where growth remained positive even as the economy softened, with the narrative focused on slowing without slipping into recession.
We have also framed the current data backdrop as modest economic growth, while acknowledging that policy mistakes could change the path.
So yes, the cycle is later.
But the base case is still slower growth, not collapse.
How often does volatility happen?
So then, should we be worried about volatility?
Well, once you understand the frequency of market moves, you’re more likely to stop treating volatility like an emergency.
Because the fact of the matter is that pullbacks happen a lot.
Indeed, in our published work last year, we noted that market dips around 3% have historically happened about seven times per year on average, and declines of 5% or more occur roughly three times annually.
That didn’t happen in 2025.
So, if you’ve felt like you’ve been living through a year with no pullbacks, you’ve been waiting for something that simply feels like it does not show up very often.
Zoom out even further and the point gets even clearer.
For example, in our 2Q25 market update, we shared that since 1928 the S&P 500 has experienced an intra-year decline of at least 5% in the vast majority of calendar years, with the median intra-year drop around 13%.
So volatility is not rare, it’s routine.
The truth is that big down days are rarer, but they still get the headlines.
And that’s the trap, isn’t it?
The scary days are memorable. The normal days are forgettable. And the market uses that to mess with your confidence.
Because the truth is that corrections are not an “if,” they’re a “when.”
When it comes down to it, some investors like a clean framework like, “Markets are due for corrections every 18 to 24 months.”
Whether you like that cadence or not, the core conclusion holds either way.
Smaller pullbacks happen multiple times per year. And, history has shown that a 5% drawdown typically happens in almost every calendar year.
So the takeaway is straightforward: Corrections are not an “if,” they’re a “when.”
What do we do when uncertainty shows up?
So what should you do when market volatility picks up? Well, this is where most investors go wrong.
They spend most of their energy trying to predict what happens next instead of focusing on what they control.
And the one thing you can control is whether you react or respond.
#1: Stick to Your Discipline
Because in moments like this, the winning move is often boring. It’s about sticking to a disciplined investment strategy.
It’s staying diversified.
It’s staying committed to a process built for markets that occasionally misbehave. It’s dollar cost averaging into your portfolio and rebalancing regardless of what the markets are doing.
It’s a point we have made consistently in our updates, including the idea that trying to sidestep volatility through timing can mean missing the best days in the markets, potentially costing you thousands, while staying invested gives compounding room to work.
#2: Review Your Cash Management Process
The other thing you can control is whether you are forced to sell investments at an inopportune time.
That’s where cash management comes in.
The simplest way to avoid panic-selling is to remove the need to sell. Indeed, over the years, we’ve reinforced the use of a cash as a buffer to help you avoid selling at the wrong time, and holding cash reserve ranges that are often appropriate depending on whether you’re working or approaching retirement.
It’s about creating your “sleep-well number,” or the level of cash that lets you stay committed to your strategy when headlines get uncomfortable.
#3: Stick to Your Plan
And finally, you can control how well you’re sticking to your broader financial plan when markets start to feel uncontrollable.
Keep doing the work outlined in your plan, because we’ve already planned for moments like these.
In the short term, markets can feel like a voting machine. In the long term, they act more like a weighing machine.
Pullbacks help reset expectations, cool overheated parts of the market, and set the stage for future gains.
Historically, markets have recovered over time, even through major crises.
So the question is not, “Will this feel uncomfortable?”
It will.
The better question is, “Do I have a plan that assumes discomfort shows up from time to time?”
Bottom line
Should you be worried about market volatility?
Not if you’re prepared for it.
Because the fact is that volatility l is not a surprise guest, it’s part of the ticket to achieving your long-term goals.
So if you’re feeling unsettled right now, then it’s time to get back to the basics. That involves staying disciplined, knowing your sleep-well cash number and keeping your focus on the long-term plan.
That’s how you move through uncertainty without letting it drive the bus.
Here’s What to Make of Recent Headlines
It is hard to think about investing, planning, and the future when it feels like the social fabric that has held this country together is fraying in real time.
If you have found yourself distracted, unsettled, or even angry by the headlines around immigration enforcement, you’re not alone. Recent reports over the past few weeks have left a lot of Americans asking, “what’s happening to us?”
And yet, it’s tempting to shrug and say, “This is politics, it has nothing to do with my retirement plan.”
However, this time, I don’t agree.
Not because every headline turns into a market event because most headlines don’t.
It’s because the issues underneath these headlines touch on two things markets care deeply about, and that’s trust and stability.
When trust and stability are strong, capital flows in. When trust and stability are questioned, however, investors begin to demand a higher price for taking risk.
Sometimes that shows up as higher borrowing costs, sometimes it shows up as more volatility and sometimes it shows up as both.
Ultimately, the headlines could be a symptom of a broader trend unfolding, so here’s what I’m watching.
Two channels I am watching
First, it’s crucial to note that the United States is a premier destination for global capital.
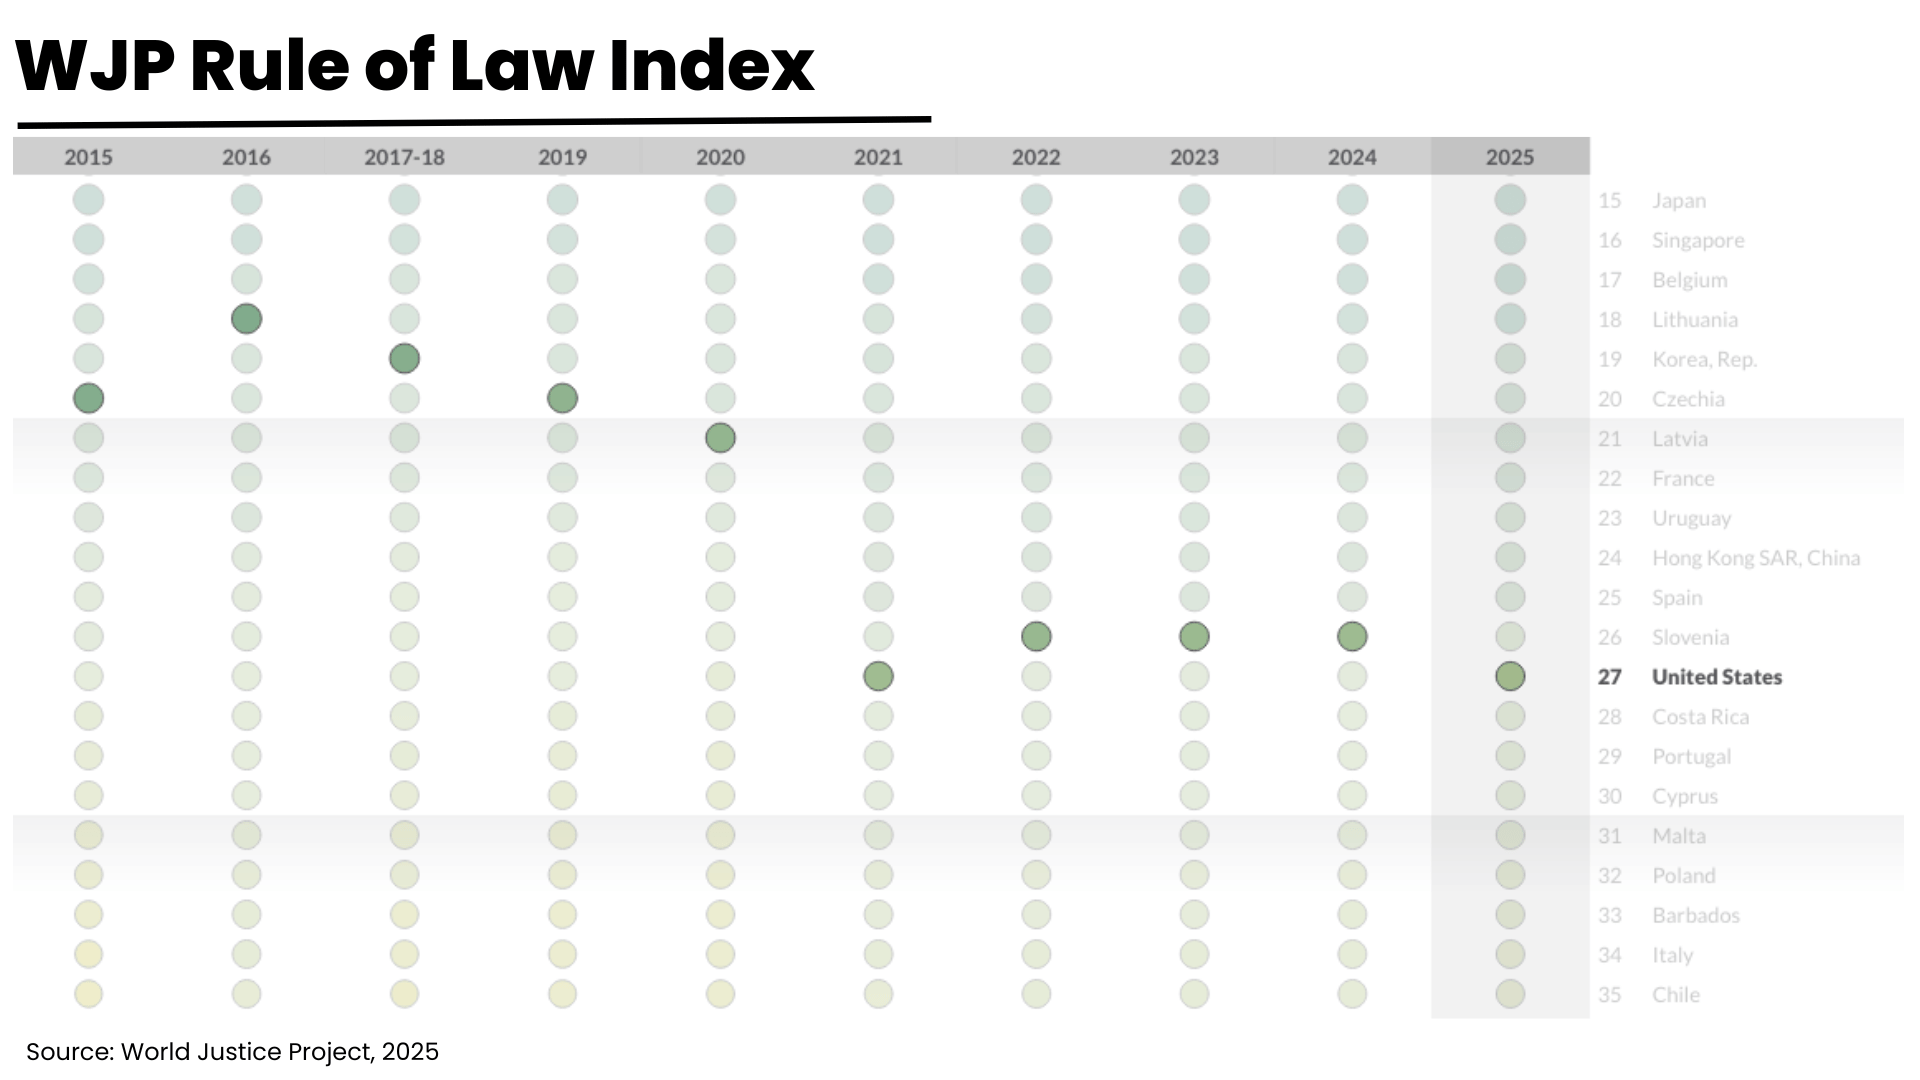
And one of the quiet advantages the U.S. has had for decades is not simply innovation or scale, it’s governance and rule of law.
It’s the idea that rules apply consistently, contracts are enforceable, and institutions are resilient. That rules-based order is part of why global investors have been willing to allocate so much money here, even when our politics are loud.
That’s also why perceptions matter because markets don’t need perfection, they need confidence that the basic institutional guardrails will stay in place.
Watching the Fed
A good example is what’s happening with the Federal Reserve.
The Fed’s credibility has always rested on independence, and the belief that policy decisions are aimed at long-term stability, not short-term political goals.
With that said, as leadership transitions approach, it is reasonable for investors to pay closer attention to whether that independence looks protected or pressured. That’s because even the perception of shifting incentives can change how the world prices U.S. assets.
The other example is rule of law. And what do we mean here by rule of law?
Well, it’s the difference between “I own this asset” and “I own it until someone with power decides otherwise.”
Throughout my career, this has been one of the key risks we evaluate when looking to invest in emerging markets or politically unstable regions. Until recently, it has not been a risk most investors felt they had to price heavily in the United States.
Now, it’s starting to change, even at the margins.
Because when headlines start to raise questions about fundamental rights, due process, and institutional constraints, that’s the sort of thing global capital markets pay attention to.
Not instantly, and not always dramatically, but it’s the kind of thing that makes global investment policy committees sit up and begin reviewing their asset allocation decisions.
The Impact on Prices
The second thing I’m watching is how today’s events impact the economic structure behind labor, growth, and prices.
This is a longer-term trend, to be sure, but the seeds being planted today, if not mitigated, could be of consequence years down the line when it matters most in retirement.
Because here’s the thing: What has made America exceptional for so long is that people have been willing to come here, work, build, and contribute to build a new life.
That is the American story, whether your family arrived centuries ago or last generation.
And so, if the U.S. becomes a less attractive destination for legal immigration, then the economic consequences, like labor shortages, don’t stay contained, they could naturally flow into the prices we pay for goods and services.
You can see the contours of this development already unfolding.
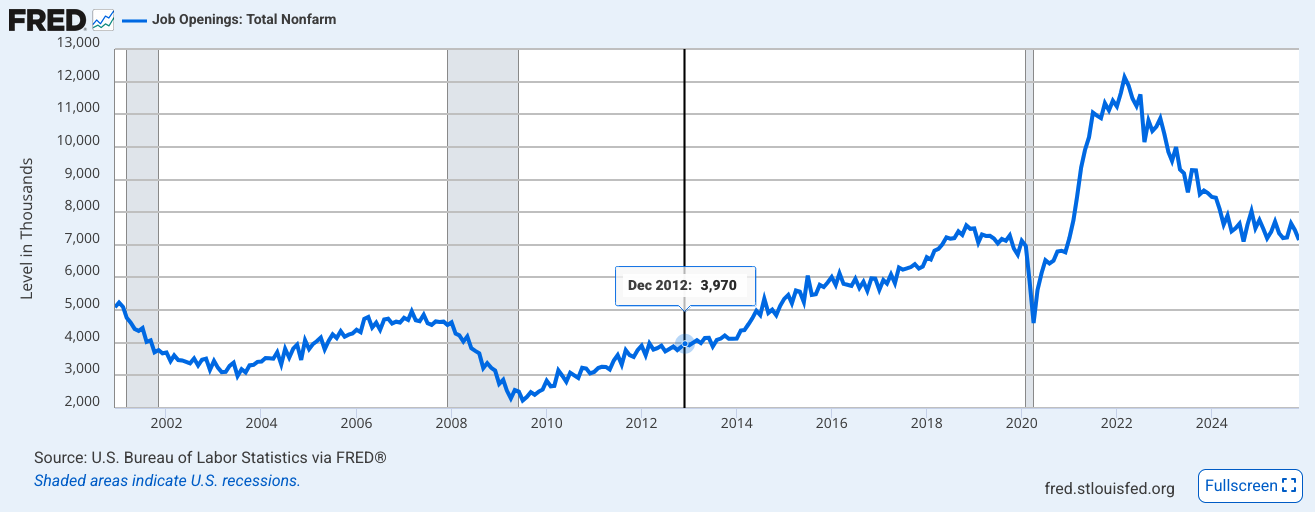
Indeed, industries that rely on skilled labor and steady hiring pipelines, like construction, healthcare, and engineering, are sensitive to labor disruption. Add uncertainty for workers on legal pathways, including work visas and student visas, and you risk shrinking the pool of talent over time.
Yes, automation will keep advancing. And AI, robotics, and process improvements will absolutely offset some labor pressure.
Still, there are many jobs where a human eye and a human touch are not optional, at least not yet. If labor supply tightens faster than technology can replace it, the effect is that costs rise.
That is the simplest economic math on the board.
In practical terms, that could mean higher prices in areas that already feel stretched, including food, housing-related labor, and medical services. It could also mean inflation settling at a higher level than the 2% world many retirement models quietly assume.
So what does this mean for your plan?
It’s essential to note here that I don’t say any of this to be dramatic. I say it because looking away is not a strategy. Ignoring reality is not a plan.
If institutional stability is eroded, you could see a world where markets demand a higher risk premium for U.S. assets. And that could translate into lower valuations, more volatility, and higher interest rates than people expect.
And if labor constraints persist because determined, talented individuals are less interested in coming to the United States, well, you could see a world where inflation runs hotter for longer, which might raise your long-term cost of retirement.
Taken together, both of those outcomes matter because they touch the growth of your assets and the purchasing power of your withdrawals.
The good news is that our planning work is not built on best-case assumptions.
We already model conservative growth rates and higher inflation because surprises are not rare, they are the norm.
So then, in moments like this, the question is not “can we predict what happens next?”
But rather, the question should be “is my plan built to endure a range of outcomes, including uncomfortable ones?”
That’s what we will keep focusing on.
What can you do right now?
We can’t control the headlines.
However, we can control how prepared we are for the changing developments.
At this moment in time, it’s worth paying attention to, even if it’s uncomfortable.
Because the things that feel distant, political, or abstract can become personal through our portfolios, prices, job markets, interest rates, and the stability of the institutions we all rely on.
If you have questions about how this environment could affect your plan, now’s a good time to revisit assumptions, stress-test scenarios, and make sure your strategy matches the world as it is, not the world we wish it were.
Weekly Market Recap: Ceasefire, Oil Reversal, and the Rally Markets Were Waiting For
Stocks traded higher for a second consecutive week as de-escalation triggered the strongest single day rally in a year. The S&P 500 gained +3.7%, with the Nasdaq and the Russell 2000 both returning +4.3%.
Most of the rally occurred on Wednesday after the announcement of a two-week ceasefire contingent on Iran reopening the Strait of Hormuz. Oil plunged -11%, the VIX dropped below 20, and international stocks rose as energy-importing nations benefited from the oil reversal. Industrials were the top-performing sector, gaining +5%, with broad strength across most sectors excluding energy.
Treasury yields fell modestly, and corporate bonds outperformed as credit spreads tightened to late January levels. However, the ceasefire was already being tested late in the week, with the market closely monitoring this weekend’s talks.
Key Takeaways
The U.S. and Iran agreed to a two-week ceasefire, triggering a relief rally.
Late Tuesday, the White House announced an agreement contingent on Iran reopening the Strait of Hormuz, less than two hours before a stated deadline to launch strikes on Iranian infrastructure.
Markets reacted decisively Wednesday: the S&P 500 surged +2.5%, its best single-day gain in a year, the Dow jumped +2.9%, the Russell 2000 gained +3.0%, and international equities rallied +3.5%. Unlike prior headlines, this was an actual agreement confirmed by both sides, with talks scheduled for this weekend.
Implication: The ceasefire is meaningful, but its durability was tested within hours. Israel launched strikes across Lebanon, Iran accused the U.S. of violating three conditions, and the Strait remained effectively closed Thursday morning. This weekend's talks will determine whether the agreement marks a turning point.
Oil plunged -16% on Wednesday, its largest single-day decline since April 2020, as the market priced in a Hormuz reopening.
WTI fell from $112 to around $94, erasing weeks of the war-driven rally that had pushed oil up over +65% YTD. The decline triggered immediate secondary effects: airline stocks surged, and the odds of a rate cut increased as inflation expectations eased.
However, the physical reopening remains uncertain. As of Thursday morning, the Strait was still effectively closed, and oil was moving back toward $100.
Implication: Oil is the transmission mechanism through which the conflict reaches inflation, the Fed, consumers, and corporate profits. Wednesday's decline showed how quickly the geopolitical premium can unwind, with the market watching for actual follow-through.
Credit spreads tightened and volatility declined, confirming the risk-appetite shift across asset classes.
High-yield spreads compressed during Wednesday's ceasefire rally and are now the lowest since late January after tightening nearly -0.50% over the past two weeks. Credit spread tightening is an indication the market is starting to price in less stress.
The VIX fell to 21, its first close below 22 since late February, after touching 28 intraday Tuesday before the ceasefire was announced.
Implication: Credit and volatility are the market's most reliable stress indicators, and both confirmed the equity rally as broad-based rather than speculative.
Treasury yields barely moved despite the ceasefire rally.
The 10-year yield fell just -0.03% to 4.28%, a muted response given the magnitude of the oil crash and equity rally. The bond market's reaction reflects the Fed's policy forecast. Seven of nineteen Fed members forecast zero cuts in 2026, and the Fed's March minutes, released this week, reaffirmed its patient approach.
Implication: The bond market's restraint suggests it is waiting for confirmation that the ceasefire will meaningfully improve the inflation and growth outlook.
Next week unofficially kicks off Q1 earnings season, with the big Wall Street banks reporting.
The focus will extend beyond the usual revenue and earnings beats to management commentary on the conflict's impacts, from energy costs and supply chain disruptions to consumer demand and forward estimates.
Implication: Earnings calls will provide the first corporate read on how the energy shock is flowing through margins, pricing, and demand. Forward guidance and tone may matter more than the headline numbers this quarter.