Here's How Retirement is an Endurance Sport
In many ways, retirement isn’t a goal, it’s an endurance sport.
I had the opportunity to compete in the Pittsburgh Marathon over the weekend and wanted to share a quick thought that came to me during the race:
To run the race, you not only have to train, but you’ve also got to be able to adapt your plan to uncontrollable conditions on race day.
We’ve often been led to believe that retirement is a singular destination, that all you need to do is show up at the starting line with the right-sized nest egg, and you’ll be set.
The reality is, however, that you have to prepare not just to be able to show up for race day, but also to sustain yourself along the way.
It’s not just about putting in the miles to go the distance; it’s about pacing, nutrition, hydration and attitude.
In retirement, pacing becomes your spending plan. Nutrition and hydration represent efficiently growing your wealth and protecting it. And your attitude? That’s staying disciplined when markets and life throw challenges your way.
A misalignment in any of these components is likely to fundamentally change your race day experience.
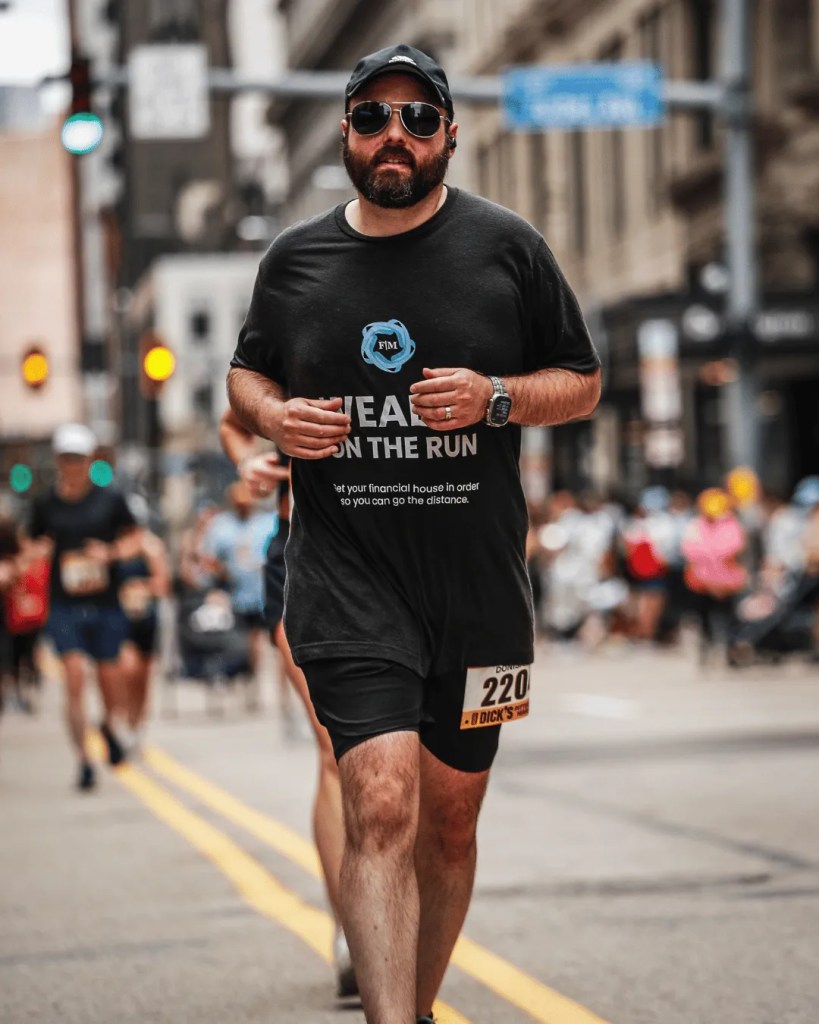
Heading into my taper week ahead of last week’s race, I felt like my training was solid and was certain that by race day, my body and legs would be fresh. But wouldn’t you know it, I woke up on Sunday morning with a cold and a case of bronchitis.
That’s the paradox of endurance training: you can’t control the conditions, but it does equip you to press through them.
You change and test the variables weeks in advance so you know how your body might adapt to the unknown stresses of the event.
And once you’ve trained for an endurance sport, you’re likely forever changed.
Because more often than not, you haven’t prepared for a single race; after months of deliberate effort, you’ve forged a new way of life.
Many people believe retirement planning is about maintaining their current lifestyle for the next 20, 30 or 40 years. But the right plan doesn’t just preserve what you have, it expands your horizons. It equips you to live a lifestyle you may not have envisioned before, opening the door to entirely new races you hadn’t even considered.
You see, retirement success isn’t about reaching a single milestone.
It’s about having the right habits, resources, and mindset to keep going strong over the long run no matter where your journey might take you, even under the least optimal conditions.
Frankly, the conditions presented to me on my race day were certainly less than optimal. In the end, I finished the race, but not in the way I had hoped. Even so, my planning and training enabled me to envision an outcome (finishing the race) beyond current circumstances (illness).
Whether you’re already executing your retirement plan or still fine-tuning it, it’s worth asking: do I have the right systems, support, and strategies in place to thrive mile after mile no matter what life throws my way?
Humble Brag
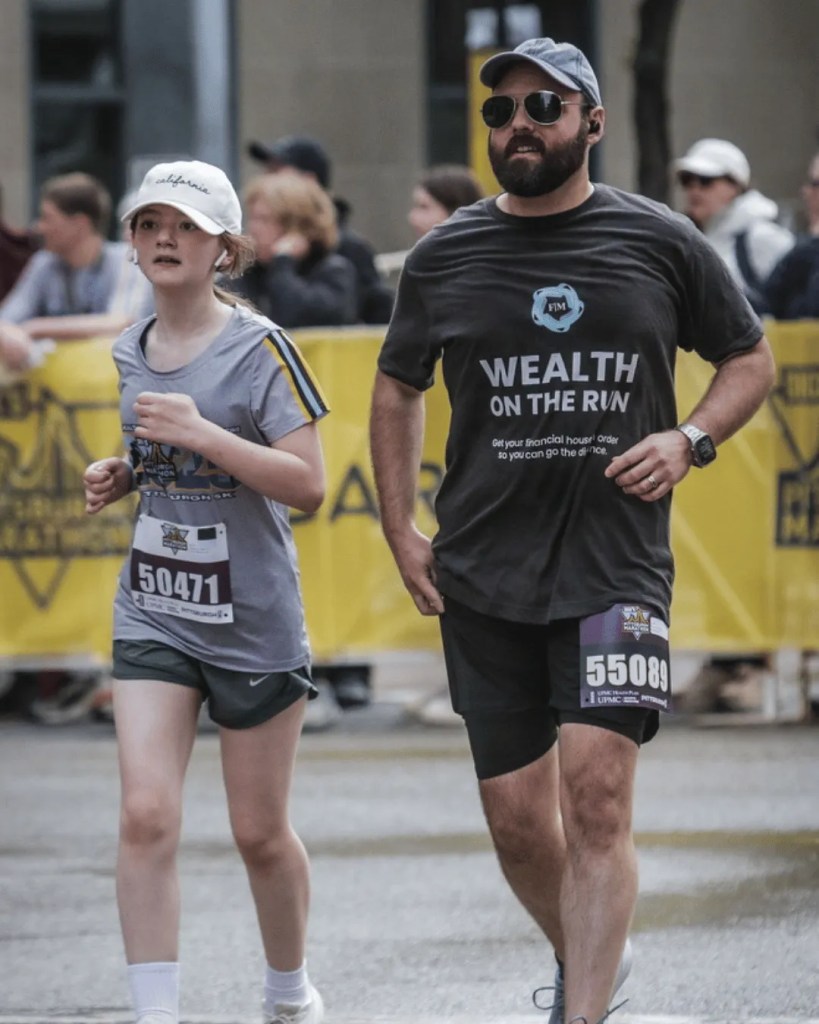
I had a proud-dad moment this weekend as my oldest, Lily, ran her first timed 5K.
It wasn’t about speed or competition, it was about building grit.
We laughed, we cried, and ultimately, we crossed the finish line together.
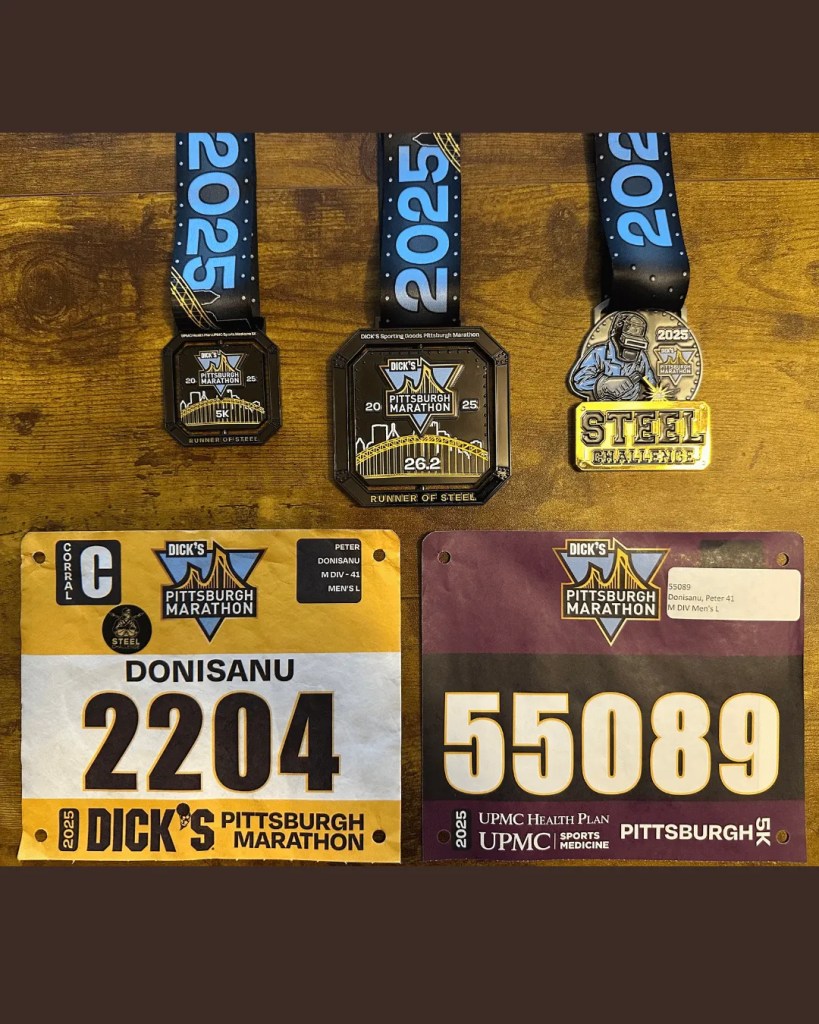
Here’s to the first of many more races we’ll run side by side in the years to come.

What to Make of Weaker First Quarter Growth?
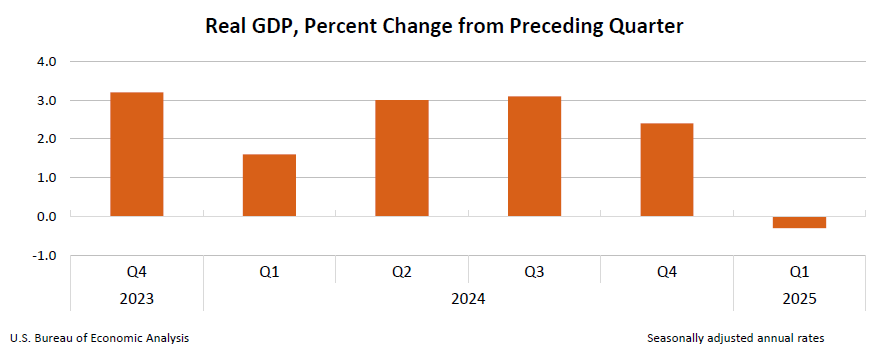
Last week, incoming data showed that the U.S. economy shrank in the first quarter of 2025, the first time in several years we've seen this happen.
Now, it's essential to note that one quarter of decline doesn't mean a recession is inevitable. But with today's unpredictable economic policies, it's fair to wonder if this could be the beginning of a short-term slowdown.
Why Predicting the Economy Is Harder Than Ever
Indeed, trying to figure out where the U.S. economy is going has never been easy. But in the years since the pandemic, it's become even more difficult.
That's because many of the tools economists used to rely on don't seem to work as well anymore. For example, when interest rates rise, that usually signals a slowdown or even a recession in the making.
But in the past five years, even with warning signs in place, Americans kept spending. And since consumer spending makes up over two-thirds of the U.S. economy, this has helped keep things growing.
So, what's changed?
Well, what's likely different this time around is the policy environment. We're dealing with a new set of economic rules and decisions that make predictions more complicated.
And these changing policies create more uncertainty, and that can weigh on both consumers and businesses. Because of this, the chances of a recession, or at least slower growth, may be rising as these policy effects ripple through the economy.
What Caused the First-Quarter Economic Decline?
So then, to better understand what's behind the recent slowdown, we need to look at the key parts of economic growth.
And as you'll likely recall from your economics courses in college, gross domestic product (GDP) is made of: 1) government spending, 2) business investment, 3) household spending, and 4) net exports (exports minus imports).
So, what did the data show us?

Well, in the first quarter, two things stood out as the leading causes of weaker growth: a drop in government spending and a sharp increase in imports.
Now, the rise in imports likely happened because of the Trade War, as businesses and consumers were trying to buy goods before prices increased.
To be sure, as trade tensions have returned, and tariffs on some items are now as high as 150%, that's led many to act early, stocking up before things get worse.
Now, the drop in government spending is more complicated.
That's because overall federal spending is still higher than in past years, but when adjusted for inflation and measured quarter by quarter, it appeared to fall. That technical dip was enough to drag down total economic output.
What the Numbers Don't Tell Us
While hard data like GDP shows us what already happened, it's also essential to pay attention to soft data, like how people and businesses are feeling about the future. This kind of information can help predict what's coming next.
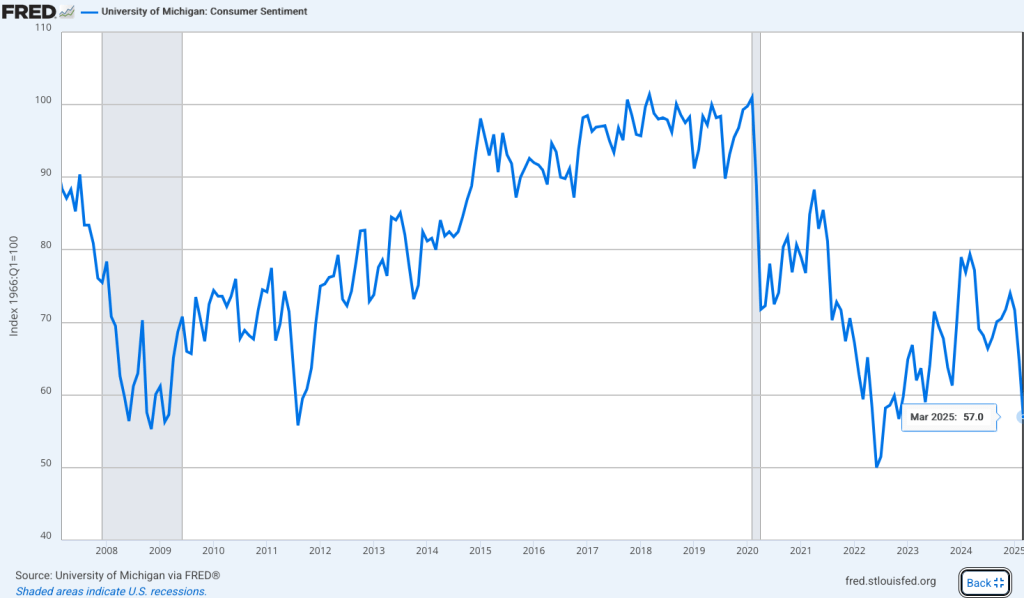
And lately, people haven't been feeling very confident. For example, a recent University of Michigan survey showed consumer confidence hit its lowest point in two years. A lot of that concern comes from worries about inflation and what future policies might bring.
We're also seeing changes in the job market. That's because data are showing there are fewer job openings, and layoffs are becoming more common. These are signs that employers are starting to pull back, something that often happens toward the end of an economic cycle.
And adding insult to injury, even shipping activity has slowed. At major ports on the West Coast, freight volumes have dropped, showing that businesses may be holding off on orders as they wait to see how trade issues unfold. All of this points to a more cautious mood taking hold across the economy.
The New Trade War: What's Changed?
Another factor adding pressure to the economic outlook is the return of Trump's Trade Wars.
But this time, businesses are handling the tariffs in a much different way than they had during Trump's first administration.
That's because, during the first trade war in 2018, many businesses chose to absorb tariff costs to keep their customers. But now, more of them are passing those costs directly to shoppers.
That makes everything more expensive, and if prices keep going up, people may start spending less. If trade problems continue, and if businesses and consumers respond by cutting back, it could create a chain reaction that leads to even slower growth.
So, Are We Heading for a Recession?
Nevertheless, it's too soon to say for sure whether we're heading for recession. Frankly, one quarter of economic decline is not enough to call for a slowdown, particularly when the factors could be temporary.
Indeed, even experienced economists often struggle to predict when a recession will hit.
But one thing is clear: today's policy environment isn't helping. And ongoing uncertainty about trade, inflation, and regulation has made people and companies more cautious about spending and investing.
If that uncertainty doesn't clear up soon, the risk of economic weakness and higher prices will likely grow.
In times like these, it's easy to get distracted by scary headlines or market swings. But this is precisely why having a strong financial plan matters.
When things feel shaky, your plan should be your guide.
Now is not the time to make big changes out of fear. Instead, lean on the thought and strategy that went into your long-term plan.
That kind of discipline is what helps you stay on track, especially when the road ahead feels uncertain.

2Q25 Market & Economic Update
Fear and uncertainty are two prevailing themes that emerged as we closed out the first few months of the year.
After a strong start to the year that saw the S&P 500 hit an all-time high in February, markets took a breather as policy uncertainty emerged.
And as winter turned to spring, so did investor sentiment. Concerns about rising policy uncertainty in Washington weighed on the market, and the S&P 500 ended the quarter on a lower footing.
While it’s natural to feel uneasy during a market pullback, it’s important to keep perspective. Markets go through cycles, with some driven by optimism, and others by caution. In this update, we’ll recap the first quarter, explain what’s behind the recent selloff, and share our view on where the economy may be headed.
There are a lot of moving pieces in play, and that can make headlines feel overwhelming. But with a solid financial plan in place, these moments of market stress can become easier to navigate. Our goal with this update is to help you focus on what matters most: making informed decisions that support your long-term financial wellbeing.
Stocks Trade Lower as Valuations Moderate
One of the biggest developments in the first quarter was a reset in stock valuations. What this means is that investors carefully evaluated how much they were willing to pay for a dollar of a stock’s earnings.
And while corporate earnings expectations held relatively steady, investors became more cautious, especially as policy uncertainty increased. As a result, stocks fell and not because profits disappeared, but because investors were less willing to pay top dollar for those expected profits.
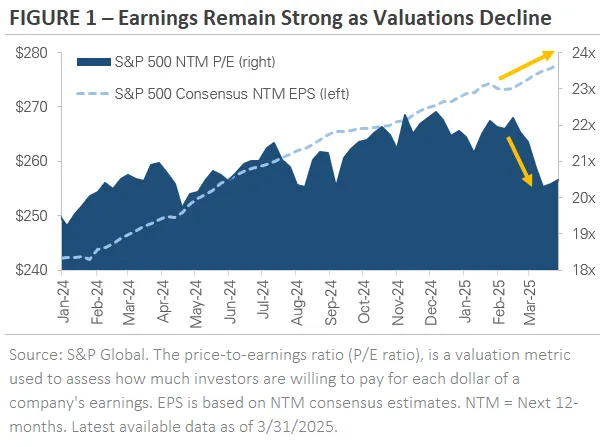
Figure 1 provides helpful context. The dashed blue line shows Wall Street’s 12-month earnings forecast for S&P 500 companies. In contrast, the navy shading illustrates the market’s price-to-earnings (P/E) ratio, or how much investors are willing to pay for each dollar of earnings.
Historically, earnings estimates are less volatile than investor sentiment, and the chart shows that pattern continuing this quarter.
And so, during the first few weeks of 2025, optimism prevailed. But as headlines around tariffs and shifting policy agendas emerged, that optimism gave way to caution. Investors recalibrated their expectations, and valuations declined, falling from over 22x earnings to around 20x.
Now, while that may seem like a small adjustment, it had an outsized impact on stock performance. In short, markets got cheaper, even though company profits stayed largely intact.
Another theme that emerged this quarter was centered around company size. Last year, the so-called "Magnificent 7" of Nvidia, Microsoft, Alphabet, Amazon, Tesla, Apple, and Meta, soared, lifting the broader S&P 500 by +23%.
This year, those same companies are pulling the index lower, down about -15% as a group. Meanwhile, smaller companies within the index are holding up better. For example, the equal-weighted S&P 500, which gives every company the same influence regardless of size, is down just -1%.
What this means for you: The market’s recent dip has more to do with investor mood than economic fundamentals for the time being. This view could change should policy missteps lead to a broader economic decline. Nevertheless, during this period of uncertainty, it’s essential to remember that your portfolio is built to weather these kinds of shifts, and to take advantage of opportunities when they arise.
Rising Policy Uncertainty is Impacting Sentiment
So, why exactly is policy uncertainty so important? Well, as households and business become less certain about the future, they tend to spend and invest less as well. And one of the main drivers behind this quarter’s market pullback was a shift in sentiment.
As new policies emerged from Washington, focused on trade, tariffs, and government spending, investors, business leaders, and consumers began to show signs of caution. While these developments are still evolving, they’ve introduced a level of uncertainty that markets typically dislike.

Figure 2 tracks three key sentiment indicators that help us understand how people are feeling about the economy:
- Consumer Sentiment (top clip): This comes from the University of Michigan’s well-known survey. After recovering steadily from the lows of the pandemic, consumer confidence dipped again in early 2025. Higher prices, policy shifts, and election-year headlines have likely all contributed to renewed anxiety. Since consumer spending drives nearly 70% of the U.S. economy, a dip in confidence can have ripple effects.
- CEO Confidence (middle clip): Business leaders are also showing signs of concern. The Conference Board’s index fell to its lowest level since 2011. CEOs are facing tough decisions amid uncertainty over tariffs, global trade dynamics, and potential changes to labor and immigration policy. When CEOs feel cautious, they tend to delay hiring, investing, or expanding, which can slow broader economic growth.
- Market Volatility (bottom clip): Measured by the CBOE Volatility Index (VIX), market turbulence picked up noticeably after mid-February. Some volatility is a normal part of investing, but the recent spike reflects investors trying to price in an unclear policy outlook. Until there’s more clarity, we may continue to see wider swings in the market.
Sentiment doesn’t always match reality, but it can influence behavior. People might spend less, hire less, or invest less simply because they feel uncertain. That’s why we monitor these data points.
Ultimately, they can help us anticipate how market participants might behave in the months ahead. While sentiment has softened, the economic data has not yet caught up, suggesting a possible lag between perception and actual economic activity.
So then, what sentiment data are telling us now is that there’s a potential that negative sentiment could feed into a self-perpetuating cycle of slower economic growth, slower earnings growth which could lead to more market volatility in the weeks and months ahead.
An Update on the U.S. Economy
Now, it’s easy to assume that when markets fall, the economy must be weakening too, but that’s not always the case. The stock market can be considered a voting, or discounting machine. It’s a forward-looking mechanism that’s trying to price in expectations about the future into today’s market.
So then, prices tend to move up and down to expectations, not just present conditions. And while market sentiment shifted this quarter due to policy uncertainty, the latest economic data tells a more nuanced story.
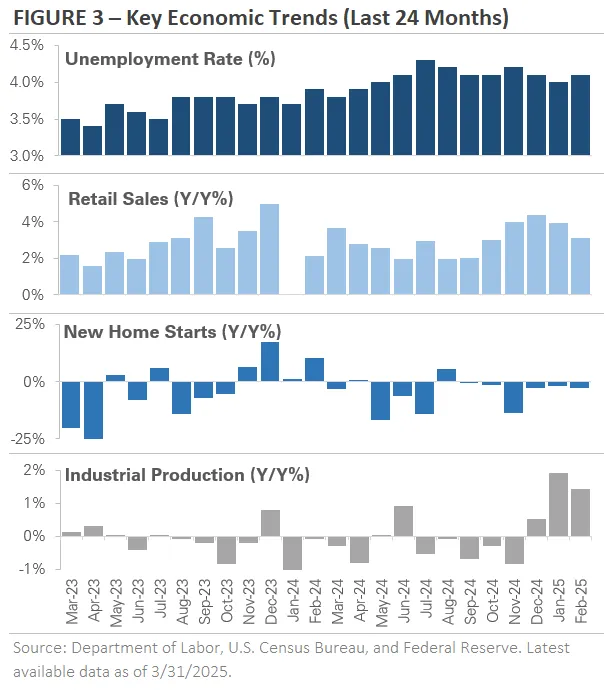
Figure 3 illustrates four key economic indicators that help us evaluate the health of the U.S. economy:
- Unemployment Rate (top clip): Despite headlines, the labor market remains solid. After ticking up in 2023 and early 2024, unemployment has moved lower in recent months as job growth has picked up. A strong job market means continued income for households and stable consumer spending which is the backbone of the economy.
- Retail Sales Growth (second clip): Consumer spending grew strongly in 2023, buoyed by higher wages and leftover savings from the pandemic. In 2024 and early 2025, growth has slowed, but not reversed. This signals that households are still spending, just more cautiously, which is a natural adjustment as interest rates remain elevated.
- Housing Starts (third clip): The housing sector has cooled in recent years due to high mortgage rates and affordability challenges. Builders are also facing added uncertainty as potential tariffs could increase material costs, and immigration policies may impact labor availability. Still, new home construction remains above pre-pandemic levels, a sign of resilience despite the headwinds.
- Industrial Production (fourth clip): This measure of economic output from factories, utilities, and mines declined through much of 2023 and 2024. Recently, however, it has begun to recover. Improved clarity on interest rate cuts and post-election policy direction ahead of tariff decisions could have contributed to renewed business investment.
The bottom line: So are we headed for an economic collapse? Well, it depends. Presently, the data suggests that the economy is still growing, but at a slower pace. The labor market is healthy, consumers are adjusting rather than retreating, and manufacturing is showing early signs of strength.
With that said, the effects of the Trade War are likely not yet fully reflected in the economic data. There’s a potential that, a policy misstep by the current administration could create conditions (weakening sentiment, lower spending and investment) that precipitate an economic slowdown.
That’s why these data points are worth monitoring closely. For now, we’ll continue to monitor the risks, particularly around policy impacts, as the overall data does not reflect that we’re currently in a recession.
Overall, it’s uncertain whether the short-term headlines will evolve into an economic decline. That’s why we believe it’s important to stay focused on long-term trends and avoid letting momentary shifts dictate your financial strategy.
Equity Market Recap: Looking Beyond the Index
So then, what does this valuation, sentiment and economic backdrop mean for stocks as we move through the second quarter?
Well, most of the stock market’s decline this quarter happened after the S&P 500 set a new all-time high on February 19th. And what’s crucial to understand is that this pullback wasn’t spread evenly across the market.
That’s because a handful of the largest, most recognizable companies bore the brunt of the losses, and as we pointed out earlier, their size meant they pulled the overall index down with them.
The “Growth” style of investing, which includes many of the big technology names that led in recent years, declined -10% in Q1. The Nasdaq 100, a tech-heavy index that includes the “Magnificent 7” fell -8%. But underneath the surface, the picture looked very different.
In fact, 9 of the 11 sectors in the S&P 500 outperformed the index. Seven of those sectors actually posted positive returns, while two were flat. Only two sectors, Technology and Consumer Discretionary, saw notable losses, and both are heavily influenced by the Magnificent 7 through the end of March.
In other words, there wasn’t a broad-based selloff per se in the first quarter. Rather, it was a concentrated recalibration of the companies that led the market higher in 2023 and 2024. Indeed, many of last year’s lagging sectors are this year’s leaders, showing how market leadership can rotate quickly.
International stocks also stood out in Q1. For example, the MSCI EAFE Index, which tracks developed markets outside the U.S., gained +8%, and posted one of its strongest quarters of outperformance since 2000.
Europe, in particular, saw strength as governments unveiled new spending initiatives. And the MSCI Emerging Markets Index also gained +4.5%, outpacing the S&P 500 by nearly +9%.
Market headlines often focus on the S&P 500, but that’s just one slice of a broader, globally diversified portfolio. Last quarter’s performance reminds us why we diversify: when one area struggles, others may thrive. That balance helps smooth returns and reduce risk over time.
Credit Market Recap: Bonds Trade Higher in Q1
While stocks declined in the first quarter, the bond market offered a measure of stability. In fact, bonds did what they’re often designed to do: provide diversification and help cushion portfolios during periods of market stress.
There were two main themes in the bond market this quarter: a drop in U.S. Treasury yields and a widening in credit spreads.
First, let’s talk about yields. The 10-year Treasury yield fell from around 4.80% in mid-January to 4.15% by early March. This decline reflected a shift in investor behavior as concerns over policy uncertainty, potential tariffs, and a slowing economy pushed investors to seek safety in longer-term government bonds.
When demand for these bonds rises, their prices go up and their yields fall.
As bond prices rose, investors benefited, especially those with Treasury exposure. This helped offset some of the losses from the stock market and reinforced the value of owning high-quality bonds as part of a diversified strategy.
As we enter the second quarter, this theme is being challenged as some large investors question holding Treasuries. However, it’s crucial to note that the Treasury market still remains the largest and most liquid bond market globally, and is backed by the Federal Reserve.
With that said, the second major and notable bond market theme in the first quarter was credit spread expansion. Now, this theme is something to watch as it’s typically reflective of market or economic uncertainties.
That’s because credit spreads measure the extra yield investors demand to lend money to corporations, compared to lending to the U.S. government. Wider spreads mean investors are more cautious because they see greater risk in lending to companies, especially those firms with lower credit ratings.
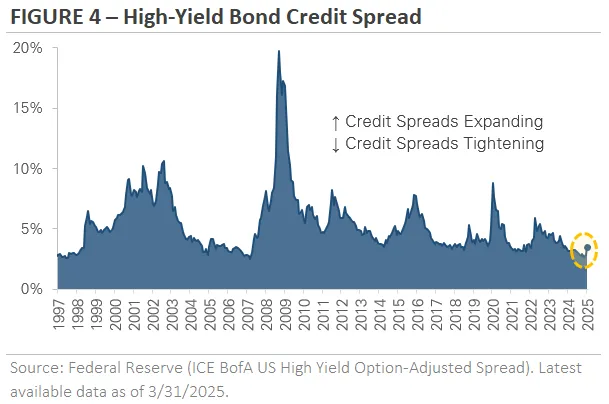
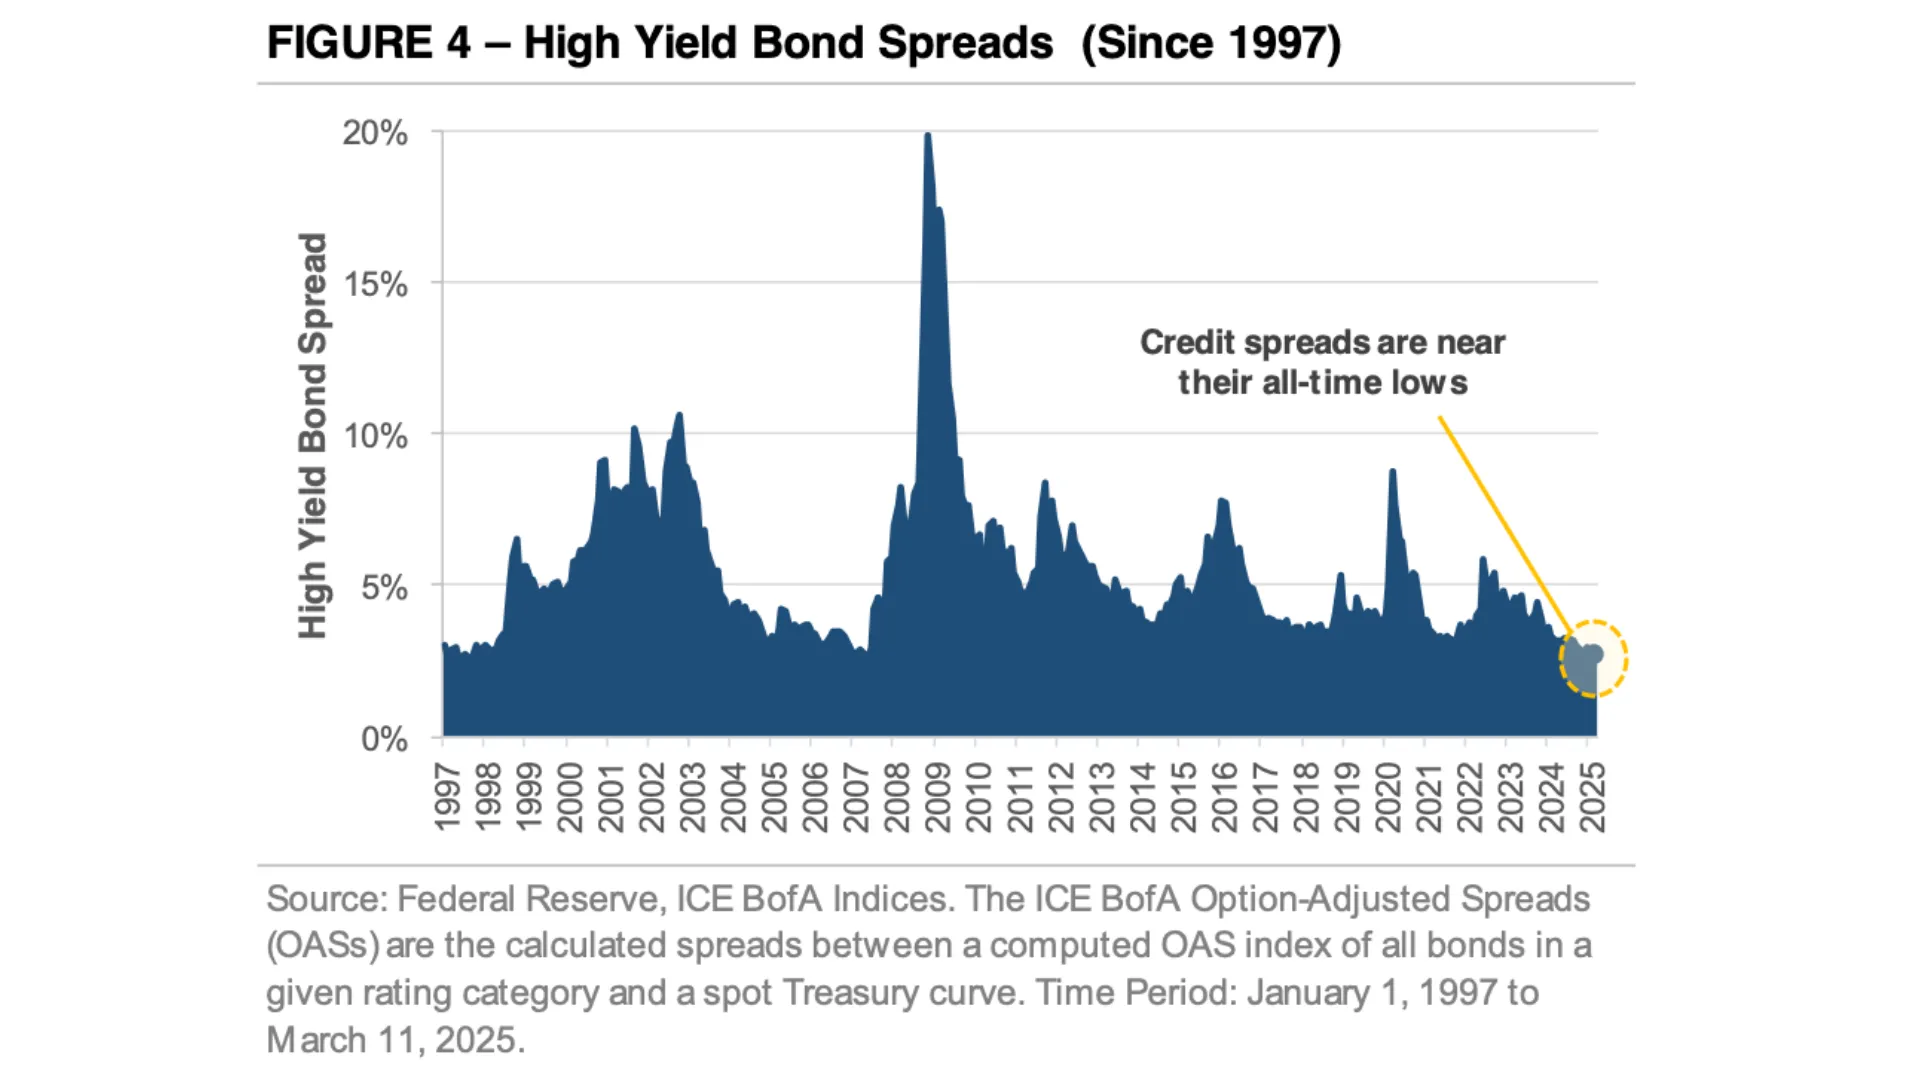
Figure 4 charts the high-yield credit spread going back to 1997. And after narrowing in late 2024, when the Federal Reserve began cutting rates, spreads began to widen again in Q1. The yellow circle highlights this recent shift. This suggests that investors are now more sensitive to risks around tariffs, slower growth, and policy change.
That said, spreads remain low by historical standards, which likely means that while caution has increased, the bond market isn’t flashing warning signs of financial stress. Indeed, by some measures, companies still have access to capital, and credit markets remain functional barring external shocks from further policy mis-steps.
Overall, bonds remain an important stabilizer in your portfolio regardless of what you’re reading in the headlines. Even as uncertainty rises, high-quality bonds continue to provide ballast during turbulent periods. And while credit spreads have widened slightly, the broader financial system remains sound for now, which is another reason to stay grounded and focused on your long-term plan.
2025 Outlook: Maintaining a Long-Term View
Periods of market volatility can feel unsettling, especially when headlines are filled with ambiguity. But these periods are not only normal, they’re expected as part of a typical economic and market cycle.
In fact, they’re part of what makes long-term investing work.
How so?
Well, pullbacks help reset expectations, cool overheated areas of the market, and set the stage for future gains.
Figure 5 puts this into perspective. It shows nearly a century of S&P 500 data and highlights a simple truth: market pullbacks happen almost every year. Since 1928, the index has experienced a decline of at least -5% in 91 out of 98 calendar years. The median intra-year drop is -13%. This year’s volatility isn’t unusual, it follows a well-established pattern.
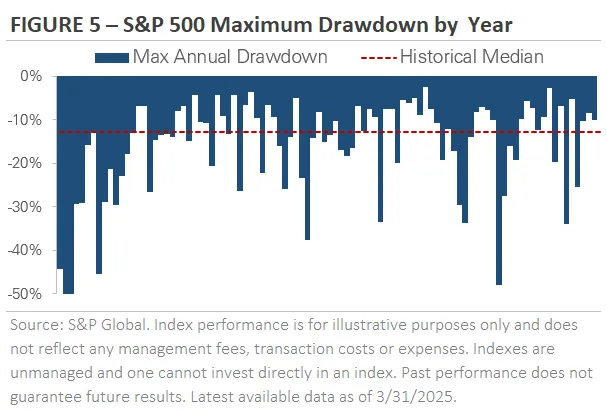
In fact, despite wars, recessions, inflation spikes, financial crises, and global pandemics, the market has consistently recovered and moved higher over time. That upward trajectory has been fueled by economic growth, innovation, and corporate profitability and not just investor optimism.
Here’s the key takeaway: volatility is the price of admission for long-term growth.
And trying to avoid short-term swings by timing your way into and out of the market often means missing the eventual rebound. So then, by staying fully invested, no matter what the market is doing, you give your portfolio the chance to participate in compounding returns over time.
Overall, my job is to help you stay focused on what you can control, including your goals, your risk tolerance, your long-term plan. When the headlines shift, your strategy doesn’t have to because we’ve built a plan designed to weather times like these, and we’re here to help you stick with it.
Whether markets are rising or falling, the most powerful tool we have is perspective. And right now, perspective reminds us that temporary setbacks are a normal part of progress, and that long-term success comes not from reacting to every twist and turn, but from remaining committed to a thoughtful plan.
Income Tax Valley: The Most Overlooked Years in Retirement Planning
One of the biggest and most preventable tax mistakes high-net-worth retirees make is waiting too long to address the growing tax liability in their pre-tax retirement accounts.
Sure, you may have done everything right, like saving diligently and building a sizable nest egg so you can enter retirement with confidence.
But now, your IRA or 401(k) sits like a tax time bomb, waiting to trigger Required Minimum Distributions (RMDs) and inflate your taxable income well into your 70s and beyond.
Indeed, what many investors don't realize is that the years between age 59½ and when you begin taking Social Security represent a golden opportunity to defuse that tax burden.
That's because, with no 10% early withdrawal penalty, reduced earned income, and RMDs still a few years away, you're in a low-tax window, but one that won't last for too long.
And that's where Roth conversions come in.
That's because converting your pre-tax account during this window gives you more control over how and when you pay your taxes.
In fact, it allows you to strategically move money from tax-deferred to tax-free accounts, locking in today's rates and reducing tomorrow's surprises.
With that said, the key here is recognizing that this isn't just a planning opportunity; it's a problem-solving moment. One that can dramatically improve your long-term tax picture if handled wisely.
Why Timing Matters
Now, if you've just retired, the years between when you stop working and begin claiming Social Security is strategic.
That's because, more often than not, your income is temporarily low.
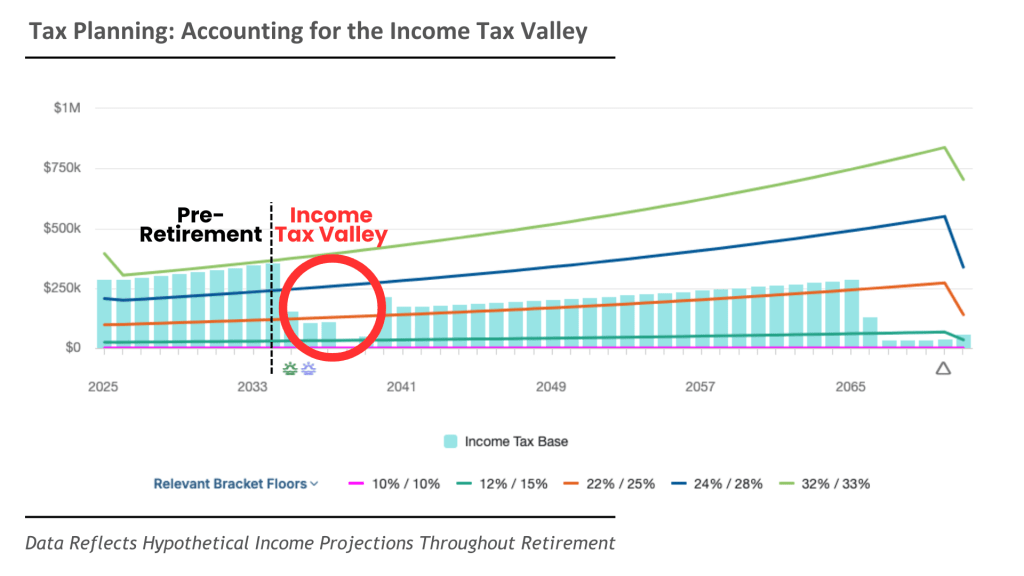
We call this the income tax valley.
You're no longer working, you haven't started taking Social Security, and Required Minimum Distributions haven't kicked in.
In fact, for many high-net-worth retirees, this is the lowest tax bracket they'll be in for the rest of their lives.
That's what makes Roth conversions so powerful in this window.
You can move money from tax-deferred accounts, like IRAs and 401(k)s, into a Roth IRA and pay taxes at a rate you choose, not one the IRS forces on you later.
What this means is that every dollar you convert now is one less dollar subject to RMDs down the road. That means lower future taxes, fewer Medicare surcharges, and more flexibility in how you take income later.
Ultimately, when it comes to tax planning in the income tax valley, you're either proactive now, or you'll be forced to be reactive later.
Even so, this is your chance to get ahead.
How This Works in Practice
So, what does this kind of planning look like in practice?
Well, let me tell you about my friend, Susan.
Susan is 62 years old, recently retired, and sitting on about $3.2 million in retirement savings, mostly in her traditional IRA and 401(k).
She's healthy and financially secure and plans to delay Social Security until age 70 to lock in the maximum benefit.
At first, Susan figured she didn't need to do much until her benefits started. But when she sat down with her advisor, she saw the bigger picture.
Her income during this income tax valley was low, around $50,000 a year, including capital gains distributions from a taxable account and some small dividends.
That gave her a unique opportunity to convert $100,000 a year from her IRA to a Roth and allowed her to stay within a lower tax bracket and avoid triggering higher Medicare premiums.
In fact, over the next eight years, Susan moved $800,000 into a Roth IRA.
More importantly, she paid the taxes on these conversions on her terms.
In fact, she reduced her future RMDs by nearly $30,000 a year. And in doing so, she built a tax-free pool of money for later retirement and legacy planning.
Same accounts. Same retirement. It's just a smarter sequence, with a major long-term impact.
Why Roth Conversions Before Social Security Can Be Advantageous
So then, when it comes down to it, the window between age 59½ and claiming Social Security isn't just a quiet phase of retirement, it's one of the most powerful tax planning opportunities you'll ever have.
That's because Roth conversions during this time can reduce future RMDs, minimize your lifetime tax liability, avoid Medicare premium surcharges, and give you more control over how your retirement income is taxed.
And for high-net-worth individuals like yourself, the cost of inaction isn't small; it means tax savings that are compounded over decades.
If you don't take action now, it can mean bigger RMDs, potentially putting you in higher tax brackets, offering less flexibility, and allowing more of your retirement savings to go to the IRS instead of your family.
With that said, with the right strategy, this window of opportunity, your income tax valley, becomes a moment of leverage. It becomes a chance to take control, preserve more wealth, and shape a smarter financial legacy on your own terms.
At the end of the day, tax planning isn't about reacting to the past; it's about anticipating and being proactive about the future. And the retirees who plan ahead are the ones who spend with confidence and leave more behind.
Liberation Day: What to Make of the Latest Tariff Announcement
This week, the U.S. government announced new tariffs starting with a 10% tax on all imported goods starting April 5.
Some countries, like China, will face even higher tariffs as part of a plan to push for fairer trade. These changes have caused markets to react quickly, with some stocks falling sharply and investors turning to safer options like bonds.
Now, it’s natural to have questions about what this means for the economy, your cost of living, and your investments.
That’s why in this update, I’ll walk you through what’s happening, why it matters, and how to think about your next steps.
What’s Happening and Why Now?
The Trump administration is rolling out a major shift in trade policy.
Beginning April 5, a 10% tax will apply to all goods imported into the U.S., with very few exceptions.
Then, on April 9, extra tariffs will be added for about 60 countries that are seen as having unfair trade practices.
For example, goods from China could face tariffs as high as 54%.
The goal?
Reduce the country’s $1.2 trillion trade deficit and bring manufacturing jobs back to the U.S.
This plan has been in the works since the last presidential campaign, and President Trump is calling the launch “Liberation Day,” hinting that these changes could be long-lasting.
Still, other countries may push back, and that could force future changes to the plan.
Are We Headed for a Trade War or Recession?
Right now, countries like China and those in the European Union are warning that they may fight back by placing their own tariffs on U.S. goods.
That raises fears of a trade war, which could slow the global economy. But so far, no official counterattacks have been made.
Economists say these tariffs could reduce U.S. economic growth and increase inflation, meaning prices might go up.
That doesn’t mean a recession is guaranteed, though.
The last time tariffs were raised back in 2018 growth slowed but stayed positive, thanks to strong consumer spending.
These new tariffs cover more goods, so the risks are higher, but the future is still uncertain.
How Are Markets Reacting?
Markets don’t like surprises, and this announcement was a big one.
Stocks dropped as news broke, especially for companies that rely on imports, like Apple, Ford, and Nike.
At the same time, bond prices went up as investors looked for safer places to put their money. Oil prices also fell due to concerns about slower economic growth.
While this reaction feels dramatic, it’s also common.
Markets often move quickly on news before all the details are known. That’s why we stay focused on long-term investing.
Your portfolio was built with days like this in mind, and it includes a mix of assets including U.S. and international stocks, bonds, and real estate that work together to manage risk.
Will This Raise My Everyday Costs?
Possibly, but not right away.
While tariffs begin in early April, it takes time for supply chains to adjust.
Some companies may raise prices, but others might absorb the extra costs at first.
If prices do go up, it could mean an extra $1,000 a year for the average household, with increases on things like phones, cars, and appliances.
Still, these are estimates, not guarantees.
We’ll be watching how companies respond and how prices shift over the next few months.
What Should I Do Right Now?
There’s no need to take action right away.
The effects of these tariffs will unfold over time. If you’ve been planning a big purchase. like a car, it might make sense to move sooner, just in case prices rise.
For everyday expenses, consider leaving a little extra room in your monthly budget.
As for your investments, patience is key.
We’ll keep a close eye on how things develop, and we’re here if you have questions.
Nevertheless, keep in mind that reacting too quickly to headlines can do more harm than good over the long-term.
Big Takeaway
Uncertainty is part of investing, and times like these are exactly why we’ve taken a diversified, long-term approach.
I’ll continue monitoring how these tariffs play out and keep you updated along the way.
If you’re feeling concerned or just want to talk things through, don’t hesitate to reach out, I’m always here to help.
Market Update: Is it a Correction or Something Bigger?
What do you do when the market takes a turn you didn’t expect? Do you panic? Do you make quick decisions? Or do you take a step back and look at the bigger picture?
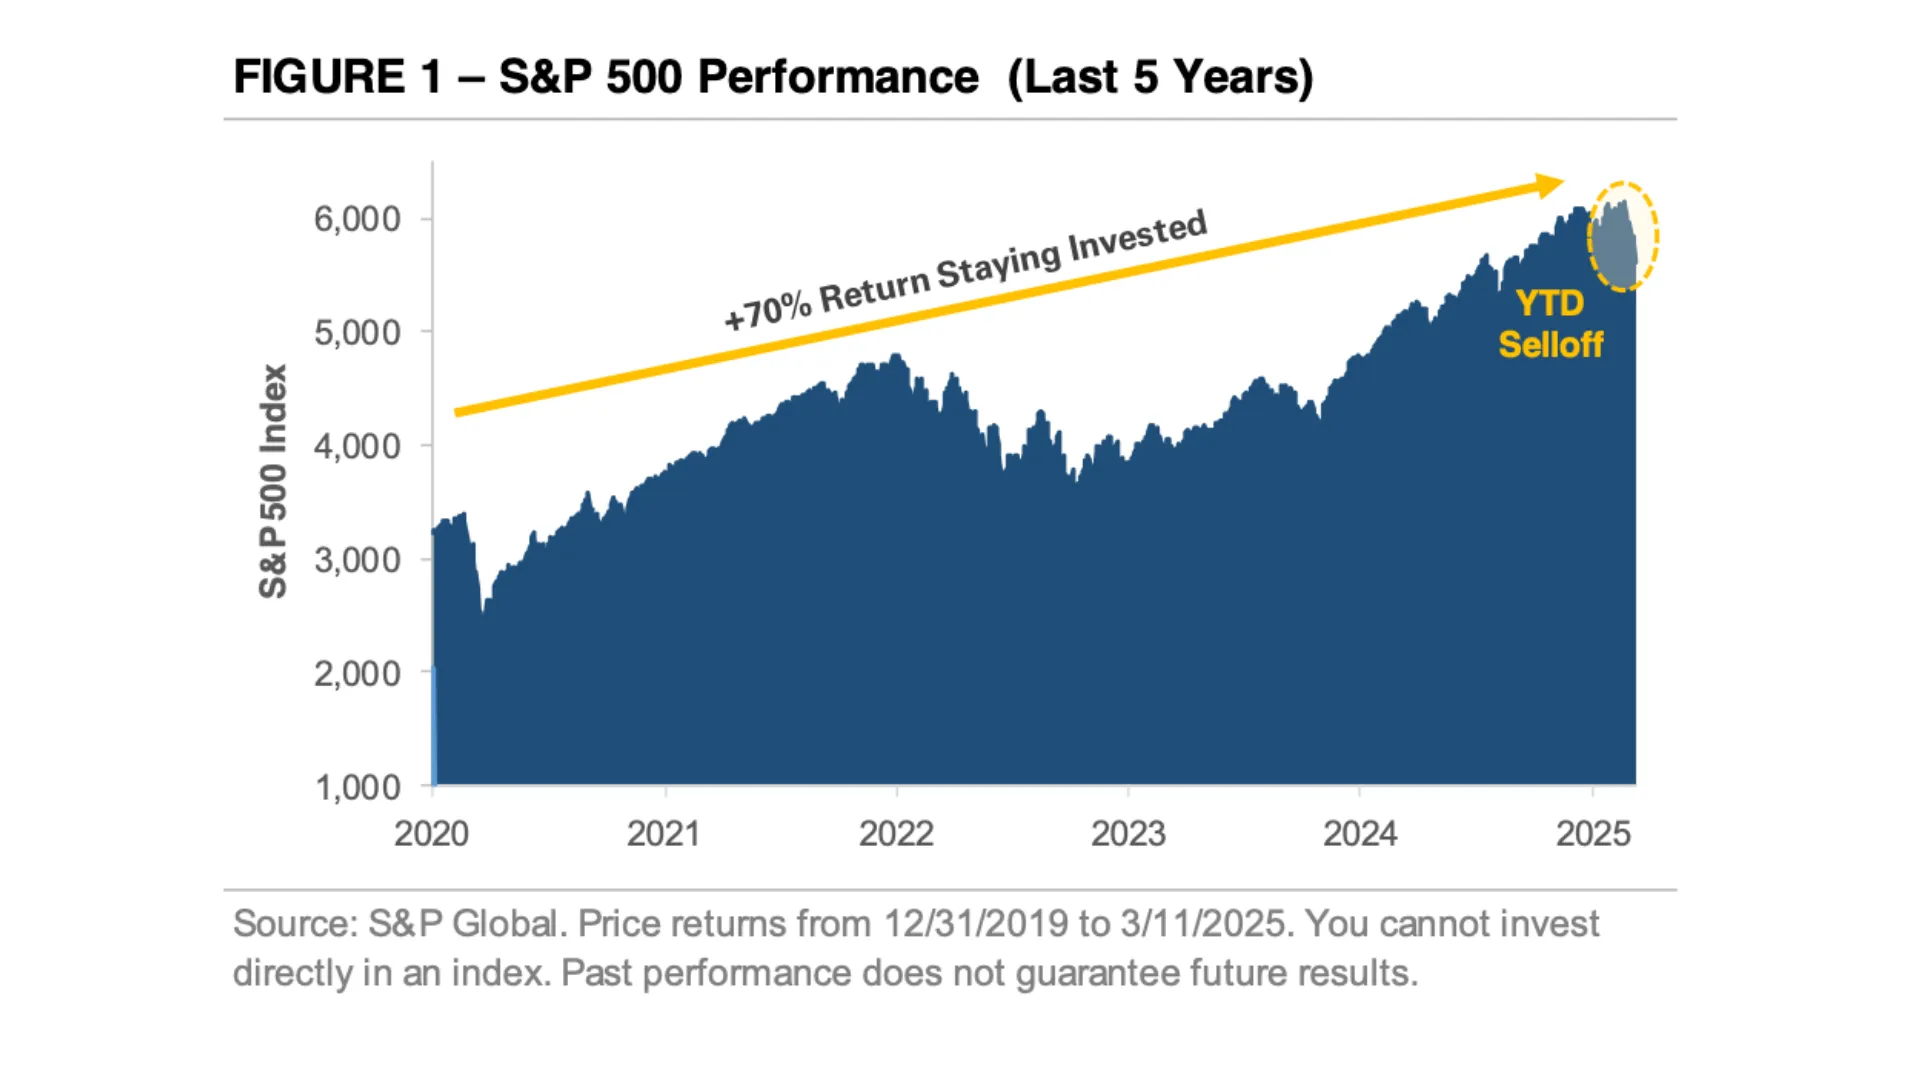
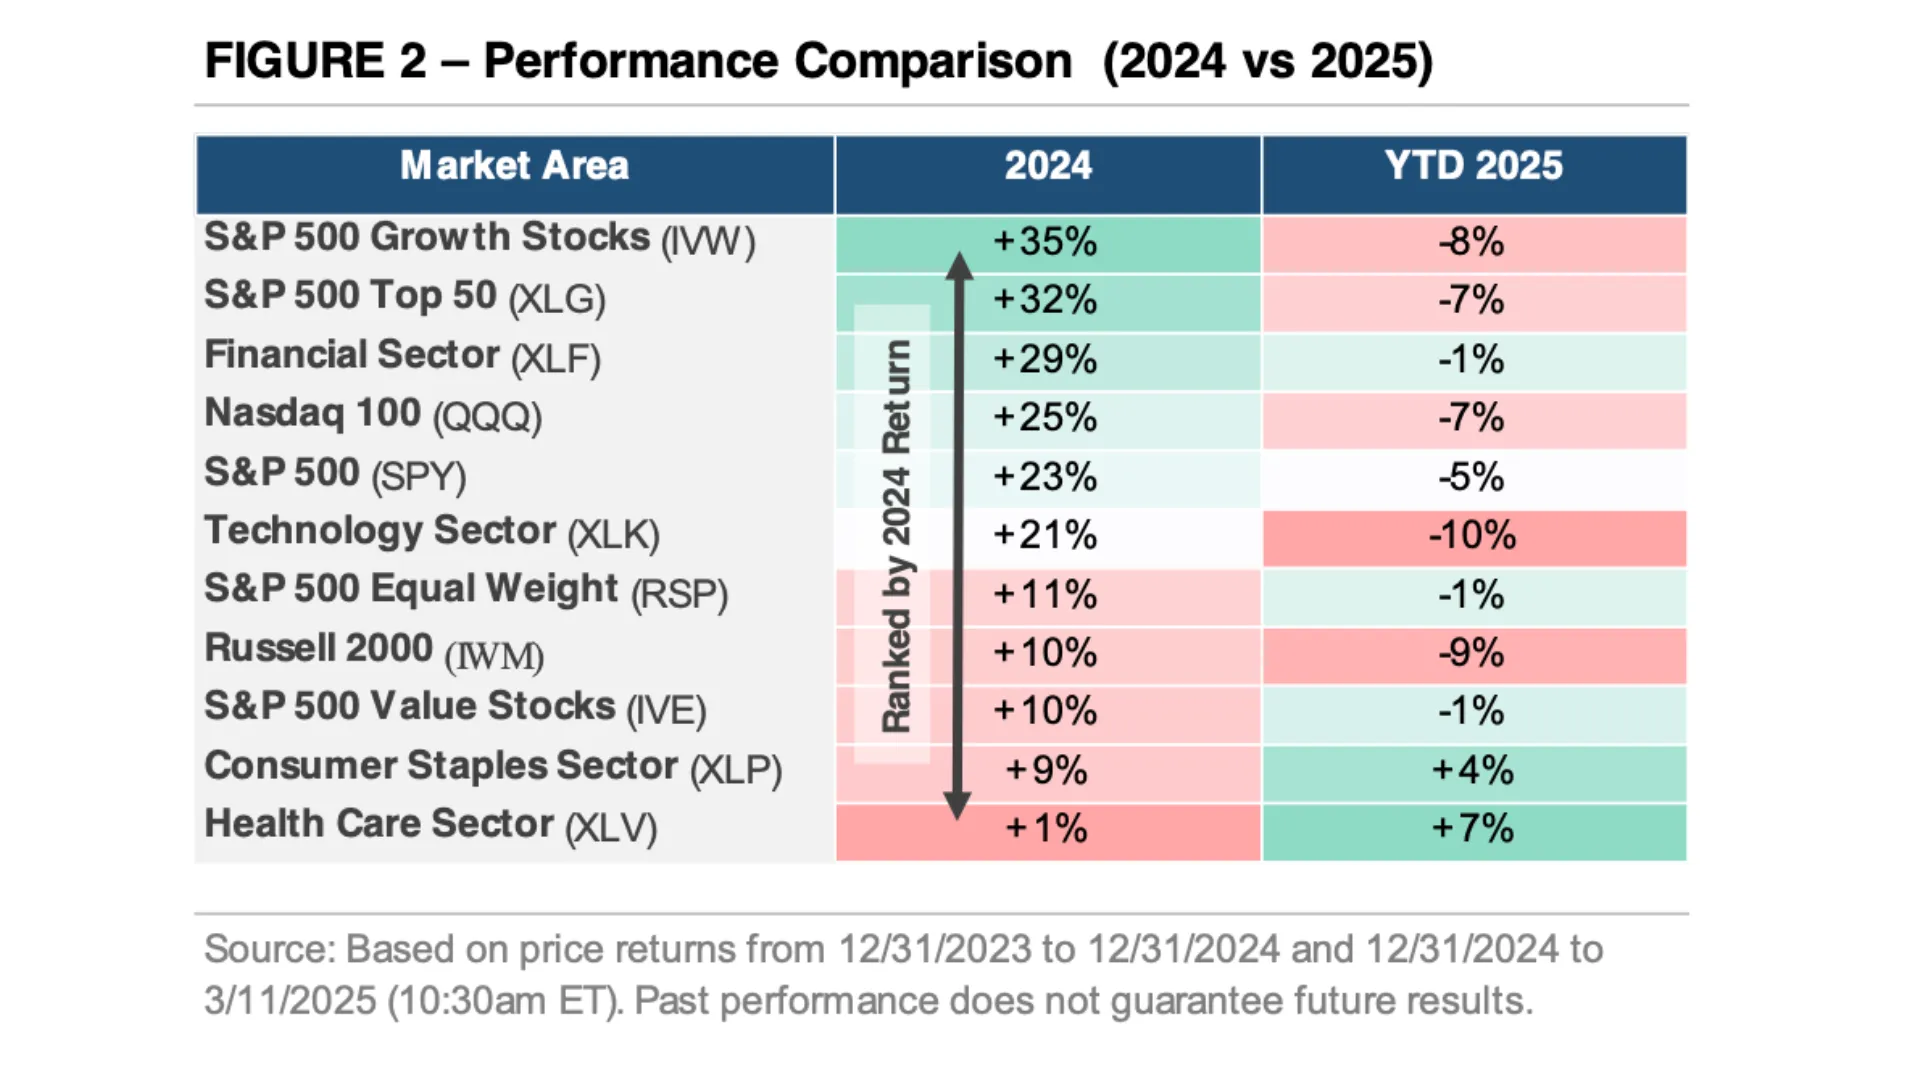
As we step into the first few months of 2025, the market has given investors plenty to think about. Stocks started the year on a strong note, but since then, we've seen a pullback. The S&P 500 briefly entered correction territory, bringing its year-to-date return down to -5%.
Similarly, the Nasdaq 100, home to some of the biggest names in tech, is down 7% this year, while the small-cap Russell 2000 has fallen 9%. And the what about the Magnificent 7 of Microsoft, Apple, Meta, Alphabet, Amazon, Nvidia, and Tesla? They’re down nearly 15%.
So what’s really going on? More importantly, what should you do about it?
What’s Behind the Market Selloff?
Well, it’s easy to blame market swings on one big event. But in reality, it’s rarely just one thing because there are likely a few reasons this year’s recent pullback.
First, the stocks that led the charge last year are the ones struggling the most today. And it’s not unusual to have yesterday’s winners become today’s laggards. Indeed, figure 2 shows us that the biggest winners of 2024, like tech stocks and the Magnificent 7, have become 2025’s underperformers.
Why?
Because last year’s rally was built on enthusiasm, especially around artificial intelligence. And when enthusiasm drives prices higher, valuations get stretched. Investors pile in, positioning gets crowded, and eventually, the weight of that momentum starts to break down.
That’s what’s happening now.
Second, investors, both individual and institutional, came into 2025 with a high level of exposure to stocks. In fact, some of the largest institutional investors like pension funds, endowments, and insurance companies held a record share of their wealth in equities.
And that strategy works well when markets are climbing, but when momentum reverses, institutional investors start deleveraging. And when they unwind positions quickly, it amplifies the selling pressure.
Finally, there’s the policy backdrop. What started as optimism around pro-growth policies under the Trump administration has shifted to uncertainty. As we’ve written about before, concerns about spending cuts and the impact of tariffs have raised questions about economic growth.
Because the fact of the matter is that investors don’t like uncertainty, and right now, they’re adjusting to a new, highly uncertain reality.
Market Volatility vs. Economic Reality
So, does all this mean the economy is struggling? That’s a great question. And here’s where we need to separate perception from reality.
The stock market reacts quickly to new information, but that doesn’t always mean the economy is following the same path. One way we can test that is by looking at real-time economic data.
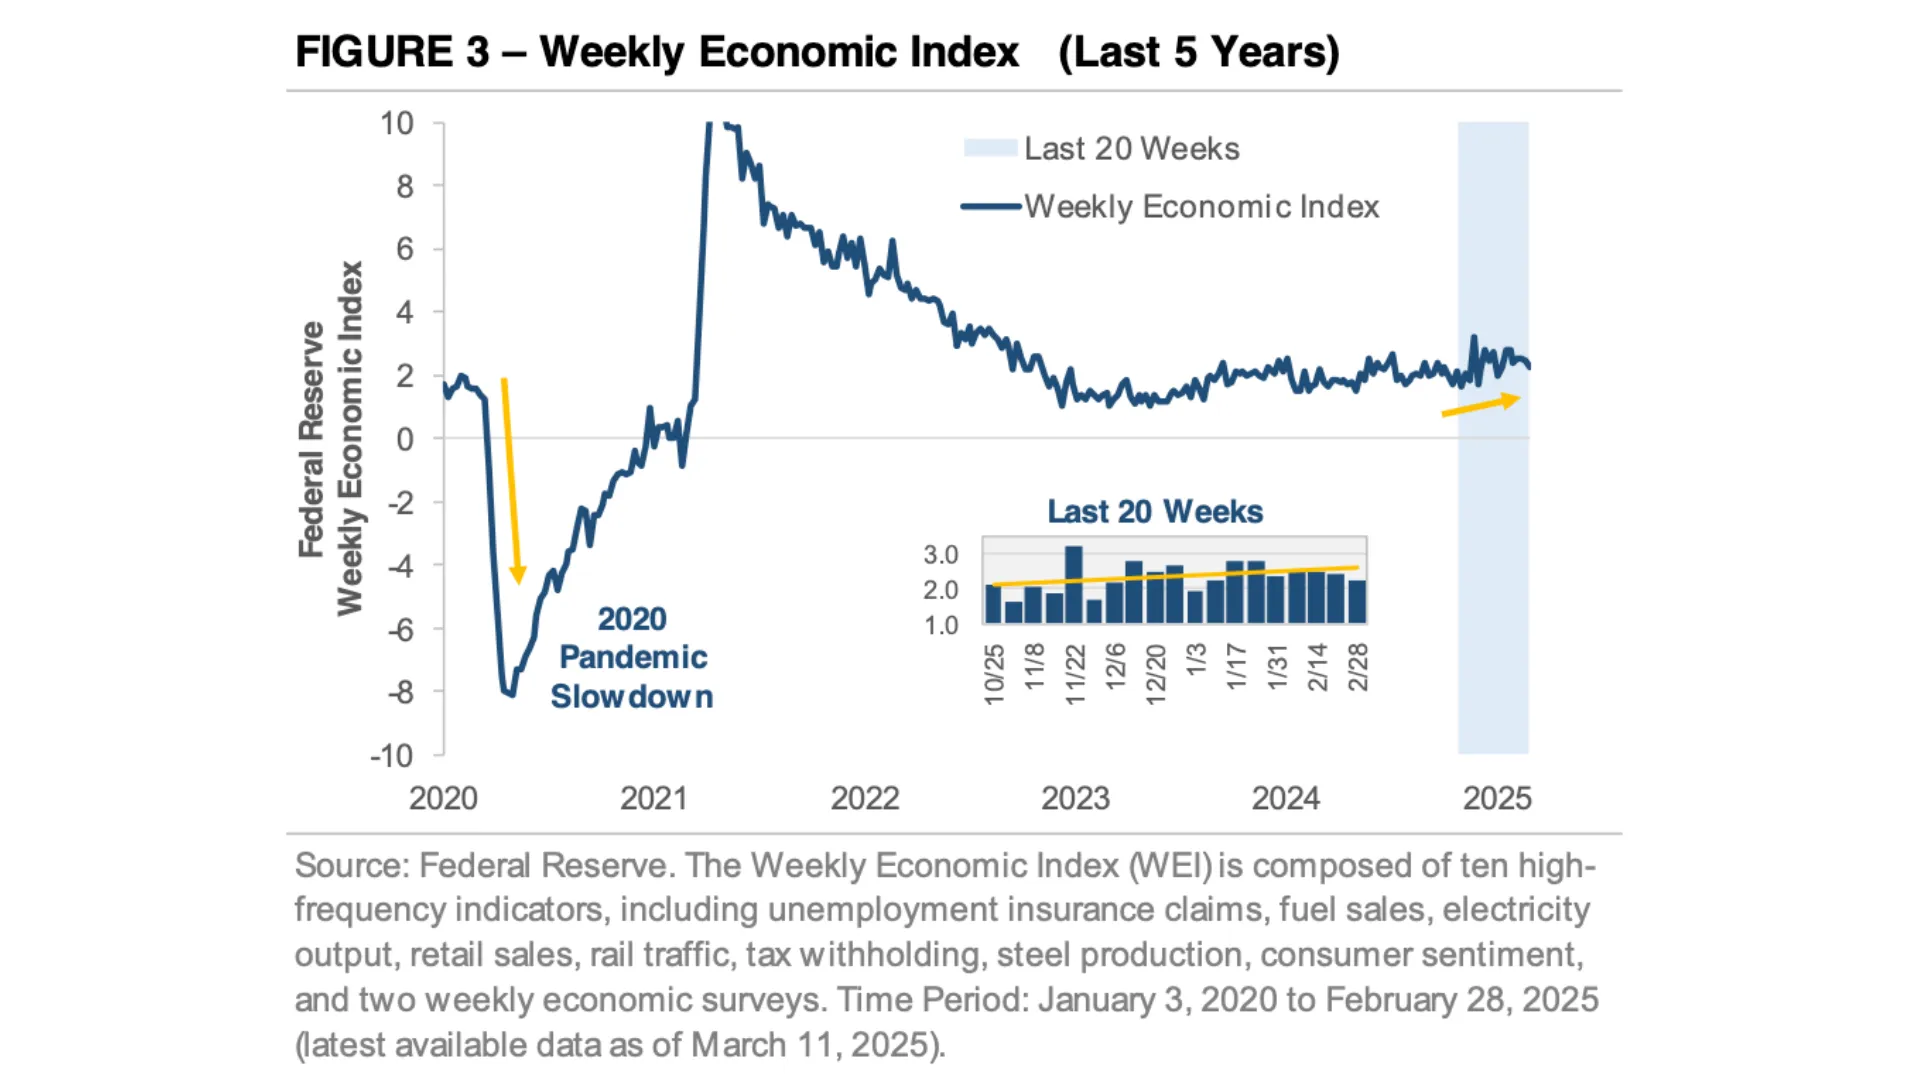
For example, the Federal Reserve’s Weekly Economic Index (WEI) tracks real-world activity using data points like unemployment claims, rail traffic, steel production, and tax withholdings.
And right now? It’s still positive (Figure 3).
Another piece of the puzzle is the bond market. High-yield credit spreads, which are essentially the difference in yield between risky corporate bonds and safer U.S. Treasuries, are a great way to measure financial stress.
And today, those spreads remain near all-time lows (Figure 4). Indeed, if we were facing a deeper economic problem, we’d expect to see those spreads widen. The fact that they haven’t tells us this market selloff could be more about repositioning than it is about a fundamental crisis.
With that said, no one rings a bell when we’ve entered a recession. And it’s very well possible that a policy error from the current administration could push the economy into a downturn. For now, however, the data continue to reflect modest economic growth.
Is This Normal and Can the Market Selloff Continue?
Now, if you’ve been investing for a while, you likely know that market volatility isn’t new. But let’s be honest, knowing that doesn’t make it feel any better when stocks drop, does it?
So what should you do?
Well, one of the best things we can do is put this moment in perspective. For example, since 1928, the S&P 500 has experienced a decline of 5% or more in 91 of the past 98 years.
Read that again.
In almost every year on record, we’ve seen the market pull back like this. And yet, time after time, markets have recovered. Investors who stay the course, who focus on the long-term, are the ones who have been rewarded.
So let me ask you: What’s your plan?
Because the difference between reacting and responding is having a plan. The key isn’t trying to predict every market move. It’s making sure you’re positioned to succeed no matter what happens next.
And that’s why sticking to a disciplined process and having a long-term perspective matter over the long-run.
The Bottom Line
Market volatility often feels personal. It’s your retirement savings on the line, isn’t it?
And so, when you see headlines about market swings, it’s easy to wonder, “Is this the beginning of something bigger? Am I missing something? Should I be doing something differently?”
So then, if that’s where your mind is right now, you’re not alone.
But more importantly, you’re not powerless. You don’t have to let fear dictate your financial future. You can make decisions based on a thoughtful strategy rather than short-term emotions.
Whether you’ve been working with our team for years or you’re just starting to explore your options, here’s what I want you to hear: clarity, confidence, and peace of mind don’t come from guessing the market’s next move. They come from knowing you have a plan that’s built for moments like this.
Because at the end of the day, the market will move up.
It will move down.
That’s a given.
But those who stay focused on the long term, those who stay diversified and patient, won’t just weather today’s volatility. They’ll be in the best position to thrive beyond it.
So, the real question isn’t what will the market do next? The real question is: Are you ready for whatever comes next?
The Market Feels Unstable — Here’s How to Stay on Track
There are times in market cycles when economic, geopolitical, and financial conditions converge in ways that create palpable uncertainty. In many ways, it can feel like standing on the precipice of an abyss.
Today, I would argue that we are in just one of those moments.
Often, it’s not just one event, but a cascade of interconnected developments that lead one to conclude that things are about to get bad.
History Often Rhymes
Early on in my career, it started with the failures of Bear Stearns and Lehman Brothers, the nationalization of Fannie Mae and Freddie Mac, and the bailouts of AIG and Citi, all of which signaled the fragility of the global financial system in 2008.
In 2020, early reports of health warnings, travel restrictions, and border closures eventually escalated into a near-total shutdown of the global economy, prompting widespread existential fear.
Now, in early 2025, we are experiencing heightened uncertainty as the resumption of trade wars with ambiguous objectives, shifting geopolitical alliances, and a retreat from post-war global institutions and a seeming move towards isolationism create a new political and economic reality. These shifts pose significant implications for the global economy and financial markets.
Needless to say, there is much to worry about in the current political, economic, and market environment. It’s enough to make any sane person want to bury their savings in their backyard.
How to Navigate the Uncertainty
That said, having been through multiple market cycles, being an avid student of history, and considering my background in macroeconomic strategy, I would like to share some thoughts on how to frame today’s environment and what you can do about it financially.
Firstly, I want to acknowledge that we are in the midst of an anxiety-provoking time in U.S. history. I am not going to discount the legitimate fear that many of us may be feeling right now amidst all the political tumult and economic uncertainties. This is a natural response.
With that said, when it comes to investing and the markets, it’s crucial to remember that we’ve been through similar challenges in the past. And with history as our guide, during times like these, it’s essential to remain committed to a long-term, disciplined investment strategy.
Make no mistake, what’s happening today will have significant implications for years to come.

Why It’s Essential to Stay Committed for the Long-term
However, history has shown that, from a capital markets perspective, risk assets tend to sell off during political and economic inflection points, before eventually recovering. These ebbs and flows are a natural part of the market process when key narratives change.
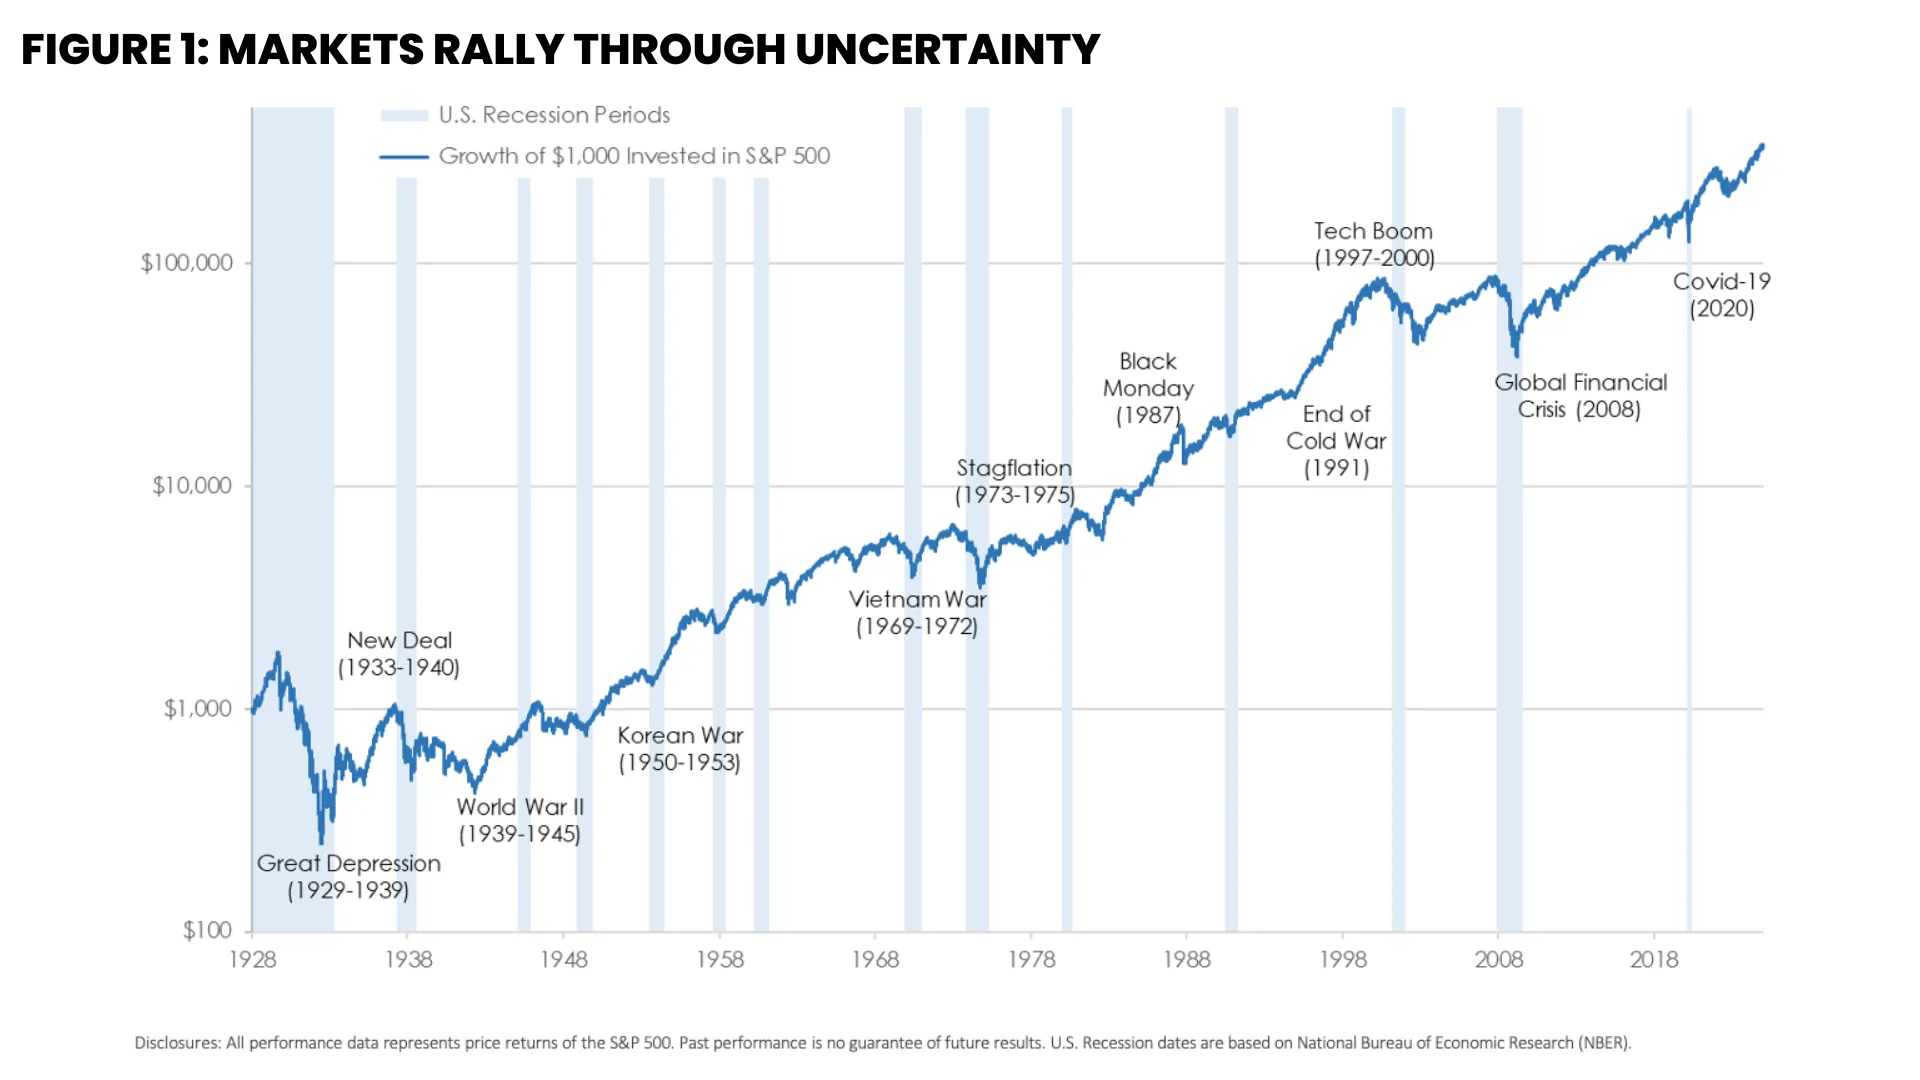
In fact, over the past 100 years, there have been many paradigm-shifting political and economic events, but stock prices continued to march higher thereafter. This point is evidenced in Figure 1.
To be sure, financial markets, after periods of uncertainty, do eventually recover as investors eventually adapt to new political or economic paradigms. Indeed, as figure 1 illustrates, risk asset prices are naturally biased to the upside because if they weren’t, then investing would not be much different from gambling, would it?
Nevertheless, you might say that now is not the right time to be in the markets and that you would prefer to get out. However, history has also shown us that exiting the markets at the wrong time could lead to major disappointment down the road.
For example, Figure 2 shows how missing even the best five days over the past 20 years could have led to significant missed opportunities in the markets. Indeed, back in 2008, it is arguable that peak market fear occurred at the end of the year, just a few months before the market bottomed out in March 2009.
Similarly, in 2020, peak fear occurred in late February before markets bottomed out in March and then took off again in April. Therefore, trying to time the markets or get out when it feels like things are starting to get bad might work against you over the near- and long-term.
Practical Steps to Take
So then, amidst all of this, what should you do about it all?
Well, in uncertain times, many investors often find themselves torn between taking action and standing still.
Here are six key strategies to consider regardless of where you stand today:
#1 Know Your “Sleep Well Number” (Cash Management)
When it comes to cash management, during times like these, it is crucial to know your “sleep-well” number. Depending on where you are in your retirement journey, having enough cash on hand to cover six to eighteen months of living expenses is something to consider now.
Having this number available will enable you to avoid making knee-jerk decisions with your portfolio, enable you to stay committed to your long-term strategy and avoid selling assets at an inopportune time.
#2 Rebalance Your Portfolio
Rebalancing your portfolio now allows you to take some risk off the table. Markets have rallied handsomely over the past eighteen months, which means that your current holdings are very likely out of alignment with your strategic asset allocation.
Rebalancing includes taking gains from positions that have done well in your portfolio and adding to positions that are underallocated in your portfolio relative to your strategic allocation. This approach ensures that you’re not taking any more risk than necessary with your investments.
#3 Stick to Your Long-term Plan
When in doubt, stick to your plan. Remembering your long-term plan is essential during market uncertainty. That’s because it is easy to become distracted and search for a salve to relieve the unease in the near term when things start going off the rails.
However, it’s crucial to remember that your financial plan was created to help you navigate not just the good times, but also uncertain times like the ones we’re experiencing today.
#4 Reconsider Big-Ticket Purchases
If you are contemplating purchasing a new home, car, or other big-ticket item, you may want to consider holding off on any moves for the next few months. This approach will allow you to preserve cash and ensure that you are not locking yourself into a decision at an inopportune time.
#5 Sharpen Your Pencil
At the same time, it is worth sharpening your pencil. Warren Buffett is known to have said, “Be fearful when others are greedy, and greedy when others are fearful.” Depending on your living situation and cash position, fear-driven market sell-offs often provide opportunities to purchase assets at a discount.
If you are in a solid cash position, keeping an eye out for favorable buying opportunities once we have more clarity on the political and economic environment could be worthwhile.
#6 Consider Tax Planning Opportunities
Finally, market sell-offs also present an opportune time for tax planning. And a key tax planning approach includes completing a Roth conversion. That’s because lower portfolio values often translate to lower taxable values. Remember, Roth conversions are not just a fourth-quarter tactic but a year-round opportunity.
Similarly, market downturns can present opportunities for tax-loss harvesting. This approach involves selling stocks at a loss and buying a similar but not identical asset. Even if you do not have gains to offset the losses, you can carry forward the losses as a tax asset to offset future capital gains.
The Big Takeaway
When it comes down to it, the big takeaway from an investment perspective is to stay invested for the long term even though the near term seems so uncertain. While we may be headed for a dark period in the months ahead, I am reminded of how essential it is to remain optimistic.
Viktor Frankl, a Holocaust survivor and author of the book, “Man’s Search for Meaning”, points out in his work that those who adapted and sought meaning in each moment, especially in trying times, had greater ability to endure trials and uncertainty than those who did not.
Make no mistake, we are likely headed for some very trying times in the weeks and months ahead. From a political and social perspective, we do not have a roadmap for navigating what lies ahead, which means we will have to take things one moment at a time. As difficult as that may be, however, finding purpose and direction in uncertain times has always been a defining trait of those who successfully emerge from such events.
What’s more, from a financial perspective, history has repeatedly shown that uncertain times like these often create opportunities for those who stay the course. That’s why having a solid financial plan and a disciplined investment strategy is essential now more than ever. While the near-term outlook may be uncertain, remaining objective and committed to a well-thought-out financial plan continues to be the best way forward.
Fed Policy: Are Rates Poised to Head Higher or Lower in 2025?
Are interest rates headed higher or lower in 2025? Well, it likely depends on the incoming data.
Indeed, not long ago, the Federal Reserve launched one of the fastest rate-hiking cycles in history as it was determined to bring inflation down from a multi-decade high. After keeping rates elevated for more than a year, the Fed shifted course in late 2024, cutting rates by a full percentage point between September and December.
Today, however, policymakers appear to be taking a "wait-and-see" approach as incoming data present conflicting stories.
The Fed's Balancing Act: Inflation vs. Employment
Now, to understand where things stand, it helps to remember that the Fed has two main responsibilities.
First, it aims for price stability, which means keeping inflation low and predictable. Second, its job is to seek out full employment, ensuring conditions that encourage job growth while keeping unemployment in check. The challenge today is that these two goals don't always align perfectly. And right now, the balance between them is changing.
How so?
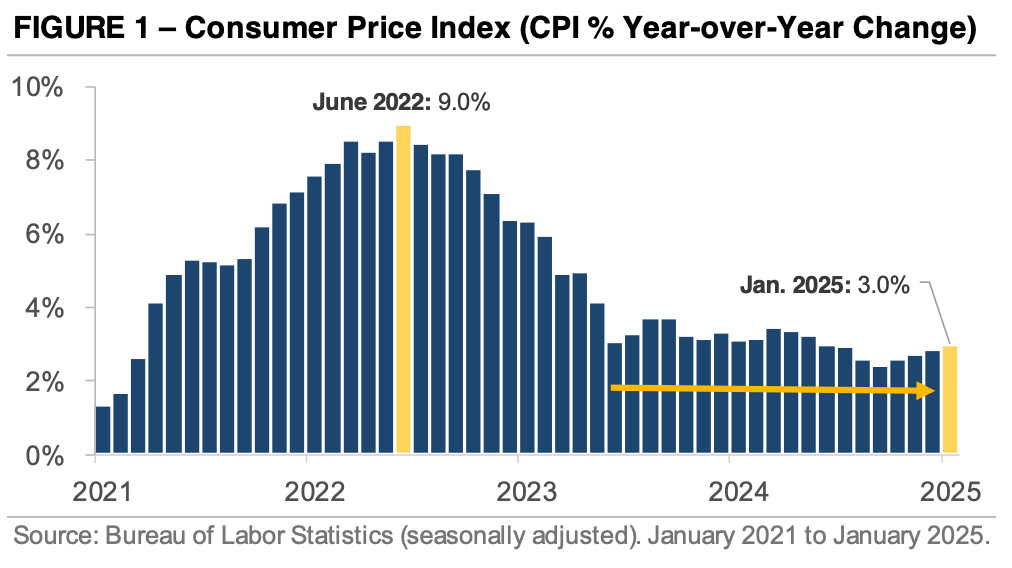
Well, consider inflation. The chart in Figure 1 tracks the year-over-year change in the Consumer Price Index (CPI), which measures how the prices of everyday goods and services fluctuate. Throughout most of 2024, inflation had been steadily declining.
However, in January 2025, inflation picked up again. CPI rose 0.5% from the previous month, marking the largest increase since August 2023. As a result, the annual inflation rate inched up to 3.0%, slightly above December's 2.9%.
And while inflation has come down significantly from its peak of nearly 9% in mid-2022, progress has stalled in recent months. Indeed, since late 2023, CPI has hovered around 3%, raising concerns that inflation could remain above the Fed's 2% target for an extended period.
Conflicting Jobs Data
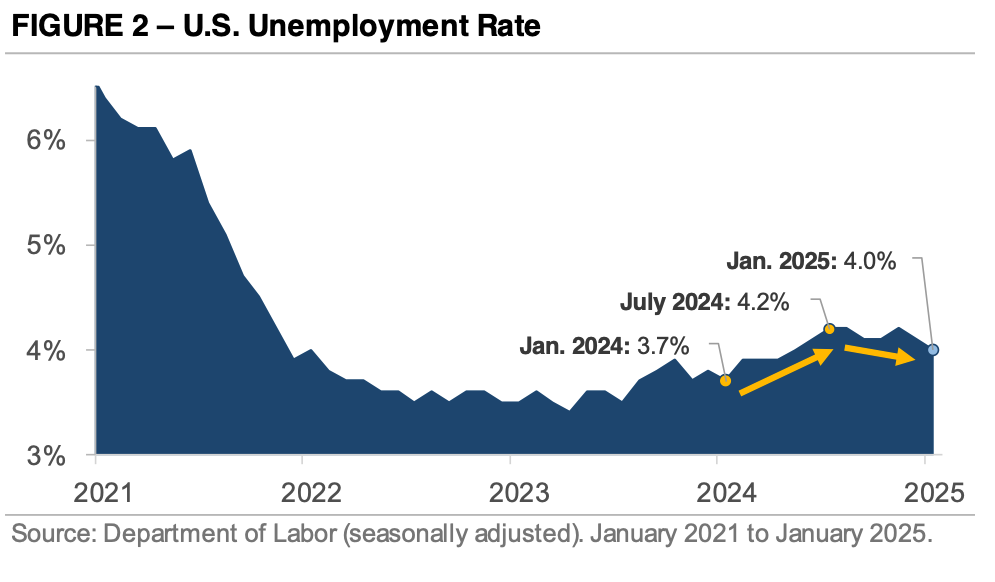
At the same time, the labor market continues to show resilience. Figure 2 highlights the U.S. unemployment rate, which remains strong by historical standards.
In fact, in January, unemployment edged lower to 4.0% which is the lowest its been since May 2024. To be sure, while employers added 143,000 jobs that month, which was a slower pace compared to the post-pandemic hiring boom, it was nevertheless a sign of steady demand for workers.
At the same time, job numbers from November and December were revised higher, revealing that the economy created 100,000 more jobs than initially reported.
And this has been problematic for the Fed given that just a few months ago, policymakers pointed to rising unemployment as a reason to begin cutting rates. However, recent data suggests that the labor market is not weakening as quickly as many had expected.
What Does this Mean for Interest Rates?
So, what does this mean for interest rates?
Well, in 2024, the Fed started cutting rates to shift its focus from controlling inflation to supporting job growth. However, now that inflation progress has stalled and the labor market remains stable, many believe the Fed will pause further rate cuts until it has more clarity.
In fact, at its January 2025 meeting, the central bank chose to keep interest rates steady after three consecutive cuts. At the same time, Fed Chair Jerome Powell reinforced this cautious stance, explaining that there is no immediate need to rush into further adjustments.
What Should You Do About It?
Looking ahead, there are signs that market expectations have shifted.
To be sure, instead of anticipating another rate cut in the early months of the year, many now expect the next adjustment to come in June 2025. However, the real question remains: Will inflation continue to cool, or will the Fed need to rethink its strategy once again?
With the political climate shifting, budget cuts looming, and both households and businesses feeling more cautious, the Fed's decision to pause may not be a sign of confidence but rather a reflection of uncertainty.
Could inflation take another leg down if demand slows further? That remains to be seen. But more importantly, what does all of this mean for your investments?
Right now, it's very well likely that we're in a period of transition. The economy is adjusting, and markets are searching for direction. But if history has taught us anything, it's that trying to predict where markets will go in the next 12 months, or even the next 12 weeks, is rarely a winning strategy.
Indeed, over the past five years, market behavior has looked very different from the decade before.
The Big Takeaway
So, what should you focus on instead?
Well, one thing that hasn't changed is the value of a well-diversified portfolio. While markets shift and economic conditions evolve, diversification remains one of the best ways to manage risk. This approach ensures that no single event, no single policy decision, and no single downturn can completely derail your long-term progress.
Either way, here's the big takeaway: There is still plenty of uncertainty surrounding inflation, interest rates, and the economy. While some indicators point to slower growth ahead, the wisest approach isn't to react to every twist and turn.
Instead, it's to stay disciplined, stay focused, and stay committed to your long-term plan. Now more than ever, doing so will keep you from being caught off guard no matter which way the markets move next.
Five Reasons Why a Roth Conversion Might be Right for You
You've done everything right: you've worked hard, built a successful career, and saved for the future. But there's one piece of the puzzle that could quietly erode your wealth if you don't plan for it: taxes.
Retirement isn't just about how much you've saved, it's about how much you get to keep. And if most of your retirement savings are in tax-deferred accounts like a 401(k) or traditional IRA, the IRS has plans for that money. That’s why tax planning is crucial now more than ever.
In fact, when it comes to IRAs, those withdrawals you take in retirement will be taxed as ordinary income, and when you turn 75, Required Minimum Distributions (RMDs) will force you to take money out, even if you don't need it.
But here's the thing: what if you could pay taxes on your own terms?
What if you could lock in today's lower tax rates, reduce your future tax burden, and create a more flexible income strategy for retirement?
That's where a Roth conversion comes in.
In fact, by converting a portion of your tax-deferred retirement savings into a Roth IRA, you pay taxes on that money now and at a rate you can control.
In return, your Roth IRA grows tax-free, and when you need to withdraw in retirement, there are no additional taxes owed.
What's more, there are no RMDs, no surprise tax bills, and a better plan for passing wealth to your heirs when it comes to your Roth IRA.
But the big question here is is it the right move for you?
Well, the answer depends on several factors, including your current and future tax rates, your retirement timeline, and how you want to structure your income.
So then, let's break down five key reasons why a Roth conversion could be one of the smartest financial decisions you make in 2025.
#1 Would You Rather Pay Taxes at Today's Rates or Risk Higher Rates in the Future?
First things first, would You Rather Pay Taxes at Today's Rates or Risk Higher Rates in the Future? Think about it: do you believe taxes will be lower in the future? Or do you think they'll go up?
If you're like most people, you're betting on higher taxes. And that's not just a guess. The tax cuts currently in place are set to expire after 2025, which means tax rates for high earners could rise significantly. If nothing changes, the top tax bracket will jump from 37% back up to 39.6%.
And even if the Tax Cuts and Jobs Act is extended, there's no guarantee that tax rates won't go higher in the future given our country's massive debt burden.
Indeed, with rising government debt and shifting tax policies, higher taxes could become the norm. So then, if you wait to withdraw from your tax-deferred accounts in retirement, you could find yourself paying much more in taxes than if you had acted earlier.
That's where a Roth conversion lets you take control. Because instead of waiting to see what happens, you can lock in today's lower rates and create tax-free income for the future.
How so? Well, let's say you convert $500,000 from a traditional IRA to a Roth IRA today while you're in the 24% tax bracket. In this case, you'll likely owe $120,000 (24% of $500,000) in taxes today.
Now, let's assume you wait 10 years, but by then, higher tax rates push you into the 35% bracket. With that same amount, assuming no growth of your savings, you'd likely owe $175,000 (35% of $500,000).
That's a $55,000 difference, just for waiting.
And here's where it really adds up: if that $55,000 in tax savings were invested instead at an average 7% annual return, it could grow to over $400,000 in 30 years, all because you converted when rates were lower.
So then, by making a move today, you're not just reducing taxes, you're potentially adding hundreds of thousands of dollars to your retirement savings all by paying some tax today, to save a lot more in the future.
#2 Do You Want to Avoid Required Minimum Distributions (RMDs) That Could Inflate Your Tax Bill?
The next thing to consider when it comes to determining whether a Roth Conversion is right for you is whether you're comfortable paying your anticipated RMDs.
Now, you may not need the money, but the IRS does.
That's because by the time you're age 75, you'll be required to start withdrawing money from your traditional IRA or 401(k), whether you want to or not. And these Required Minimum Distributions (RMDs) aren't just forced withdrawals, they're taxable income.
Now, depending on how large your retirement accounts are, RMDs can push you into a higher tax bracket, trigger higher Medicare premiums, and cause more of your Social Security benefits to be taxed.
That's where a Roth conversion can help you get ahead of this problem. Because Roth IRAs aren't subject to RMDs, converting today means you keep more control over your income in retirement, instead of letting the government decide for you.
So then, how does this work? Well, let's say you're 65 years old with a $2 million traditional IRA, and it grows at 6% per year. Here's what happens if you don't convert any of it to a Roth.
By age 75, your RMD starts at $87,591 per year. But each year, Uncle Sam forces you to take out more and more money from your IRA each year. So then, by age 90, your RMD balloons to $258,741 per year.
That means you'll be withdrawing more and paying more in taxes, whether you need the money or not.
However, if you convert a portion of your IRA to a Roth before RMDs kick in, you might be able to reduce your future tax burden and avoid being forced into withdrawals you don't want to take.
Put a different way, this isn't just about tax savings, it's about having more flexibility in how you use your money in retirement. So then, wouldn't you rather make that decision yourself or have Uncle Sam force you to take money out of your savings? That’s where prudent tax planning comes into play.
#3 Do You Want to Leave More to Your Heirs Without a Tax Burden?
You've spent a lifetime building wealth, and now you're preparing to pass it on. But do you really want the IRS to take a big chunk of what you leave behind to your children?
Because here's the thing: if your heirs inherit a traditional IRA, they'll be forced to withdraw the full balance within 10 years, and every dollar they take out is taxed as ordinary income.
So then, if they're in their peak earning years, those withdrawals could push them into a much higher tax bracket, costing them hundreds of thousands in unnecessary taxes.
A Roth IRA, on the other hand, passes on tax-free savings to your heirs, and no forced distributions for a spouse. In other words, no income taxes for your kids and no surprises when they inherit your wealth.
How does this work? Well, let's compare a $1 million traditional IRA and a $1 million Roth IRA passed down to your children.
If the money stays invested for 30 years at 7% annual growth, here's what happens. With a traditional IRA, your heirs must withdraw all funds within 10 years, and assuming they invest it, after taxes, it grows to $5.8 million.
However, if you left behind the same $1 million in a Roth IRA, it's possible that the portfolio would grow tax-free to $7.6 million and be available for tax-free withdrawals. That's a $1.8 million difference, all because of taxes.
Even if your heirs don't need the money right away, a Roth IRA lets them delay withdrawals until it makes sense for them, avoiding tax spikes and keeping more of your legacy intact.
So then, if you're planning to pass on wealth, the question is simple: Do you want your money to go to your family, or to the IRS?
#4 Could a Roth Conversion Help You Save on Medicare and Social Security Taxes?
Most people don't realize that their Medicare premiums and Social Security benefits are tied to their taxable income. In fact, the more income you report in retirement, the more you could pay for healthcare and the less of your Social Security you'll actually get to keep.
How does this happen? Well, it happens because withdrawals from a traditional IRA count as taxable income. So then, even if you don't need the money, those withdrawals could push you above key income thresholds, and trigger higher Medicare premiums which could make up to 85% of your Social Security benefits taxable.
A Roth IRA on the other hand avoids this issue because withdrawals don't count as taxable income. That means you can take money out as needed without pushing yourself into a higher tax bracket or triggering unexpected penalties.
How so? Well, let's take a couple who are 67 years old and are planning to retire soon. They have $1.5 million in a traditional IRA and $60,000 in combined Social Security benefits per year.
Now, if they start taking $80,000 per year from their IRA, they're likely to face a few complications. First, their Medicare premiums likely will increase due to IRMAA (Income-Related Monthly Adjustment Amounts). Next, they could find that up to 85% of their Social Security benefits become taxable and so, their total tax bill and healthcare costs jump by over $112,000 over their retirement.
Now, let's say this same couple converts $300,000 over three years into a Roth IRA before claiming Social Security and Medicare. In this case, their taxable income stays below Medicare surcharge limits, their Social Security remains largely untaxed and they save over $112,000 in combined healthcare and tax costs.
So then, this isn't about avoiding taxes, it's about planning ahead, especially when it comes to balancing retirement income with goverment benefits. From this perspective, why give more to the IRS when you can keep more for yourself through prudent tax planning?
#5 Are You Planning a Move to a Lower-Tax State?
Finally, where you live in retirement matters a lot, especially if you're considering a Roth conversion.
In fact, if you're planning to move from a high-tax state like California or New York to a no-income-tax state like Florida, Texas, or Nevada, the timing of your Roth conversion could save you tens, if not hundreds of thousands of dollars in state taxes.
That's because when you complete a Roth conversion, you'll also end up paying state taxes in the year you convert. So then, if you do a Roth conversion while living in a high-tax state, you could owe state income tax on that conversion. But if you wait until after you move, you could pay zero state tax on the conversion.
How does this work? Well, let's say you have a $1.5 million traditional IRA and are moving from California to Florida. You decide to convert the full amount before moving and California state tax (13.3%) on $1.5M conversion leads to $199,500 owed in taxes.
Now, let's say you wait until after you move to Florida where you pay no income tax. Here, you could effectively save $199,500 in taxes just by planning your move before coverting.
But what if you plan to stay in a high-tax state? A Roth conversion might still be a smart move, especially if state tax rates are expected to rise. In other words, locking in today's rates could still be a win.
Regardless, if you're thinking about moving, or even if you aren't, state taxes should be part of your Roth conversion decision. Because when it comes to taxes, timing is everything.
So, What's Your Next Move?
Let's be honest. Nobody enjoys thinking about taxes. However, whether you think about them or not, you will pay them on way or another. So then, the real question is not if you will pay taxes, but when and how much.
Right now, you have an opportunity to do some prudent tax planning. Tax rates are at historic lows, and you still have time to plan. Most importantly, you have the ability to decide what happens next, which might not always be the case.
So what's your plan?
Are you going to wait and hope the tax code works in your favor? Are you going to let the IRS determine how much of your wealth stays with you and how much goes to them? Or are you going to take control of your financial future while you still can?
Here is what we know. Tax rates are expected to rise in the coming years. Required Minimum Distributions could force you to withdraw more than you need, potentially pushing you into a higher tax bracket. If you plan to pass on wealth, your heirs could face a significant tax burden unless you make a plan.
Medicare premiums and Social Security taxes can increase unexpectedly, but with the right strategy, you can avoid these unnecessary costs. And if you are planning to move to a state with lower or no income tax, the timing of your Roth conversion could save you thousands of dollars.
That sounds like a lot. But here's the good news.
You do not have to figure this out on your own. You have time to plan. You have the ability to make smart decisions today that will give you more financial freedom in the future. Most importantly, you have options.
That is why I am here. Let's run the numbers, talk through your options, and build a strategy that works for you. The best time to plan for your future is today.
If you are ready to take the next step, schedule a call and let's get started.
Market Update: A Look Back at April's Market Drama
Have you ever noticed how quickly fear can spread in the financial markets? Or how a headline can send shockwaves through risk assets in a matter of hours?
That's exactly what happened in early April.
And it happened because the White House announced sweeping tariffs, escalating the Trade Wars and just like that, the S&P 500 dropped more than 10% in a single week.
Of course, investors panicked, and uncertainty took center stage.
But then, just as quickly as the fear appeared, it seemingly faded. The administration paused those tariffs, cooler heads began to prevail and by the end of the month, the market had clawed its way back, finishing April with a loss of less than one percent.
The bond market was a completely different story. That's because interest rates didn't know which way to go.
Indeed, they bounced around all month long, responding to every new headline and every ounce of economic doubt. But despite all the noise, they ended up right where they started, flat for the month.
Why Is Policy Driving the Markets?
Now, if you've been wondering what's really moving the markets this year, it all boils down to policy uncertainty.
The truth is that the rules of the game are changing as the direction out of Washington is shifting.
And when the future feels uncertain, people pause, businesses wait and consumers tend to hold back.
At the same time, market participants begin to take notice and start asking, "Is this the start of something bigger?"
Certainly, we've already seen the impact in some corners of the economy. Some consumer demand was pulled forward earlier in the year due to tariff concerns.
But now, there's a hesitation as surveys show that businesses and households are beginning to delay big spending and investment decisions because no one wants to make a move when the rules of the game might change tomorrow.
What's Going On with Stocks?
So then, what has this meant for stocks? Well, the fact of the matter is that what we're seeing in the markets today is when yesterday's winners stop winning. Indeed, the mega-cap Magnificent 7 tech stocks that dominated last year are down more than 15% in 2025 after soaring over 60% in 2024.
Even so, that doesn't mean all stocks are struggling because many investors have already begun shifting their focus to defensive sectors like Utilities, Consumer Staples, Health Care, and Real Estate.
And even though the S&P 500 is down more than five percent, these sectors are showing strength because, in uncertain times, people look for stability.
What's even more striking here is that for the first time since 2023, international stocks are leading the way. In fact, the first quarter was one of their best showings in over two decades.
So then, if you've been ignoring markets outside the U.S., now might be a good time to pay attention.
What About Bonds and the Fed?
And how have bonds done this year? Well, these markets have not been immune from the heightened level of volatility.
Indeed, Treasury yields have been jumping in response to, tariffs, debt concerns, inflation risks, and that ever-present cloud of uncertainty.
At the same time, corporate credit spreads, or the premium that investors demand above holding "safe" investments, have started to widen again.
That's making riskier high-yield bonds less attractive because investors are pricing in the unknown as they're preparing for a wide range of outcomes, and that's exactly what causes volatility.
Now, in the midst of all this volatility, the Fed is waiting patiently on hold. Rate cuts haven't started yet, but the market is betting that the first one will come in June. And not just one, but multiple cuts are now expected by the end of the year.
But that, of course, depends on how the economy holds up and how inflation behaves in the months ahead.
So What Does This Mean for You?
So, what should we make of all of these developments?
Well, the bottom line here is that markets threw a tantrum in April as policy uncertainty stirred the pot.
And for a moment, it felt like everything was up in the air.
But the fact of the matter is that this is what markets do when the path ahead feels unclear.
They test convictions, they expose cracks and they remind investors that uncertainty is the cost of admission for long-term growth.
Nevertheless, uncertainty doesn't have to equal instability.
Because if you have a clear purpose, a thoughtful plan, and a disciplined process for staying on track, then these moments become less about reacting and more about reaffirming what you already know to be true.
That's why now may not be the time to chase returns or make sweeping changes to your investment portfolio.
Even so, it may be the perfect time to revisit your strategy, reassess your positioning, and evaluate whether your plan is built for this kind of environment.
If you're not sure, let's have that conversation.
Because you don't have to predict the future to prepare for it, you just need to know what you own, why you own it, and what to do next.
That's what we help our clients do every day.