The Election Changed Washington. It Didn't Change Your Plan.
Maybe you stayed up Tuesday night refreshing the results. Maybe you woke up Wednesday morning relieved. Or maybe you woke up worried about what the next two years will bring.
Either way, if you're an investor, there's a good chance another question followed close behind:
Should I be doing something with my money?
Will the results lead to higher stock prices? Could a shift in congressional control change the direction of tax policy, government spending, or economic growth? And should your investments look different now that the votes have been counted?
These are fair questions.
After all, elections have consequences. The people we send to Washington make decisions that influence the economy, businesses, and ultimately the financial well-being of American households.
But here's what tends to get lost in the post-election noise:
The political landscape changed this week. Your financial plan didn't, at least not yet.
And understanding the difference could save you from making an expensive mistake.
Elections Matter. Just Not the Way Most Investors Think.
Now, to be clear, I'm not suggesting that elections don't matter to financial markets.
Quite the opposite.
During my years developing macroeconomic research and investment strategy at Wells Fargo Investment Institute, evaluating government policy and geopolitical developments was an important part of understanding the economic outlook.
That's because decisions made in Washington can have real consequences for corporate earnings, inflation, interest rates, and ultimately asset prices.
Consider fiscal policy, for example.
Changes to government spending and taxation can influence consumer demand and business investment. Tax reductions may encourage additional spending and investment, but depending on how they're financed, they can also contribute to larger federal deficits.
And those deficits matter because increased government borrowing can influence Treasury yields, which in turn affect mortgage rates, corporate borrowing costs, and the valuation of financial assets.
Trade policy is another example.
Tariffs might provide an advantage to certain domestic producers, but they can also raise input costs for companies relying on imported goods. Depending on how businesses respond, those higher costs can squeeze profits or contribute to higher consumer prices.
So, from this perspective, the composition of Congress matters because it can influence which policies advance, which face resistance, and which remain unresolved.
But here's where things get interesting.
The economic consequences of political decisions aren't always the same as their intended outcomes.
A policy designed to stimulate growth could contribute to inflation. A policy intended to protect domestic industries could create new costs elsewhere in the economy.
And even when investors correctly anticipate a policy change, financial markets may have already reflected those expectations in asset prices.
That's why understanding the election results is only the beginning of the investment analysis.
The more important question is how actual changes in policy interact with the economic environment that already exists.
Midterm Years Look Weak for Stocks. The Elections Weren't the Reason.
Now, if we turn to history, there's good reason to be cautious about drawing investment conclusions from election outcomes alone.
According to research from J.P. Morgan Asset Management, the S&P 500 has generated an average annual total return of 9.2% during midterm election years since 1937, compared with 13.3% during non-midterm years.
At first glance, that might suggest that midterm elections are bad for stocks.
But the numbers don't tell the whole story.
Consider 2018 and 2022.
Both were midterm election years, and both experienced significant stock market declines.
But the primary pressures on markets weren't the elections themselves.
In 2018, investors were dealing with tighter monetary policy, rising interest rates, and concerns about slowing global growth.
In 2022, inflation was running at its highest levels in decades, and the Federal Reserve was aggressively raising interest rates to contain it.
The elections happened against those economic backdrops. They weren't necessarily the reason markets struggled.
And that's an important distinction because correlation doesn't establish causation.
Indeed, research from J.P. Morgan also shows that the S&P 500 has historically generated positive returns in the twelve months following every midterm election since 1950, with an average gain of approximately 15%.
That's an interesting observation, but it isn't a forecast for the coming year.
Those historical returns occurred under very different economic conditions, interest-rate environments, and market valuations.
The takeaway isn't that stocks are destined to rally after an election.
It's that trying to use election outcomes alone to predict future market performance is a much less reliable exercise than many investors might believe.
The Bigger Risk Isn't Washington. It's How We React to It.
There's another factor that makes investing around elections particularly challenging.
And it has less to do with Washington than with how we process political information.
You see, whether we realize it or not, our political beliefs can influence our expectations about the economy.
When the political party we support wins, we might become more optimistic about the future.
When the other party wins, we might become more pessimistic.
But that change in sentiment doesn't necessarily reflect a change in the underlying economy.
Consider research published in The Journal of Finance examining how millions of American households adjusted their investments around the 2016 presidential election.
The researchers found that investors identified as likely Republicans increased their stock exposure following Donald Trump's victory, while investors identified as likely Democrats shifted toward safer assets.
Importantly, these changes were largely driven by a relatively small group of investors making substantial portfolio adjustments.
Think about that for a moment.
Two investors could look at the same election result, face the same economic conditions, and make completely different investment decisions simply because of how they interpret the political news.
Yet neither investor's retirement spending needs, long-term goals, or financial obligations necessarily changed overnight.
That's why I've long maintained that political opinions and investment decisions should be kept separate.
It's certainly reasonable to have concerns about government spending, deficits, taxes, or the direction of economic policy.
And it's equally reasonable to feel optimistic about policies that you believe could support economic growth.
But neither optimism nor pessimism is a substitute for evaluating corporate profits, interest rates, valuations, and the risks embedded in your investment portfolio.
Being right about an election doesn't automatically mean you'll be right about the stock market.
We Plan Around Policy Changes, Not Election Results
So, what does all of this mean for someone preparing for retirement or already living off their investments?
Well, this is where the distinction between monitoring economic developments and reacting to political headlines becomes particularly important.
At Franklin Madison Private Wealth, we approach economic and political uncertainty within the context of each client's broader financial plan.
And that means looking beyond what might happen in Washington to understand how different economic outcomes could affect a client's ability to meet their financial obligations.
Consider a couple approaching retirement that we recently worked with.
One of the central questions in their planning process was how to transition from earning a paycheck to generating income from their investments.
To answer that question, we first examined their actual household spending, separating recurring expenses from discretionary purchases and larger one-time financial commitments.
We then evaluated how their financial situation would change as employment income ended, healthcare costs shifted, and Social Security benefits eventually began.
An important part of that process involved modeling a multiyear Roth conversion strategy to evaluate whether paying taxes on retirement savings earlier could reduce their overall tax burden later in life.
Now, consider how this year's election fits into that picture.
Congressional decisions could eventually affect income tax provisions, healthcare policy, or other factors incorporated into their retirement projections.
But we wouldn't automatically change the couple's investment portfolio based solely on a change in congressional control.
Instead, we'd want to understand whether an actual policy change materially alters the assumptions supporting their plan.
For example, if tax legislation changes the economics of their Roth conversion strategy, we can revisit the timing and amount of future conversions.
If changes to healthcare policy affect their anticipated insurance costs, we can incorporate those costs into their retirement cash-flow projections.
And if changing economic conditions lead to higher inflation or weaker investment returns, we can evaluate how those developments affect the sustainability of their withdrawal strategy.
The key is that we're responding to changes in the client's financial circumstances and planning assumptions, not simply to changes in the political landscape.
You Don't Have to Predict the Next Crisis to Be Ready for It
The same approach applies to how we manage investment risk.
In another retirement planning engagement, our focus was on helping a client establish a more disciplined system for funding ongoing living expenses.
A key consideration was ensuring that the client had an appropriate amount of cash available to meet near-term spending needs without becoming overly dependent on selling investments at unfavorable times.
To accomplish this, we established a cash management framework that coordinated required minimum distributions, portfolio income, and planned withdrawals.
We also developed guidelines for maintaining and replenishing cash reserves, including circumstances in which it might be appropriate to delay selling equities during periods of significant market volatility.
Why does that matter?
Because for a retiree drawing income from a portfolio, the timing of investment losses can have lasting consequences.
A prolonged market decline combined with ongoing withdrawals can reduce the amount of capital available to participate in a subsequent recovery.
This is commonly referred to as sequence-of-returns risk.
Now, having cash available doesn't eliminate investment risk, and there's a cost associated with holding assets that may earn less than stocks over time.
But appropriately sized reserves can provide flexibility in meeting spending needs during market downturns.
And that flexibility is useful whether the next period of volatility comes from political uncertainty, inflation, a recession, or an unexpected geopolitical event.
In other words, we don't need to know which event will cause the next market decline to prepare for the possibility that one will occur.
That's the difference between trying to predict uncertainty and building a financial plan designed to accommodate it.
Ask What Changed for You, Not What Changed in Washington
Now that the election is behind us, the financial news cycle will inevitably shift toward what the new congressional landscape could mean for economic policy.
And there will be no shortage of opinions about which industries might benefit, whether inflation will move higher or lower, and what all of this could mean for stock prices.
Some of those arguments may prove correct.
But before making changes to your investments, I'd encourage you to ask yourself a more practical question:
What has actually changed about my financial situation that warrants a change in my investment strategy?
For instance, has your ability to withstand a market decline changed? Have your cash-flow needs increased? Are you approaching retirement with a portfolio that's more concentrated or aggressive than you originally intended?
And what about your tax situation?
If you're approaching retirement with substantial savings in a traditional IRA or 401(k), have you considered how future required minimum distributions, Social Security benefits, and potentially higher tax rates could affect your retirement income?
These are the types of decisions worth revisiting regularly.
Not because one political party won or lost an election, but because the economic assumptions underlying your financial plan can change over time.
And sometimes, an adjustment will be warranted.
That could mean rebalancing a portfolio that has drifted away from its intended allocation, reevaluating the amount of cash you hold, or updating a multiyear tax strategy following a meaningful change in tax law.
Other times, after reviewing the available information, the appropriate course of action might be to make no changes at all.
That's not ignoring uncertainty. It's managing it deliberately.
The Election Is Over. Your Financial Plan Still Has Work to Do.
As we move beyond the 2026 midterms, there's little doubt that Washington will remain an important source of economic headlines.
Questions surrounding fiscal policy, government debt, taxation, and regulation aren't going away simply because the election has concluded.
And as new policies are debated and implemented, we'll continue evaluating their potential consequences for financial markets and the economy.
But for individual investors, the bigger takeaway is that your investment strategy shouldn't depend on getting the political forecast right.
It should depend on having a clear understanding of what you're trying to accomplish, the risks you're willing and able to take, and the financial resources you'll need along the way.
After all, the next congressional election is only two years away.
Your retirement could last another twenty or thirty.
That's a much longer time horizon, and it's the one your financial plan needs to be built around.
At Franklin Madison Private Wealth, we help individuals and families coordinate their investment, tax, and retirement income strategies so that financial decisions remain grounded in long-term priorities rather than short-term uncertainty.
If you're concerned about how changing economic conditions could affect your retirement, we invite you to schedule a conversation to explore how your financial plan is positioned for the years ahead.
https://franklinmadisonadvisors.com/schedule-now/
Related Reading
Elections: Why You Shouldn't Mix Politics and Your Portfolio
Here's the Cost of Moving to the Sidelines
What Benjamin Graham Can Teach Us About Investing When the World Is Falling Apart
Keep Calm and Trust Your Investment Plan
July Market Update: A Loud Month, a Quiet Market
Research and Supporting Sources
J.P. Morgan Asset Management, "2026 Midterm Election Hub."
https://am.jpmorgan.com/us/en/asset-management/adv/insights/market-themes/us-elections/
J.P. Morgan Asset Management, "How Do Markets Perform Post-Midterms?"
https://am.jpmorgan.com/us/en/asset-management/institutional/insights/market-insights/market-updates/on-the-minds-of-investors/how-do-markets-perform-post-midterms/
Meeuwis, Parker, Schoar, and Simester (2022), "Belief Disagreement and Portfolio Choice," The Journal of Finance.
https://doi.org/10.1111/jofi.13179


Weekly Market Update: The Fed Holds as Growth Runs Hot
Stocks were mixed as investors weighed a Fed decision, strong economic data, and earnings from the largest tech companies.
The S&P 500 drifted higher and the Nasdaq gained nearly 1.5%, while the Dow fell about -1%. Small caps outperformed, with the Russell 2000 rising nearly 2.5%.
Nine of 11 sectors finished higher. Tech led with a 3.1% gain, while Communication Services fell more than -5% after Alphabet's earnings disappointed. High Beta and Momentum stocks outperformed Low Volatility, reversing part of last week's shift toward defensive stocks.
Treasury yields edged higher, and the 10-year yield stayed near 5%. The U.S. dollar firmed. Oil swung after attacks on Saudi energy facilities and ended the week nearly 3% higher. The VIX, a measure of expected volatility, fell back below 20.
Key Takeaways
Economy Grows Faster Than Expected
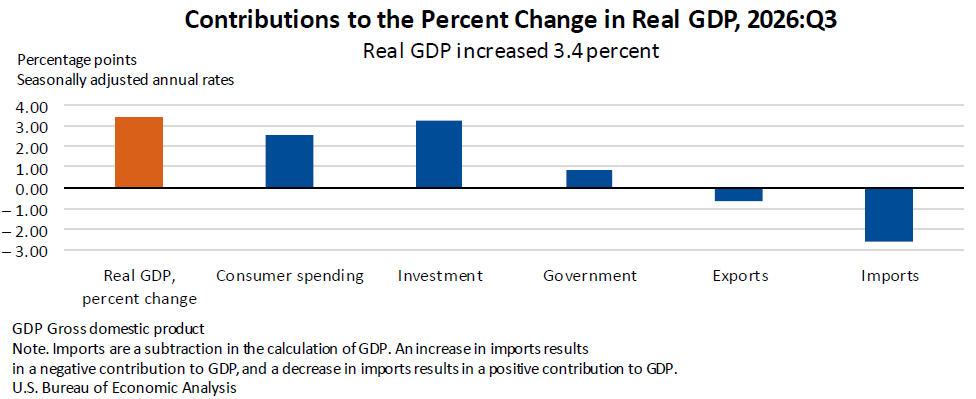
Real GDP grew at a 3.4% annualized rate in the third quarter, above the roughly 3.2% economists expected and up from 2.2% in the second quarter. Consumer spending rose 3.8%, matching the prior quarter's pace, led by health care and restaurants.
Investment in information processing equipment, which includes the computers and servers used in AI data centers, rose 37.4%, while residential investment declined as high mortgage rates weighed on housing. Real final sales to private domestic purchasers, which exclude volatile categories like trade, inventories, and government spending, increased 4.9%.
Why it matters: Underlying private demand outpaced the headline number. That means the quarter's strength came from households and businesses, not temporary swings in trade or inventories.
Inflation Picks Up as Real Spending Stalls
The PCE price index, the Fed's preferred inflation measure, rose 3.6% from a year earlier in September, up from 3.4% in August. Core PCE, which excludes food and energy, climbed to 3.1%, in line with expectations.
Consumer spending grew 0.5% for the month but was essentially flat after adjusting for inflation. Real disposable income fell -0.3%, and the personal saving rate dropped to 3.8%, its lowest level since 2022, as households saved less to keep spending.
Why it matters: The strong quarter ended on a softer note. Rising prices absorbed the gains in household spending and left consumers with a thinner savings cushion.
Fed Holds, but Two Officials Vote to Hike
The Fed kept its target range at 3.75% to 4.00% after raising rates in September, but two members dissented in favor of a quarter-point increase. The statement said economic activity is "expanding at a strong pace" and inflation "remains elevated," while Chair Kevin Warsh declined to signal the next move.
Markets raised the odds of a December hike to about 80%, according to CME FedWatch. Longer-term Treasury yields rose after the decision, and the 10-year yield closed above 5% on Wednesday.
Why it matters: The dissents show that support for further tightening extends beyond a single official. That's why markets now treat a December hike as the most likely outcome.
Investors Sort AI Spenders by Cash Flow
Alphabet shares fell more than -10% on Thursday after the company reported a second straight quarter of negative free cash flow, as quarterly capital spending of more than $51 billion outpaced the cash its business generated.
Microsoft, by contrast, reported 48% growth in its Azure cloud business along with positive free cash flow, and its shares held up far better. Earlier in the week, Oracle jumped more than 10% after capping how much new capital it plans to raise.
Meanwhile, AI financing keeps growing. Meta launched a stock sale of up to $95 billion to fund new data centers, AI developer Anthropic filed to go public, and Microsoft announced plans to issue $25 billion of debt.
Why it matters: After weeks of focus on how the AI buildout gets financed, investors are rewarding the companies that can pay for it from their own cash flow.
Weekly Market Update: Investors Rotate Away From Tech as Inflation Heats Up
Markets were mixed this week as technology and growth stocks declined while value and defensive sectors traded higher. The S&P 500 fell -0.3%, the Nasdaq declined -2.6%, and the Russell 2000 small-cap index slipped -1.0%.
However, the Equal-Weight S&P 500 gained 1.3%, and Value 1.6% outperformed Growth -2.3%, signaling broader participation and a rotation beneath the major indexes. Health Care 5.6% and Consumer Staples 3.9% led, with nine of the eleven S&P 500 sectors finishing higher. Technology -4.4% significantly underperformed.
Bonds rallied as Treasury yields declined, with longer-maturity Treasuries gaining 2.7%. Investment-grade corporate bonds gained 1.0% and outperformed high-yield bonds, which were flat as credit spreads widened. Oil rose 6.8%, while the U.S. dollar and Bitcoin were little changed.
Key Takeaways
Energy Pushes Inflation Higher
The Consumer Price Index (CPI) rose 0.6% in September, lifting year-over-year inflation from 3.4% in August to 3.7%. Gasoline prices jumped 9.1% month-over-month, accounting for more than half the monthly increase. Underlying inflation also firmed.
Core CPI, which excludes food and energy, rose 0.3%, slightly above expectations. Producer prices climbed 1.3% for the month, their largest gain since March 2022, reflecting both rising energy costs and broader price pressures.
Why it matters: The combination of persistent inflation and slower hiring complicates the Federal Reserve's efforts to balance price stability with economic growth.
Spending Beats Expectations, Helped by Gas Prices

Retail sales rose 0.8% month-over-month in September, beating expectations for a 0.3% gain, and August's increase was revised higher to 1.3%. Part of that strength reflected gasoline prices. Retail sales aren't adjusted for inflation, so higher fuel prices can lift reported spending, and sales at gas stations rose 6.4% in September.
Excluding gas stations, retail sales increased 0.2%. Spending at restaurants and other retailers stayed positive, suggesting consumers kept buying despite higher costs.
Why it matters: The report points to continued consumer spending, although growth outside gas stations wasn't as strong as the headline suggested.
AI Borrowing Comes Under Scrutiny
AI-related stocks declined sharply this week as investors grew more concerned about the heavy borrowing behind AI infrastructure. CoreWeave, a major provider of AI computing capacity, fell roughly -15% on Wednesday. Yields on some of its bonds approached 15%. That's a sign investors are demanding much higher compensation to lend to the company.
Building AI infrastructure takes enormous upfront spending on data centers, specialized chips, and electricity, and some companies are borrowing heavily to fund it. The sell-off came even though semiconductor manufacturers reported strong earnings.
Why it matters: Demand for AI computing and infrastructure remains strong, but higher borrowing costs have increased scrutiny of how companies are paying for that buildout.
Bank Earnings Point to a Resilient Economy
Third-quarter bank results showed continued growth in credit and debit card spending, adding to evidence that consumers remained active. Credit quality was also solid. Borrowers generally kept up with their payments, and loan losses stayed contained despite rising interest rates.
Bank leaders said consumers and businesses were holding up well, though they acknowledged challenges from inflation and higher borrowing costs.
Why it matters: Taken together, the results suggest consumers and businesses remain relatively resilient despite higher interest rates, elevated oil prices, and persistent inflation.


Quarterly Market Update: Solid Fundamentals Meet Higher Oil and Rates
The third quarter put two forces against each other. On one side, the economy and corporate earnings stayed solid. On the other, oil and interest rates pushed back. Oil climbed back above $100 per barrel, inflation stayed elevated, Treasury yields surged, and the Federal Reserve raised rates in September.
The S&P 500 still finished higher and set a new all-time high, carried by strong earnings and steady economic activity. But the headline gain didn't tell the whole story. Beneath it, market leadership narrowed as smaller companies and rate-sensitive areas lagged.
Artificial intelligence, meanwhile, kept playing a large role in both the economy and the markets. In this letter, we'll look at the forces pushing interest rates higher, the economic and earnings strength helping offset that pressure, and how AI's influence now reaches everyday borrowing costs, business investment, and the stock market.
Oil Stays Volatile, and the Fed Hikes
Oil was once again one of the quarter's main drivers. Its sharp swings carried implications well beyond energy, touching inflation, interest rates, and economic growth.
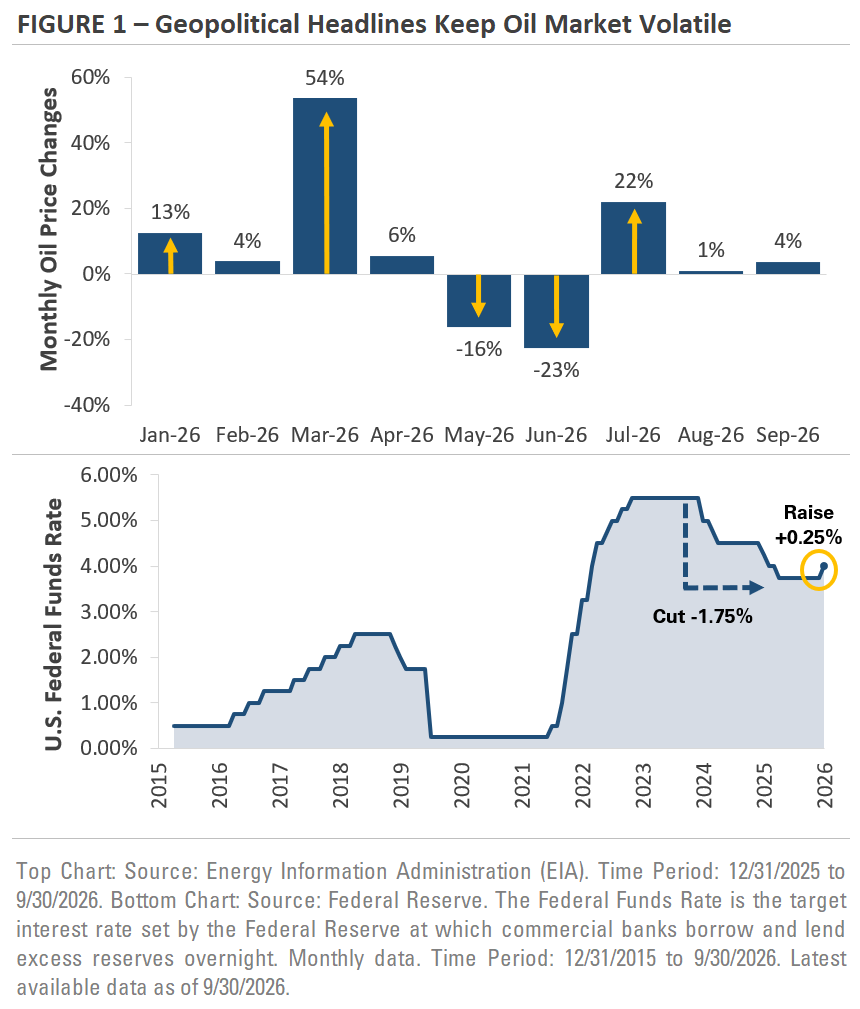
The top chart in Figure 1 graphs the monthly change in oil prices this year, and what stands out is how often prices have changed direction.
Oil surged early in the year, fell sharply in May and June, then reversed higher again in Q3, jumping 22% in July alone. The point isn't any single monthly move. It's how frequently the direction has flipped.
Most of that volatility traces back to shifting expectations for Middle East oil supplies and the uncertainty around the Strait of Hormuz. And those swings matter well beyond the energy market.
That's because oil feeds into gasoline and transportation costs, those costs feed into inflation, and inflation ultimately shapes the outlook for interest rates and growth. When oil fell in Q2, some of that pressure eased. When prices climbed again in Q3, concerns about inflation and the path of rates came right back.
That shift had a real impact on the rate outlook. Earlier in the year, investors were focused on how much the Fed could lower rates. But as oil rebounded and inflation stayed above the Fed's target, the conversation gradually turned to whether policymakers would need to raise rates instead.
The bottom chart in Figure 1 shows how that played out. The Fed cut rates by a cumulative 1.75% beginning in September 2024, then held steady for most of this year. After a nine-month pause, it raised rates 0.25% in September, its first increase since 2023.
Markets now expect additional hikes in the coming quarters, although those expectations have shifted often this year. The broader point is that the path for rates remains closely tied to how inflation, oil, and economic growth develop into year-end and early 2027.

Earnings and Growth Hold the Line
So far, that sounds like a difficult backdrop. And in some ways, it was. Yet the underlying data told a steadier story. Corporate earnings stayed strong, and households and businesses kept spending, giving the stock market real fundamental support through the quarter's uncertainty.
The top chart in Figure 2 graphs the year-over-year growth rate of S&P 500 earnings going back to 2001. Over the past year, 12-month earnings for the S&P 500 grew nearly 30%.
Outside of the rebounds that followed the financial crisis and COVID, that's one of the strongest stretches of earnings growth on the chart, and a significant step up from the single-digit pace of 2023 and 2024. So while the macro backdrop was volatile, corporate profits kept growing at a strong pace.
The bottom chart looks beneath headline GDP to show what households and businesses were actually doing. Headline GDP includes volatile categories such as trade, inventories, and government spending. Final sales to private purchasers, on the other hand, focuses on consumer spending and private investment.
Comparing the two helps separate changes in the underlying economy from temporary swings. In the second quarter, headline GDP grew at a 2.2% annualized rate, down from 2.5% in Q1. Underlying private demand, however, grew 4.6%. That gap suggests households and businesses were still spending and investing at a healthy pace, even as the broader backdrop grew more volatile.
Taken together, the two charts help explain how markets absorbed the quarter's volatility. Consumers are still spending, businesses are still investing, and earnings are still strong. That combination has served as a counterweight to higher oil prices, persistent inflation, and rising interest rates.
AI's Reach Keeps Widening
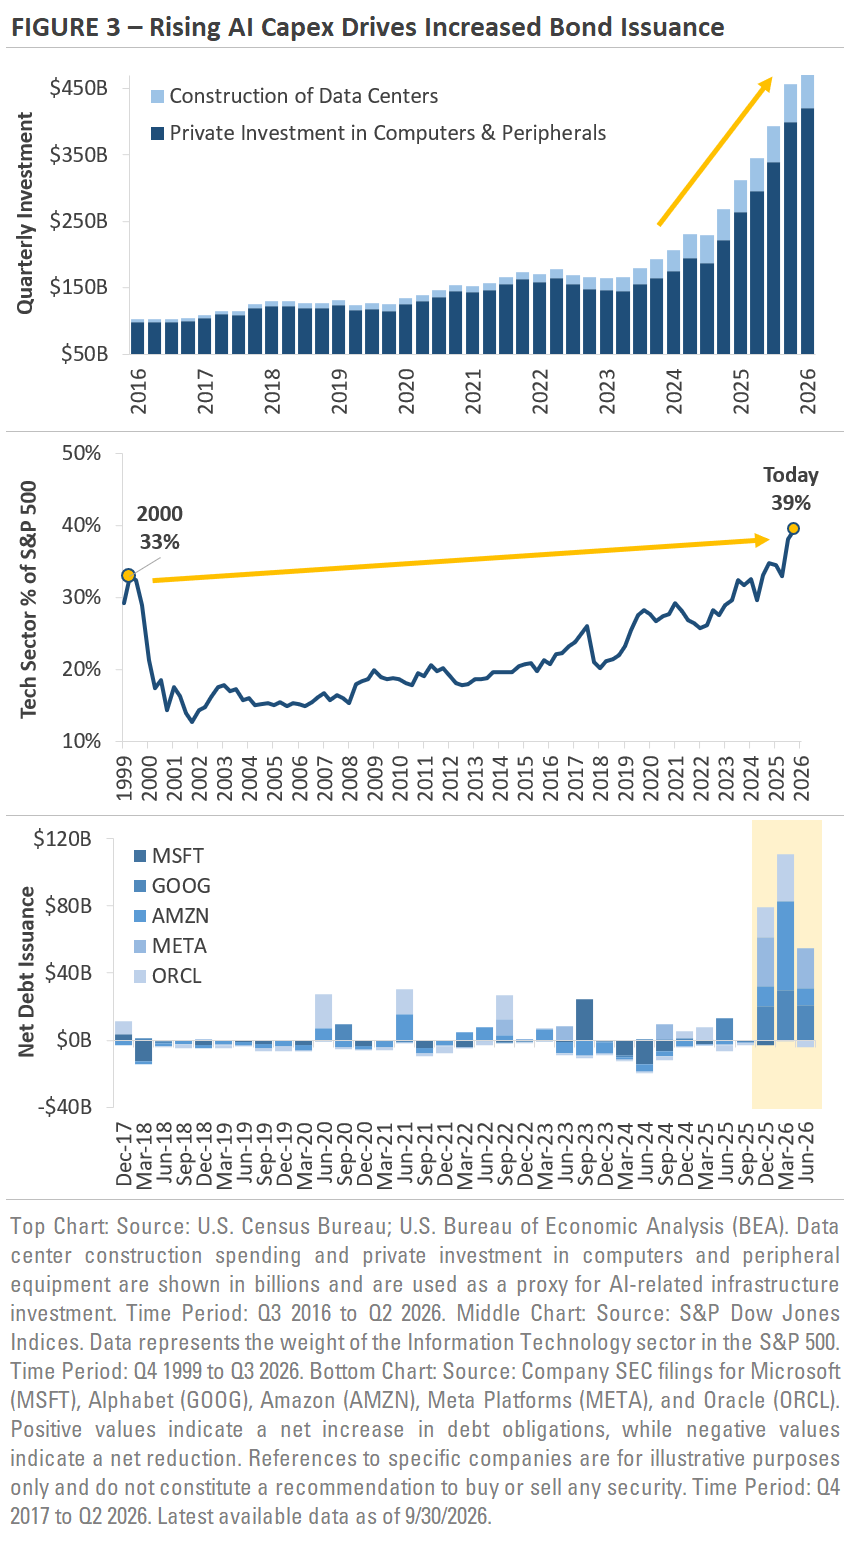
Which brings us to the theme running through much of the year. Artificial intelligence has been a major market story for several years. What's changed is the scale of the buildout, which is making AI more important to the broader economy and financial markets. Figure 3 shows three ways its influence is expanding: business investment, the stock market, and financing.
Start with business investment. The top chart graphs spending on data-center construction and computer equipment, which together serve as a proxy for the physical infrastructure being built to support AI.
Combined investment has grown from roughly $180 billion at the end of 2023 to nearly $490 billion today. That makes AI-related infrastructure an important source of business investment in its own right.
Next is the stock market. The middle chart shows that Technology now makes up nearly 40% of the S&P 500, up from about 34% at the end of 2025.
As that share has grown, the index has become more sensitive to the performance of its largest sector. What this means is that strong AI-related earnings and stock gains can have an outsized influence on the broader index.
And then there's financing. Major U.S. tech companies remain highly profitable, but the scale of their AI investment programs has grown quickly. The bottom chart shows that several of these companies are increasingly turning to the bond market to help fund the buildout. Historically, the group was fairly balanced between issuing new debt and paying it down. The right side of the chart, though, shows a significant jump in new issuance.
The question isn't just how much is being spent on AI anymore. It's how far that spending now reaches. The buildout is supporting business investment, drawing on the bond market for financing, and carrying more weight in the stock market, all at the same time.
AI has moved well beyond a narrow technology theme, and its growing scale means it's now influencing several parts of the economy and financial markets at once.
Equity Market Recap: Leadership Narrows as Rates Rise
The S&P 500 finished Q3 higher and set a new all-time high, but the path there was uneven, and the divergence beneath the index grew as the quarter went on.
Stocks faced some early pressure before rebounding in August, when the Russell 2000, the Dow Jones, and the equal-weight S&P 500 each set new highs. From there, leadership narrowed as larger companies outpaced smaller ones into quarter-end.
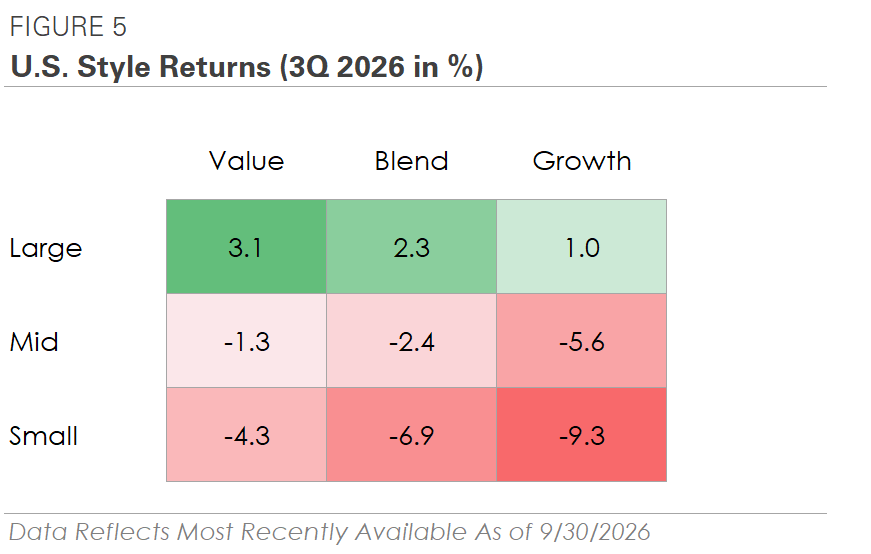
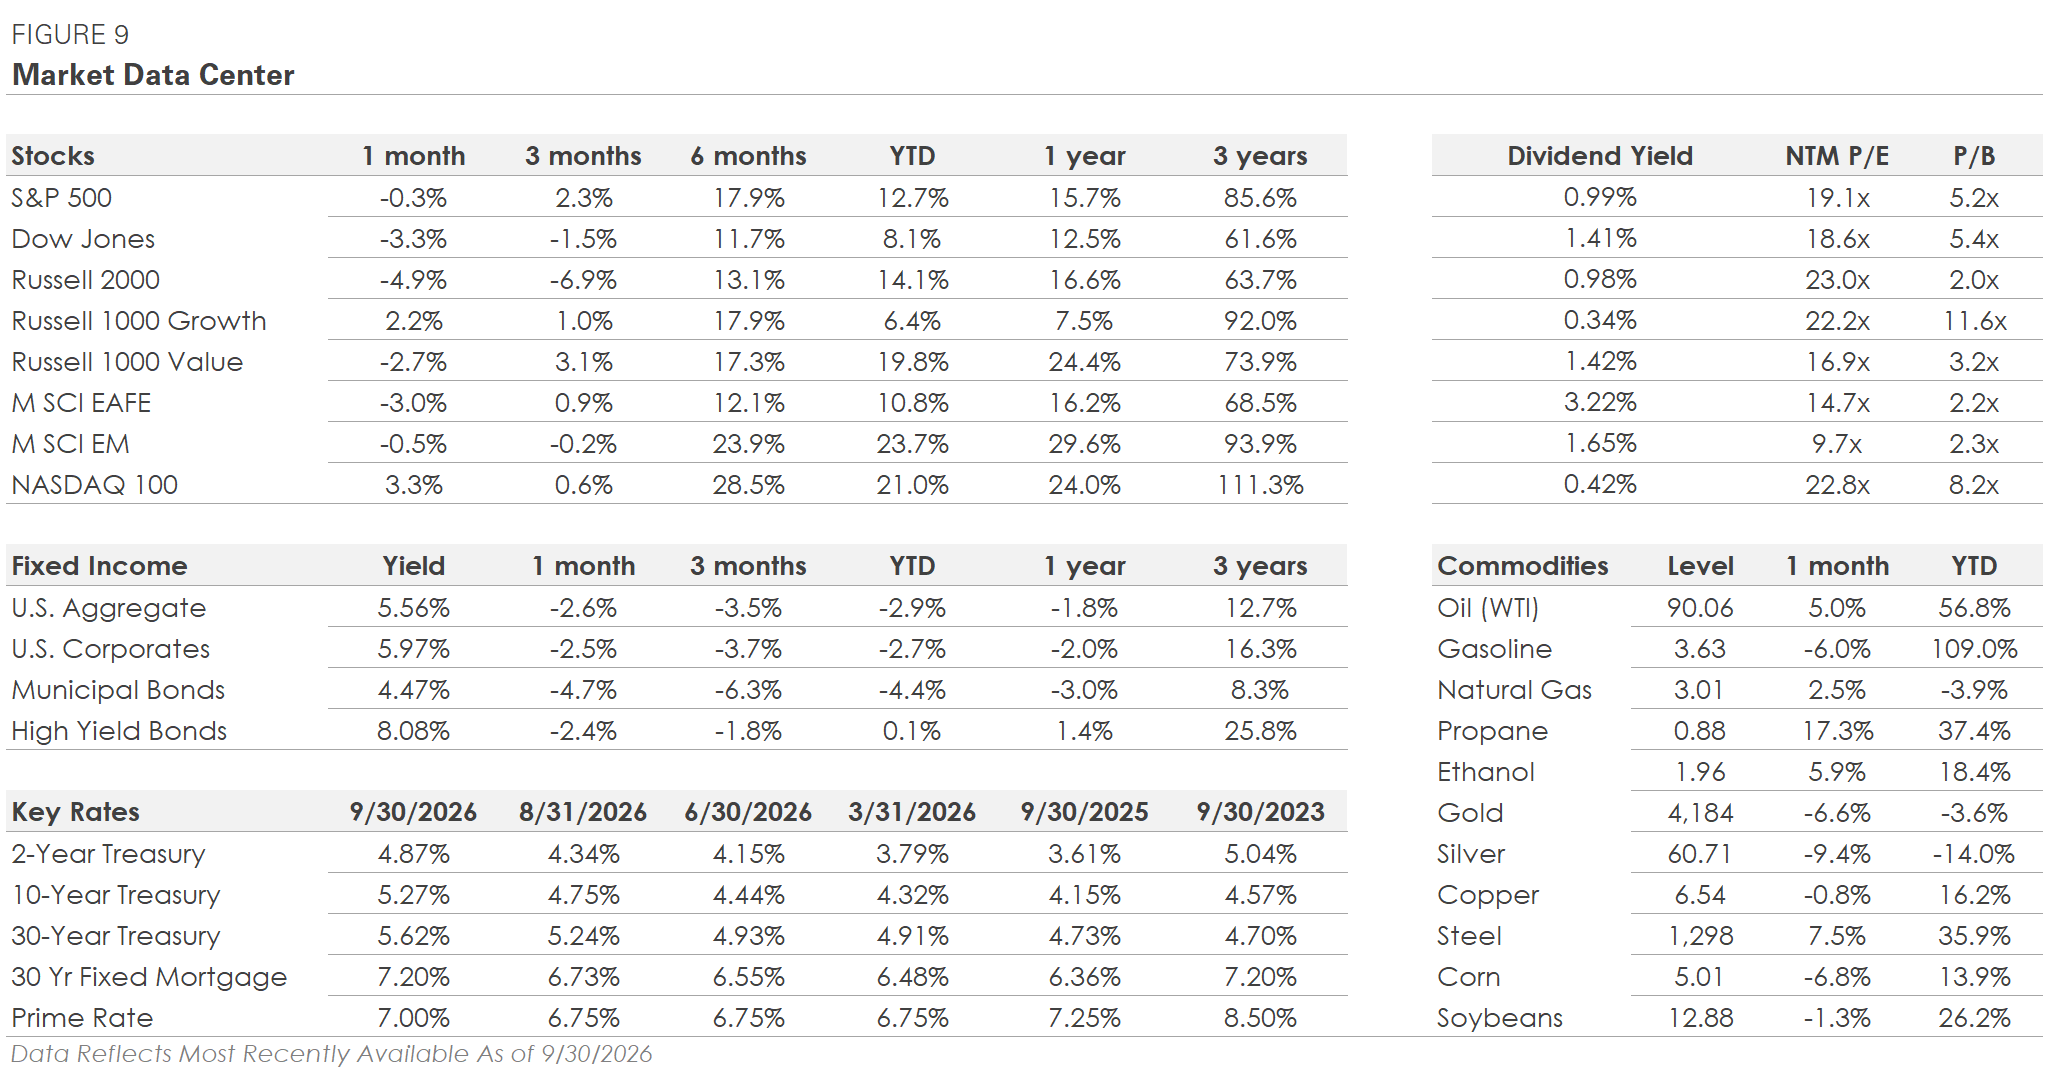
The S&P 500 gained 2.3% for the quarter, compared with 0.6% for the Nasdaq 100, -1.5% for the Dow Jones, and -6.9% for the Russell 2000. Most of that gap opened up in the second half of the quarter, which overlapped with a sharp rise in Treasury yields.
The timing suggests rising rates contributed to the divergence. That's because smaller companies tend to be more sensitive to borrowing costs.
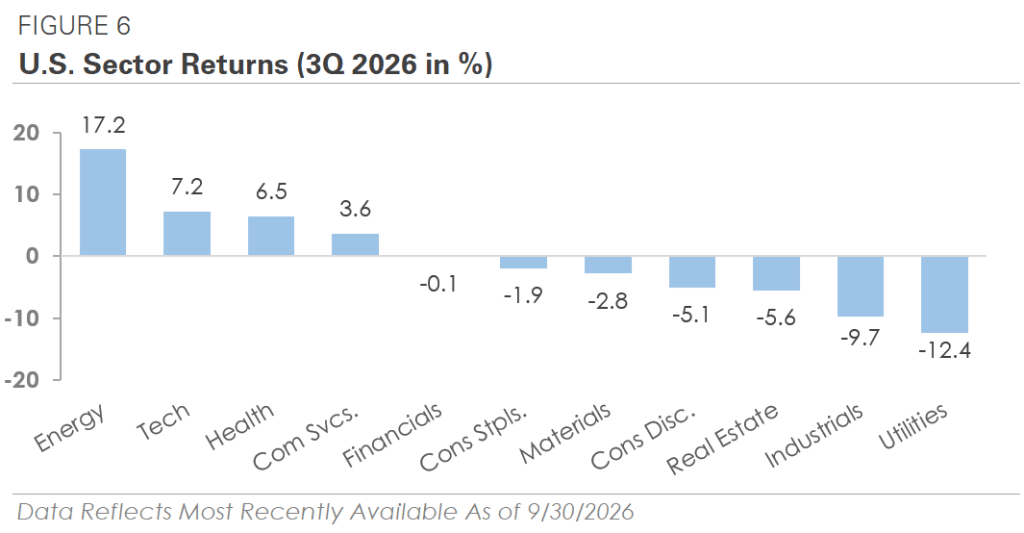
Sector performance reflected many of the quarter's main themes. Only four of the eleven S&P 500 sectors outperformed the broad index, a sign of narrow breadth. Energy led with a 17.2% gain as oil climbed from roughly $70 per barrel in early July to more than $100 by mid-September.
That's a sharp reversal from Q2, when Energy was the worst-performing sector as oil prices fell. Technology came in second with a 7.2% gain, followed by Health Care at 6.5% and Communication Services at 3.6%. On the other end, Utilities fell -12.4% as rates rose, while Industrials dropped -9.7% and Real Estate declined -5.6%.
International markets were relatively quiet after their gains in the first half of the year. Developed and emerging market stocks each finished the quarter within 1% of where they started, with developed modestly ahead of emerging.
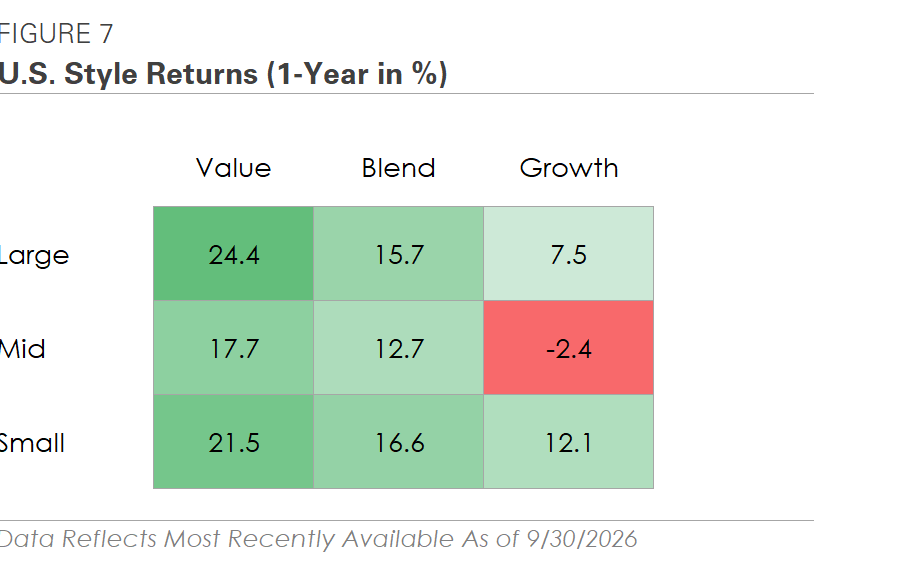
Even so, both regions are up year-to-date and are still outperforming the S&P 500 over the past 12 months.
All told, the quarter left a mixed picture beneath the major indexes. The S&P 500 reached a new high, while smaller companies and several rate-sensitive areas moved lower as yields rose late in the quarter.
Leadership is narrower now than it was in August, though the major U.S. equity indexes remain higher year-to-date.
Credit Market Recap: Rising Rates Weigh on Bonds
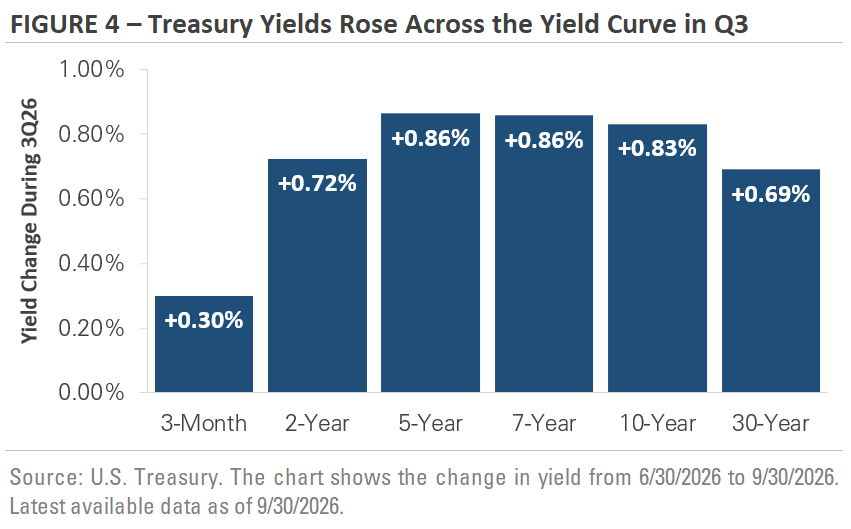
The same rise in yields that pressured smaller stocks made Q3 a challenging quarter for bonds. Figure 4 graphs the change in Treasury yields across maturities during the quarter, and yields rose at every one. The 5-year, 7-year, and 10-year yields each climbed more than 0.80%, and the 30-year rose nearly 0.70%.
Longer-maturity bonds underperformed because they're more sensitive to changes in interest rates. Shorter-maturity Treasuries held up better on a relative basis, though they still traded lower.
Corporate bonds came under pressure too, although they outperformed government bonds. High-yield posted a total return of -1.8%, ahead of investment-grade's -3.7%. Investment-grade took the bigger hit because its longer maturities made it more sensitive to rising rates.
For most of the quarter, though, the main headwind was rising interest rates, not weakening credit conditions. Investment-grade and broad high-yield spreads stayed relatively stable and tight by historical standards, suggesting investors remained comfortable with corporate fundamentals even as borrowing costs climbed.
The clearest sign of caution showed up at the lowest-quality end of the high-yield market. Spreads on CCC-rated bonds, the lowest-rated tier of high-yield, widened even as spreads on higher-quality high-yield bonds held steady. In other words, investors started demanding more compensation to hold the debt of financially weaker borrowers. Broader high-yield spreads, which had been comparatively calm for most of the quarter, also began to widen in late September.
The market grew more selective as the quarter went on, and the impact of higher financing costs showed up first among the most sensitive borrowers.
Put simply, Q3's weakness in bonds came mainly from rising Treasury yields, not a broad deterioration in corporate credit.
The late-quarter widening was concentrated among the lowest-quality borrowers, while investment-grade and broader high-yield spreads stayed relatively contained. Higher financing costs were creating pressure in pockets of the market, not across all of it.

2026 Outlook: What to Watch in Q4
Economic growth and corporate earnings remain strong heading into the fourth quarter, even as higher oil prices and interest rates have made the backdrop more mixed and volatile.
One of the main questions now is whether that underlying strength holds up as households and businesses adjust to higher borrowing costs, persistent inflation pressure, and continued uncertainty around energy prices.
So far, the economy has handled those pressures relatively well. Consumers have kept spending, businesses have kept investing, and unemployment has stayed low.
Those trends have supported growth even as rates and borrowing costs moved higher.
The coming months will show whether that momentum continues, particularly in the data tracking consumer spending, hiring, and business investment.
Corporate earnings will be another important source of information. Profit growth has been strong over the past year and has given the market fundamental support through a volatile macro backdrop.
Third-quarter earnings season, which begins in October, will offer an updated look at how companies are managing higher interest rates, changing input costs, and continued investment while still growing revenue and profits.
The AI investment cycle will remain part of the discussion as well. Spending on data centers, computing equipment, and related infrastructure continues to support business investment, and large technology companies are increasingly using the bond market to help pay for it.
As the cycle matures, the focus is likely to broaden from how much is being spent to what that investment is producing in revenue, profits, and productivity.
Markets have absorbed several changes this year without losing the support of economic growth and corporate earnings. We'll continue watching how these trends develop, while keeping the focus on portfolio diversification, discipline, and meeting your long-term financial goals across a range of possible outcomes.
Weekly Market Update: Long-Term Yields Climb as Tech Leads
Markets were mixed this week as gains in large-cap technology stocks offset broader market weakness, while long-term Treasury yields rose sharply.
The S&P 500 gained 0.9% and the Nasdaq rose 3.5%, while the Russell 2000 small-cap index fell -1.3%. Growth 2.5% outperformed Value -0.7%, and the Equal-Weight S&P 500 declined -1.0%, signaling narrow leadership.
Technology led all sectors with a 3.6% return, while Utilities -4.4%, Energy -2.3%, Financials -2.1%, and Real Estate -1.8% lagged the market.
Bonds declined as Treasury yields rose across the yield curve, with long-maturity Treasuries falling -2.8% and investment-grade bonds declining -1.9%. The U.S. dollar strengthened 1.0% as rates rose, oil declined -2.0% despite intra-week volatility, and Bitcoin gained 10%.
Key Takeaways
Consumer Sentiment Nears Its Record Low
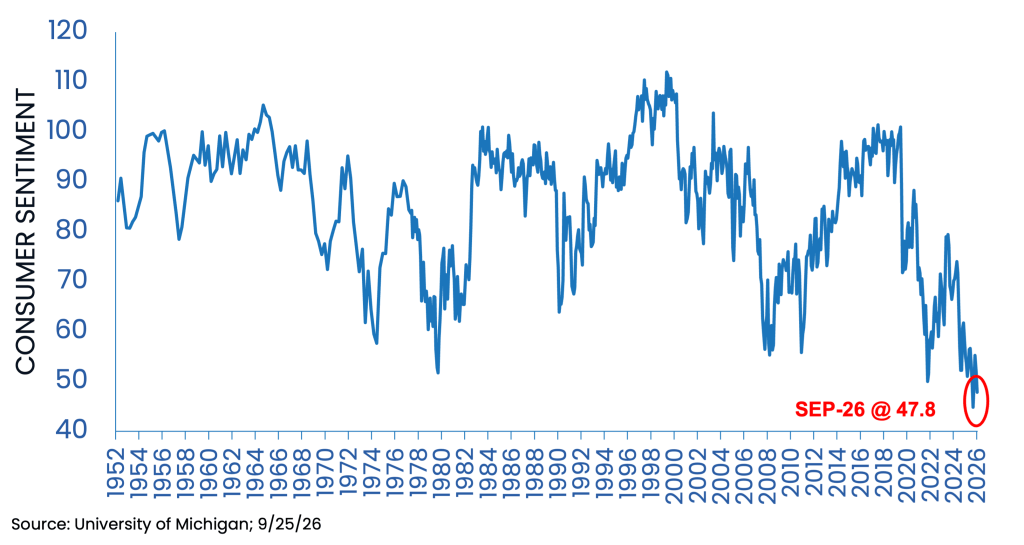
The preliminary University of Michigan Consumer Sentiment Index fell to 47.8 from 51.7, moving back toward the record low set in May. Consumers grew notably less optimistic about their personal finances and future business conditions, and one-year inflation expectations rose to 4.6% as higher fuel prices and trade-related concerns added to worries about household costs.
The weaker sentiment contrasts with recent data showing that consumers continue to spend despite a more cautious mood.
Why it matters: Consumers remain active, but they're increasingly concerned about inflation, borrowing costs, and the outlook for their finances and the broader economy.
Long-Term Yields Keep Climbing
The 10-year Treasury yield approached 5.15%, its highest level since 2007, while the 30-year climbed above 5.40%, its highest since 2004. Several factors contributed to the continued rise, including stronger economic data, persistent inflation pressure, higher oil prices, and heavy Treasury issuance.
Why it matters: The move is notable not just because yields are high, but because of how fast they've risen. The faster rates move, the more quickly markets have to adjust expectations for economic growth, inflation, and borrowing costs, which can increase volatility.
Business Activity Picks Up, Price Pressures Persist
The preliminary S&P Global U.S. Composite Purchasing Managers Index rose to 58.4 in September from 56.0 in August, well above expectations and its strongest reading since 2021. Businesses reported the fastest hiring in more than four years, while input costs rose at their quickest pace in four years. The index is based on a survey of businesses rather than hard economic data, but it provides an early read on how activity is changing.
Why it matters: The survey suggests economic activity remains solid. The combination of firm activity and persistent price pressures is contributing to higher Treasury yields and reinforcing expectations that the Fed may need to keep rates elevated or tighten further.
Meta's Muse Lifts AI, Weighs on Consumer Businesses
Muse, Meta's new personal AI agent, surpassed ChatGPT to become the top free app in the U.S. Meta shares rose sharply, the Nasdaq set a new all-time high, and semiconductor stocks rallied as investors considered how AI agents could increase demand for computing power.
The launch also pressured travel, financial, insurance, and other consumer-facing stocks, as investors questioned whether AI agents could make it easier for customers to compare prices, negotiate bills, and switch providers.
Why it matters: Strong early adoption reinforces the case for continued demand for AI infrastructure, but the reaction across travel, financials, and other industries shows that investors are still determining who ultimately benefits and who faces disruption.
Weekly Market Update: Oil and Yields Pressure Markets Ahead of the Fed
Markets traded lower this week as rising oil prices and long-term interest rates weighed on risk assets.
The S&P 500 fell 2.0%, the Nasdaq declined 1.2%, and the Russell 2000 small-cap index returned -2.6%. Growth (-1.7%) outperformed Value (-2.4%), while the Equal-Weight S&P 500 fell 3.1%, signaling broad weakness beneath the major indexes.
Energy (+0.7%) was the only sector to finish higher, while Technology was nearly flat. Health Care (-4.3%), Consumer Discretionary (-3.9%), and Materials (-3.6%) led to the downside.
Bonds declined as Treasury yields rose, with long-maturity Treasuries falling 1.7% and the 10-year yield approaching 5%. Corporate bonds also declined but outperformed Treasuries. Oil surged 12.5%, volatility increased, the U.S. dollar was little changed, and Bitcoin fell nearly 6% after a 20% rally.

Key Takeaways
Labor Conditions Improved in August After Several Weak Months of Hiring
Employers added 162,000 jobs, while the unemployment rate held at 4.1%. Prior months also looked better after revisions: June payroll growth was raised to +31,000 from +20,000, and July was revised from an initially reported -23,000 jobs to +21,000. Combined, the revisions added 55,000 jobs to the previous two months. The report does not suggest the labor market has returned to the strength of earlier years, but it paints a less concerning picture than investors saw after July's initial release.
Why it matters: The labor market still appears to be cooling, but August suggests that deterioration is occurring more gradually than previously feared.
Middle East Conflict is Becoming Harder for Markets to Treat as a Temporary Disruption
Oil prices moved sharply higher as fighting intensified and disruptions to energy shipments through the Strait of Hormuz continued. U.S. crude moved back above $100 per barrel after falling substantially earlier in the summer. More importantly, repeated escalations are making it harder to assume that each increase in energy prices will quickly unwind.
Why it matters: The longer the disruption persists, the more relevant energy becomes as an ongoing source of inflation uncertainty rather than a series of isolated weekly price swings.
Long-Term Borrowing Costs Continue to Rise Across Global Bond Markets
The 10-year Treasury yield climbed above 4.90% this week, its highest level since October 2023, while the 30-year moved above 5.3%. Government-bond yields also rose across several major developed markets as investors weighed inflation, higher energy costs, government borrowing needs, and tighter monetary policy. The breadth of the move suggests that higher long-term rates are not simply a reaction to one U.S. economic report or a shift in Fed expectations.
Why it matters: A wider set of global forces is putting upward pressure on long-term borrowing costs, making it harder to attribute elevated yields to any single economic report or shift in central-bank policy.
Expectations for a Rate Hike at Next Week's Fed Meeting Continue to Build
The Fed held rates at 3.50% to 3.75% in July, although three policymakers preferred a 0.25% hike. At Jackson Hole, Chair Warsh described the labor market as stable and said inflation should remain the Fed's predominant focus. Since then, stronger August job growth, higher oil prices, and renewed producer-price pressure have strengthened the case for an increase. Futures markets now place roughly a 70% probability on a +0.25% move at the September 15 to 16 meeting.
Why it matters: Next week's decision will show whether firmer labor data and persistent inflation pressure have been enough to move the Fed from considering a rate hike to delivering one.
AI Infrastructure Spending Remains Resilient Despite Volatile Macro Backdrop
Oil prices and long-term yields have risen, inflation pressure has increased, and the market expects a Fed hike. Those shifts would normally make large capital projects more expensive and could lead companies to reconsider spending plans. So far, however, the largest tech companies have continued committing substantial capital to data centers, computing capacity, and other AI infrastructure.
Why it matters: AI investment has become a significant contributor to both economic growth and corporate earnings, and so far, the largest tech companies appear willing to continue that spending despite volatility in rates, energy prices, and inflation.
Monthly Market Update: Stocks Set Broad Records as Rates Climb
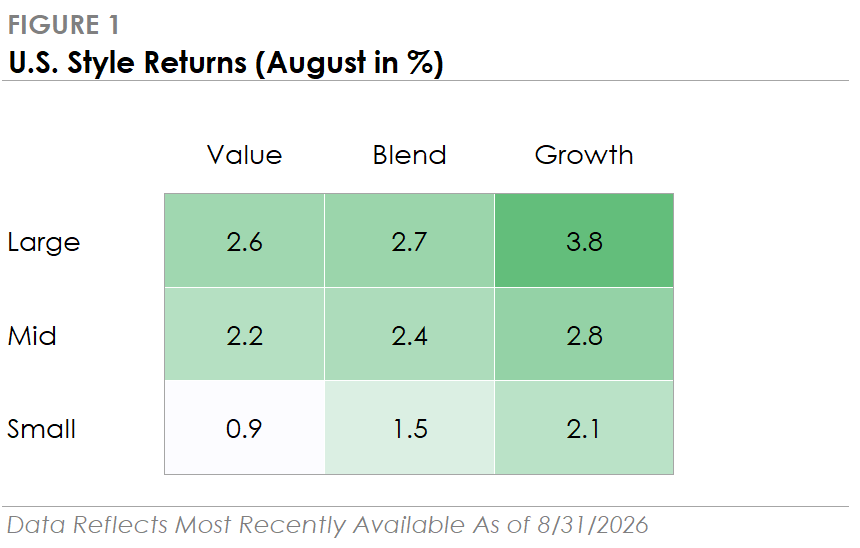
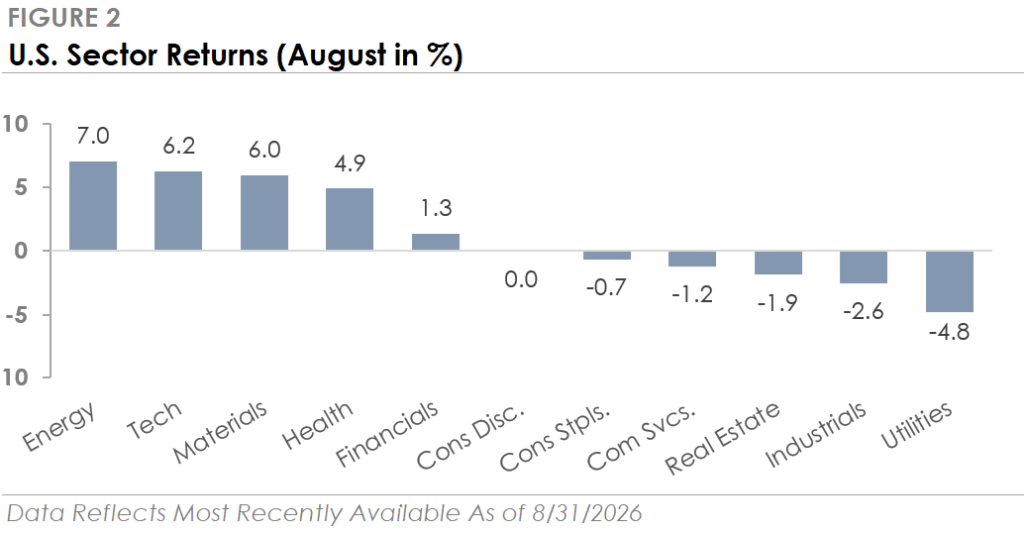
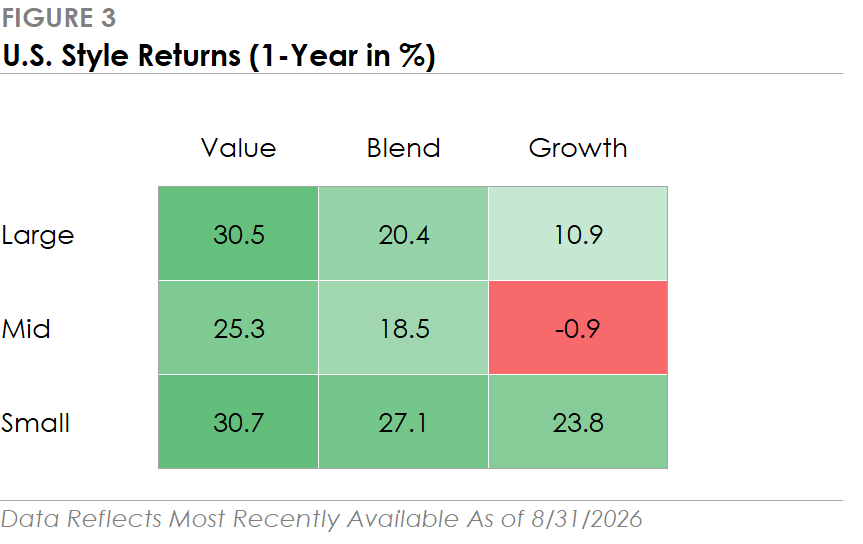
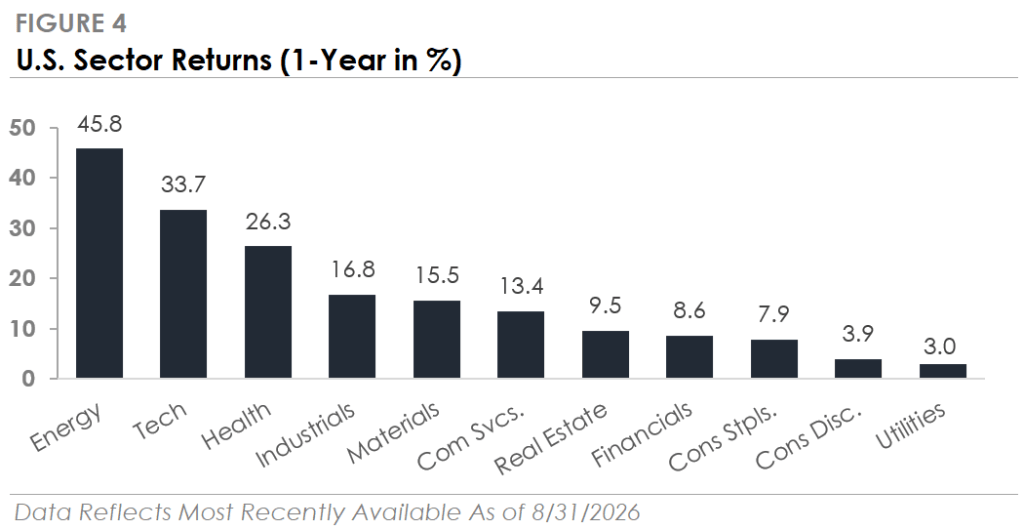
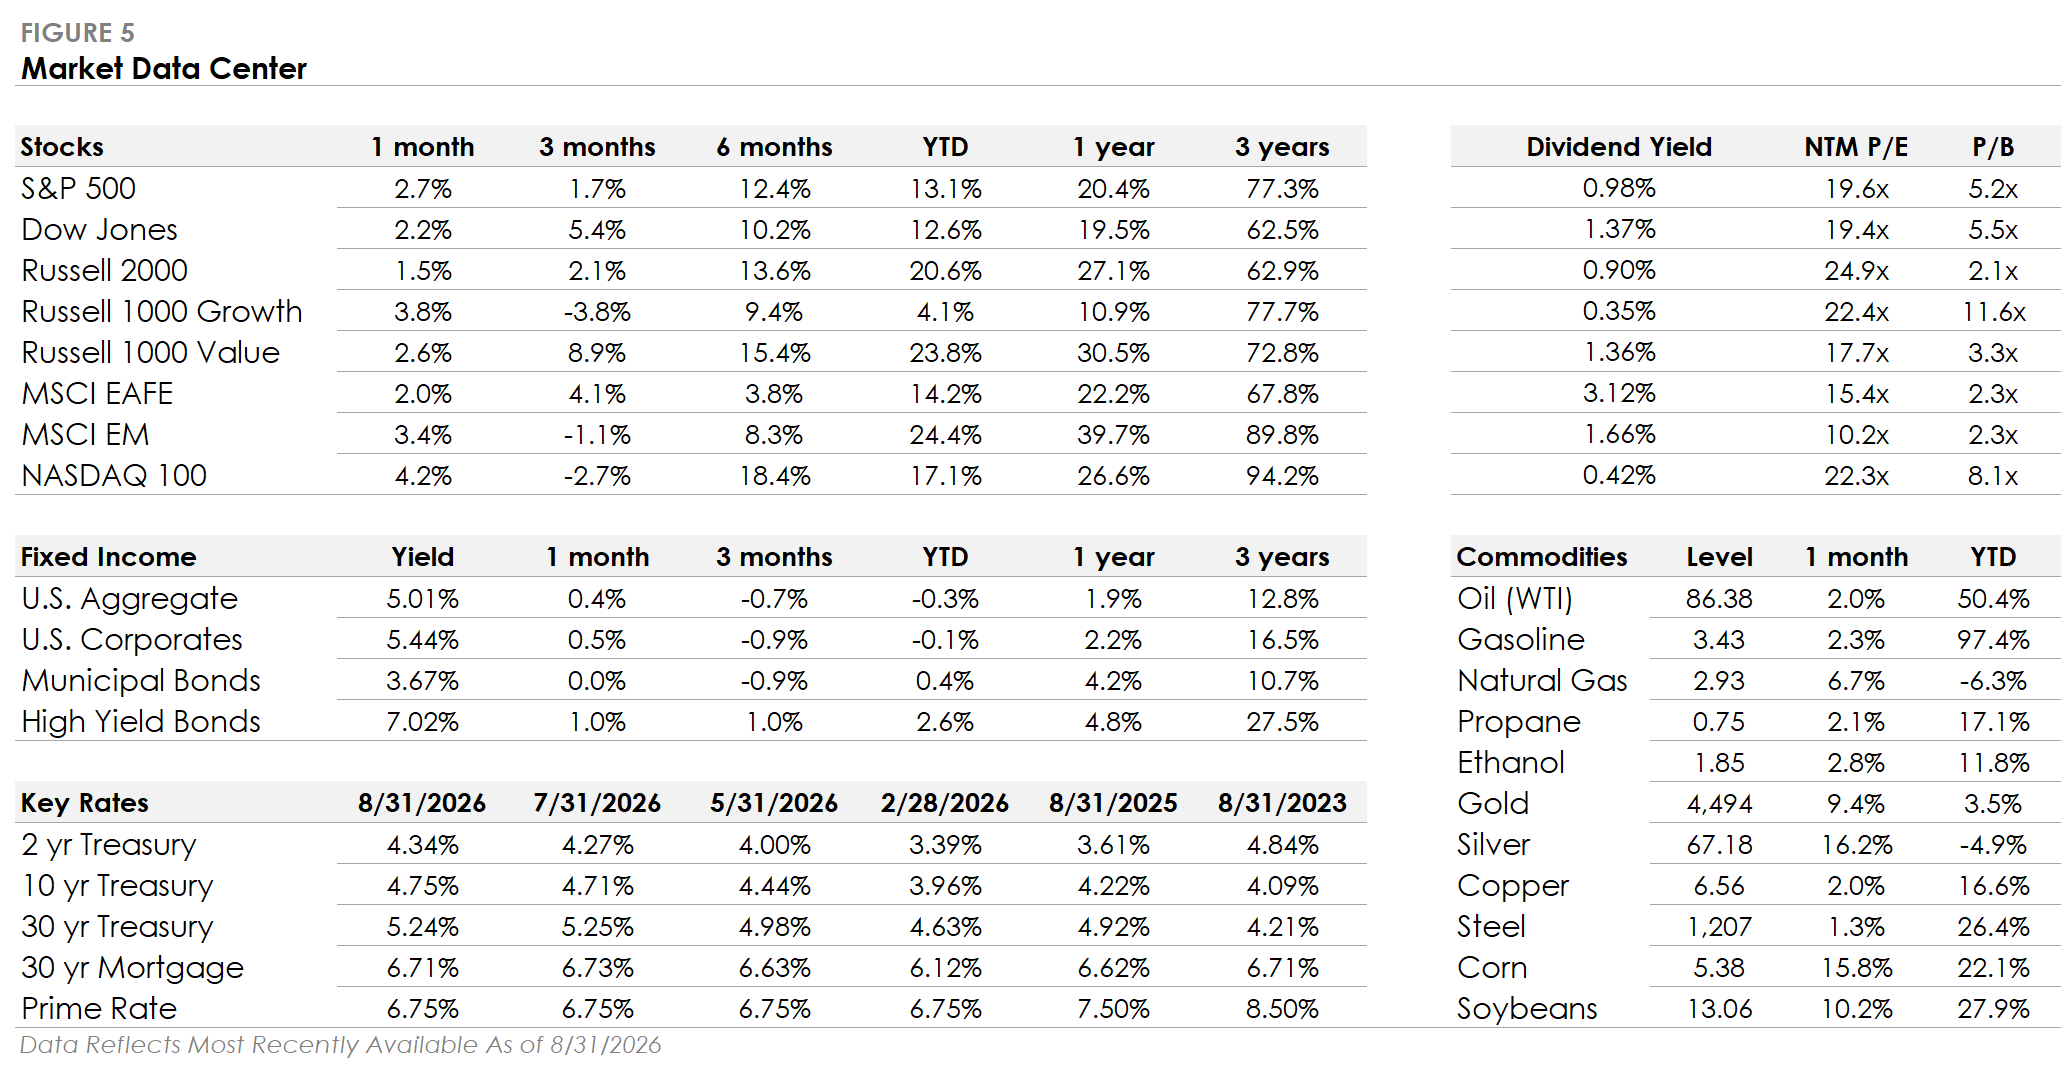
The S&P 500 Index returned +2.7% in August and set a new high. Five of the eleven S&P 500 sectors traded higher, with four outperforming the broad index. Energy (+7.0%) led all sectors, followed by Technology (+6.2%) as the sector rebounded from a July selloff and Materials (+6.0%) as gold gained nearly 10%. Utilities (-4.8%) led to the downside, followed by Industrials (-2.6%) and Real Estate (-1.9%).
Bonds traded higher despite Treasury yields rising throughout the month, with the U.S. Bond Aggregate returning +0.4%. Investment-grade corporate bonds modestly outperformed with a +0.5% total return, while high-yield gained 1.0%.
International stocks traded higher in August. Developed markets gained 2.0% and underperformed the S&P 500, while emerging markets returned +3.4% and outperformed as international tech stocks rebounded alongside U.S. tech stocks.
Stocks Set New Highs as Rates Climb
Equity markets traded higher in August, with strength extending across most broad stock market indexes. The S&P 500, Dow Jones, Russell 2000, and equal-weight S&P 500 all set new all-time highs during the month, and the Nasdaq 100 approached its June high.
The breadth of records was notable because the indexes capture very different parts of the market, from mega-cap tech to small-caps and the average S&P 500 company.
Market leadership has shifted multiple times this year, alternating between broad participation and concentration. August looked different, with strength spread across a wide range of companies and equity market segments.
The bond market offered a counterpoint to the strength in stocks. Treasury yields faced broad upward pressure during August, with the 10-year yield climbing above 4.75%, the highest since January 2025, and the 30-year approaching 5.30%, its highest level since 2007.
The rise in longer-term yields reflected several concerns, including persistent inflation, elevated government borrowing, and renewed uncertainty around energy prices.
Near the end of the month, Fed Chair Kevin Warsh's Jackson Hole speech signaled that the Fed's next move could be a rate hike rather than a rate cut, which added further upward pressure on Treasury yields. Despite the rate volatility, corporate credit spreads remained relatively calm and sit near record lows, suggesting investors are more concerned about the path of interest rates than companies' ability to repay their debt.
Markets Learn to Live with Headline Volatility
Geopolitics have dominated headlines this year, but their impact has changed as the year progresses. Oil prices continue to move when Middle East developments alter the outlook for global energy supply.
The difference is that investors appear less willing to treat each new headline as an economic shock. Earlier this year, the start of the conflict and disruption in the Strait of Hormuz caused oil prices to surge and contributed to a broad stock market selloff. Since then, investors have experienced several rounds of escalation and de-escalation.
Oil still jumps on new developments, but markets are increasingly waiting for evidence that a headline will affect energy supply, inflation, and economic growth before reacting as dramatically as they did in March.
Artificial intelligence is the second dominant market theme. Investors continue to debate whether the large sums being spent on data centers, computer chips, power generation, and networking equipment will ultimately generate adequate returns, but the companies making those investments keep moving ahead.
Nvidia's earnings report provided another indication that demand for AI infrastructure remains strong, with quarterly revenue more than doubling from a year ago. Spending plans across the industry keep rising as companies race to add computing capacity and build the infrastructure needed to support AI.
There are still questions about the eventual return on the hundreds of billions being spent, but the debate in financial markets has done little to slow the companies making the investments.

The Return You're Chasing Already Happened
There's a particular kind of investment decision that rarely feels reckless in the moment.
A part of the market has had an exceptional run. The companies are strong. The narrative makes sense. Every time you open your account, those positions seem to be doing exactly what you hoped they would.
So you add more.
That doesn't necessarily feel like chasing returns. It can feel prudent. Why put new money into investments that have lagged when the winners seem to be proving themselves month after month?
The problem is that your brain may be answering a different question than the one your portfolio needs you to answer.
Instead of asking, What mix of investments gives me the appropriate amount of risk for where I'm trying to go? you begin asking, What's been working lately?
That's where recency bias can quietly take control of a portfolio.
And for successful investors, particularly technology executives whose careers, compensation, and accumulated wealth may already be connected to the same companies or sector, the bigger risk isn't simply choosing the wrong investment next.
It's allowing yesterday's returns to determine how much risk you take tomorrow.
What Just Happened Feels Like What Happens Next
One of the central problems in investing is that our expectations aren't formed in a vacuum.
What we've recently experienced matters.
Robin Greenwood and Andrei Shleifer examined six different measures of investor expectations covering nearly five decades. They found that expectations for future stock returns were strongly tied to past market returns and to how high the market had already climbed.
In plain English, after stocks performed well, investors tended to expect more of the same.
But there was another important finding: those expectations were strongly negatively related to the returns the models actually projected going forward. The periods that left investors feeling more and more optimistic weren't necessarily the periods when future returns looked attractive.
A strong return is evidence of what's happened.
It's not evidence of what must happen next.
Research by Ulrike Malmendier and Stefan Nagel adds another piece of the puzzle. Studying household investing with Survey of Consumer Finances data from 1960 through 2007, they found that people's own experiences with stock and bond returns shaped how much risk they were willing to take and how they allocated their portfolios. More recent experiences carried greater weight.
Our memories, in other words, can become inputs into our portfolios.
And the freshest memories can become some of the most influential.
The Return That Convinced You Is the Return You Already Missed
This tendency shows up in what investors actually do with their money.
Erik Sirri and Peter Tufano studied money flowing into and out of equity mutual funds and found that investors based their buying decisions heavily on past performance. The relationship was particularly strong among the best-performing funds: exceptional prior performance pulled in a disproportionate share of new money.
That makes intuitive sense.
The investment with the best story is often the investment whose performance has already supplied the evidence for that story.
None of this means that last year's winner must become next year's loser.
A technology company can have an extraordinary year and keep performing well. An expensive asset can become more expensive. Market leadership can last much longer than investors expect.
That's why the lesson isn't to bet against whatever has recently performed well.
The lesson is simpler:
The return that convinced you to buy is a return that's already occurred.
Your decision today needs to be justified by what the investment contributes to your portfolio from this point forward.
How Concentration Actually Shows Up
This issue is usually more subtle in practice than an investor deliberately deciding to make a giant bet on last year's winner.
In one recent planning engagement, we worked with an executive whose compensation included salary, bonus, and recurring restricted stock units.
Those RSUs were an important part of the family's wealth-building engine. At the same time, the taxable portfolio was being built to serve an entirely different purpose: helping create enough financial flexibility for the executive to eventually step away from a high-paying career and move toward work optionality.
That distinction mattered.
Each time another block of RSUs vested, there were effectively two choices.
The first was passive: simply allow the employer shares to accumulate.
The second was deliberate: treat the vest as a new capital-allocation decision and ask where those dollars belonged given the family's overall portfolio, future spending needs, and risk capacity.
We chose the second approach.
The planning process called for vested equity to help fund a diversified taxable portfolio rather than allowing employer stock exposure to compound indefinitely by default. That taxable portfolio was spread across multiple asset classes and placed on a quarterly rebalancing schedule.
The important part wasn't predicting whether the employer's stock would outperform.
We didn't need to.
The issue was that the client's salary, future compensation, and a growing portion of financial wealth could otherwise become increasingly dependent on the same company.
And a position can become concentrated without the investor ever consciously deciding, I want more concentration.
Imagine that a $500,000 employer-stock position rises to $750,000.
Nothing was purchased.
No investment decision was made.
But the risk exposure changed materially.
Then another RSU grant vests.
Keeping those shares may feel innocuous because the stock has performed well, and because familiarity with the company can make the investment feel easier to understand than something outside the investor's immediate experience.
Another vest arrives six months later.
Then another.
Over time, what began as compensation can quietly become an investment thesis.
That's the practical danger of recency bias for investors with equity compensation. The bias doesn't always tell you to go out and buy the hottest stock.
Sometimes it simply tells you there's no reason to disturb what's already been working.
Success Can Change the Portfolio Without Your Permission
Now extend that problem across the rest of a high-income household's balance sheet.
The executive owns employer shares.
The 401(k) contains a large-cap U.S. index.
The taxable account owns another broad-market strategy.
Perhaps there are additional technology holdings accumulated over the years.
Viewed separately, none of those investments may appear particularly alarming.
Viewed together, however, they may represent substantially more exposure to the same companies, sector, and economic forces than the investor realizes.
This is particularly important for technology professionals.
Your human capital may already depend on the technology industry.
Your bonus may depend on company performance.
Your future RSU value depends on the employer's stock.
Your existing shares may represent a substantial portion of your financial capital.
And broad-market indexes can add further exposure to some of the same companies that have already driven your wealth higher.
The question, then, isn't simply, Is this a good company?
It may be an exceptional company.
The better portfolio question is:
How much of my financial future should depend on it?
Lisa Meulbroek's research into company stock held by employees illustrates the economic problem created by combining employment exposure with concentrated ownership of employer shares. Even when an employee believes strongly in the company, concentrated employer stock exposes the household to risks that could otherwise be diversified.
That distinction matters because diversification isn't a judgment about whether your company will succeed.
It's a judgment about how much of your family's future should depend on being right about any single outcome.
Why Portfolio Discipline Sometimes Feels Wrong
This is where a disciplined investment process earns its keep.
You establish what role each asset is supposed to play.
You decide how much concentration you're willing to accept.
You determine an appropriate allocation based on the return you need, the risk you can afford to take, your liquidity requirements, taxes, time horizon, and the goals the portfolio ultimately needs to fund.
Then you periodically compare the portfolio you actually own with the portfolio you intended to own.
That last step matters because successful investments don't remain politely inside their original allocations.
They grow.
For an investor receiving equity compensation, there's another layer: new shares may keep arriving even after an existing position has already become large.
That means maintaining the portfolio may require an active process for deciding what happens when shares vest.
Hold?
Sell?
Diversify?
Fund another goal?
The answer will vary by investor. Taxes, trading restrictions, holding periods, liquidity needs, charitable objectives, and the rest of the financial plan all matter.
What shouldn't determine the answer by itself is the fact that the stock has recently gone up.
Sometimes the most important portfolio decision isn't identifying the next winner.
It's recognizing how much your previous winners have already changed your risk exposure.
Don't Ask Your Memory to Vote
The solution to recency bias isn't becoming better at predicting which sector will lead next.
It isn't selling everything that's performed well.
And it certainly isn't reflexively buying whatever performed poorly.
Those approaches simply replace one forecast with another.
The better defense is an investment process that doesn't require you to reconstruct your portfolio strategy every time the market hands you a new reason to feel optimistic or pessimistic.
Build the portfolio around your objectives and risk profile.
Understand your exposure across all of your accounts.
Include employer stock and future equity compensation when evaluating concentration.
Establish parameters for how much risk you're willing to allow any one company, sector, or economic driver to contribute.
And when equity compensation vests, treat those shares as a fresh allocation decision rather than automatically assuming yesterday's allocation should become tomorrow's.
Then periodically compare the portfolio you actually own with the one you deliberately set out to build.
That leads to one useful question to ask this quarter:
Have my recent winners quietly made me more concentrated than I ever consciously chose to be?
If the answer is yes, that doesn't automatically mean those investments should be sold.
Taxes matter. Equity-compensation restrictions matter. Liquidity needs matter. Your broader financial plan matters.
But it does mean the portfolio deserves another look.
Because the job of an investment strategy isn't to own whatever just worked.
It's to maintain the amount and type of risk necessary to get you where you're trying to go, even when the rearview mirror is telling you to do something else.
Sources
Greenwood, Robin, and Andrei Shleifer. "Expectations of Returns and Expected Returns." The Review of Financial Studies, 2014.
https://academic.oup.com/rfs/article-abstract/27/3/714/1580705
Malmendier, Ulrike, and Stefan Nagel. "Depression Babies: Do Macroeconomic Experiences Affect Risk Taking?" The Quarterly Journal of Economics, 2011.
https://academic.oup.com/qje/article-abstract/126/1/373/1901343
Sirri, Erik R., and Peter Tufano. "Costly Search and Mutual Fund Flows." The Journal of Finance, 1998.
https://onlinelibrary.wiley.com/doi/10.1111/0022-1082.00066
Meulbroek, Lisa. "Company Stock in Pension Plans: How Costly Is It?" The Journal of Law and Economics, 2005.
https://www.journals.uchicago.edu/doi/abs/10.1086/430807
Weekly Market Update: Softer Data Cools Rate-Hike Bets
Markets traded higher for a third straight week as participation broadened.
The S&P 500 gained 1.2%, the Nasdaq 100 rose 2.4%, and the Russell 2000 small-cap index rose 1.8%. Both the S&P 500 and Russell 2000 reached new all-time highs.
Growth and high-beta stocks led the market higher, though strength wasn't limited to the largest companies.
The equal-weight S&P 500 gained 1.9%, which suggests participation stayed relatively broad.
Technology rose 2.9%, and Energy was the week's strongest sector as oil prices climbed nearly 5%. International stocks generally kept pace with U.S. equities, while the U.S. dollar was little changed.
Bonds traded higher as investors reduced expectations for another Federal Reserve rate hike, with shorter-maturity bonds outperforming longer-maturity bonds. Gold continued to drift higher, while the VIX fell below 15 and remains near its lowest level of the year.

Key Takeaways
The Labor Market Softened in July
The labor market showed more signs of cooling in July. Employers cut 23,000 jobs, and previously reported gains for May and June were revised lower by a combined 103,000, suggesting hiring had already been weaker than first reported.
Even so, the broader picture hasn't fallen apart. The unemployment rate held relatively low at 4.1%, and private-sector employment rose by 30,000.
The report points to a labor market losing momentum, but not yet the kind of deterioration typically tied to a recession.
Why it matters: A softer labor market weakens one of the arguments for keeping interest rates higher. If employment continues to cool without a meaningful rise in unemployment, the Fed may have less reason to tighten policy further.
Inflation Stayed Contained
The latest inflation reports were relatively encouraging. Consumer prices rose just 0.1% in July, and producer prices were unchanged. Both came in below expectations and helped ease concerns that rising oil prices were pushing inflation broadly higher again.
Energy remains a pressure point. The energy component of CPI is still 14.5% higher than a year ago, but that increase hasn't translated into a similar acceleration across broader inflation measures.
Higher energy prices can squeeze households and businesses without necessarily setting off another broad inflation cycle.
Why it matters: Inflation remains above the Fed's target, but July's reports suggest the recent energy shock hasn't spread meaningfully into the rest of the economy. That reduces some of the immediate pressure on the Fed to respond with higher rates.
September Rate-Hike Odds Fell
The outlook for Fed policy shifted meaningfully over the week. Heading into the employment report, markets were assigning better than a 50% probability to a September hike, with persistent inflation concerns and three dissents at the Fed's July meeting keeping another increase firmly on the table.
Then the data changed the conversation. Expectations for a September hike fell after the weaker payroll report, declined again following Wednesday's CPI release, and moved lower still after Thursday's flat producer-price report. In other words, investors are looking at a different backdrop than they were several weeks ago: a softening labor market alongside relatively contained inflation.
Why it matters: With the Fed offering less forward guidance, each incoming report carries more weight. This week's data shifted the balance away from another near-term increase, though that outlook can change quickly if inflation or employment data surprise again.
AI Demand Stayed Strong
The investment boom around artificial intelligence continues to show up in the companies building its infrastructure. CoreWeave, which buys advanced chips, installs them in data centers, and leases that computing capacity to customers, reported quarterly revenue of $2.58 billion and a backlog that climbed to $104 billion.
Other AI-infrastructure companies also reported strong growth during the week, suggesting demand isn't isolated to a single name.
The story increasingly extends beyond software firms and chipmakers to the data centers, power, networking equipment, and computing capacity needed to train and run more sophisticated AI models.
Why it matters: Questions remain about how much companies will ultimately spend on AI and what returns those investments will generate. Even so, rapid growth in demand for computing capacity suggests the underlying buildout remains strong.
Small-Business Confidence Climbed
Small-business owners grew more optimistic in July. The NFIB Small Business Optimism Index rose to 99.8, its highest reading since August 2025 and above its long-term average.
That's notable given the past several years of higher inflation, elevated borrowing costs, and persistent difficulty finding qualified workers.
Those pressures haven't disappeared, but July's survey showed improvement across several categories, including a meaningful increase in hiring plans.
Since small businesses account for nearly half of private-sector employment, improving sentiment offers a useful read on conditions beneath the surface of the broader economy.
Why it matters: Rising confidence suggests some of the pressures weighing on small businesses may be starting to ease. If that continues, it could support hiring, investment, and activity even as growth elsewhere moderates.
Weekly Market Update: AI Selloff Overshadows the Post-Election Rally
Major indexes fell as a selloff in semiconductor and other AI-related stocks outweighed a broad rally the day after the midterm elections.
The S&P 500 fell -4.7% and the Nasdaq dropped -9.5%, while the Dow Jones slipped -1.6% and the Russell 2000 small-cap index declined -4.5%.
The Equal-Weight S&P 500 fell a more modest -1.4%, and Value outperformed Growth by a wide margin as Momentum and High Beta stocks dropped -16.2% and -13.5%, respectively. Overall, 7 of 11 sectors traded higher, led by Consumer Staples with a gain of 3.6%, while Tech sank -14.0%.
Treasuries rallied as the 10-year yield fell to its lowest level since September. Oil slid -11.1% on hopes of a diplomatic resolution in the Middle East, gold rebounded above $4,000, and the VIX, a measure of expected volatility, jumped above 25.
Key Takeaways
Midterms Deliver a Divided Government
Democrats won majorities in both the House and Senate, which means major legislation will need support from both parties during the final two years of President Trump's term. Markets initially welcomed the outcome, with the S&P 500 gaining 1.6% on Wednesday as election uncertainty eased and investors anticipated fewer big policy changes.
Treasury yields declined, reflecting expectations of more constrained fiscal spending, although falling oil prices also contributed to the move. Policy uncertainty didn't disappear, however. As discussed below, tech stocks weakened amid concerns about potentially tighter AI regulation.
Why it matters: Divided government (Congress and the Executive) makes sweeping legislative changes more difficult. Attention now turns to deadlines that need bipartisan agreement, such as the debt limit in 2027, while the White House can still act on trade through executive action.
Chip Stocks Lead an AI Selloff
The pressure started last Friday, when Intel fell about -29%, its worst day since 1974, after a weak outlook. The selling spread across chipmakers and continued this week, despite strong results from AMD, whose data-center revenue nearly doubled from a year ago.
Tuesday's midterm elections, in which voters approved local ballot measures restricting data-center construction, weighed on the group as investors considered the prospect of tighter AI regulation and delays to planned projects. An index of semiconductor companies fell more than -12% on Thursday and closed at its lowest level since April.
Why it matters: The debate over AI has broadened from whether the spending will pay off to whether the buildout can continue at its planned pace. That's a question strong earnings alone can't settle.
Oil Slides on Hopes for a Hormuz Deal
Under a plan drafted with Qatari mediators, Iran said it could reopen the Strait of Hormuz within two days of a deal if the U.S. meets its conditions, including lifting sanctions. The U.S. hasn't accepted the terms, but oil prices fell as traders priced in the probability of a negotiated settlement.
West Texas Intermediate crude fell -11.1% for the week, and Brent, the international benchmark, dropped below $100 after hitting a six-month high last Friday.
Why it matters: Lower oil prices ease one of the main sources of this year's inflation pressure, and the decline helped pull Treasury yields lower.
Manufacturing and Hiring Hold Up
The ISM manufacturing index rose to 55.5 in October, above expectations and one of its strongest readings since 2022, while its prices index remained elevated at 75.2. A separate survey showed services activity slowed slightly but continued to grow.
In the labor market, employers added 86,000 jobs according to ADP, above the roughly 75,000 economists expected, and initial jobless claims fell to 189,000, matching their lowest level of the year. Abroad, the Bank of England raised its policy rate to 4.00%, its first increase since 2023.
Why it matters: The weakness in technology stocks hasn't spilled into the broader economy so far, which helps explain why markets continue to price a 70% probability of a December rate hike.